Leo Dryfruits (VANDU) Q2 FY27 Profit Lags Behind an 83% Revenue Surge
The company's Q2 FY27 revenue nearly doubled year-on-year, but a sharp margin contraction held profit growth to just 20%.
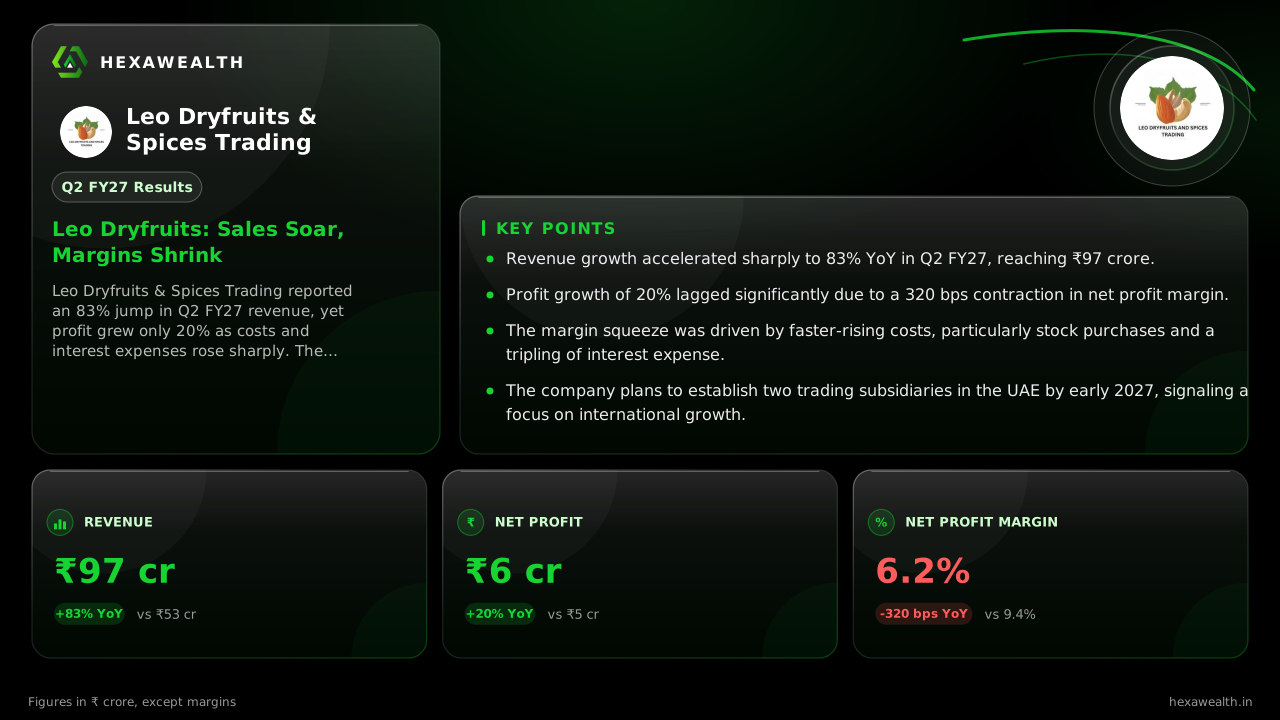
Leo Dryfruits & Spices Trading reported an 83% jump in Q2 FY27 revenue, yet profit grew only 20% as costs and interest expenses rose sharply. The board also approved plans to set up two subsidiaries in the UAE.
For a fast-growing food trader, the test is turning top-line momentum into bottom-line gains. Leo Dryfruits & Spices Trading passed the first part with flying colors in the September quarter, but the second proved much harder.
Revenue soared 83% year-on-year to ₹97 crore, while net profit grew a more modest 20% to ₹6 crore. The net profit margin compressed by 320 basis points to 6.2%, down from 9.4% a year ago. Sequentially, the story was identical, with revenue up 83% from the March quarter but profitability again taking a hit.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 18.0
- Revenue (₹ Cr), Q4 FY25: 87.0
- Revenue (₹ Cr), Q2 FY26: 53.0
- Revenue (₹ Cr), Q4 FY26: 53.0
- Revenue (₹ Cr), Q2 FY27: 97.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 8.0
- Profit (₹ Cr), Q2 FY26: 5.0
- Profit (₹ Cr), Q4 FY26: 5.0
- Profit (₹ Cr), Q2 FY27: 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 18.0
- Revenue (₹ Cr), Q4 FY25: 87.0
- Revenue (₹ Cr), Q2 FY26: 53.0
- Revenue (₹ Cr), Q4 FY26: 53.0
- Revenue (₹ Cr), Q2 FY27: 97.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 8.0
- Profit (₹ Cr), Q2 FY26: 5.0
- Profit (₹ Cr), Q4 FY26: 5.0
- Profit (₹ Cr), Q2 FY27: 6.0
Net Profit Margin
- Net Profit Margin, Q2 FY25: 11.1%
- Net Profit Margin, Q4 FY25: 9.2%
- Net Profit Margin, Q2 FY26: 9.4%
- Net Profit Margin, Q4 FY26: 9.4%
- Net Profit Margin, Q2 FY27: 6.2%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 97.0YoY +83% | 53.0 |
| Profit (₹ Cr) | 6.0YoY +20% | 5.0 |
| Net Profit Margin | 6.2%YoY -34% | 9.4% |
Why the profit didn't keep up
Total expenses jumped 91.3%, outpacing revenue growth. According to a report from Multibagg.ai, purchases of stock-in-trade were the main driver, rising by ₹34.5 crore to fund the sales surge. Interest expense tripled year-on-year to ₹3 crore, reflecting higher borrowings to support working capital needs.
The cash flow statement, cited by MarketPing, shows the strain. Operating cash flow was negative ₹8.96 crore for the half-year, as receivables and inventory swelled to support growth. This was funded by a ₹14.34 crore rise in long-term borrowings.
The plan to stretch further
Management is betting on international expansion to sustain momentum. The board approved, in principle, setting up two 80%-owned trading subsidiaries in the UAE, targeting completion by February 2027.
Live Chart
· VANDU
(BSE)
ISIN: INE0RH001011
A report from MCapital estimates this move could add ₹10-18 crore to net debt. It also projects full-year revenue growth of 29-40% over FY26, but with operating margins expected to fall another 1-2.5 percentage points.
Key Points
- Revenue growth accelerated sharply to 83% YoY in Q2 FY27, reaching ₹97 crore.
- Profit growth of 20% lagged significantly due to a 320 bps contraction in net profit margin.
- The margin squeeze was driven by faster-rising costs, particularly stock purchases and a tripling of interest expense.
- The company plans to establish two trading subsidiaries in the UAE by early 2027, signaling a focus on international growth.
Hexa Perspective
The quarter reveals a business growing rapidly but on capital that is becoming more expensive. The valuation—a P/E of 9.6, a 78% discount to the industry—prices in these margin and cash-flow concerns.
The next few quarters will show if the UAE expansion can open higher-margin channels or simply extend the current capital-intensive model. For the growth to reward shareholders, the top-line engine must eventually start lifting profitability.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.