Novateor (NOVATEOR) Q2 FY27 Profit Up 550% on Lower Sales, But Core Business Falters
Novateor Research Laboratories posted a sharp profit jump in Q2 FY27, but a 38.5% revenue drop and an auditor's red flag on interest income raise questions about its core oral care business.
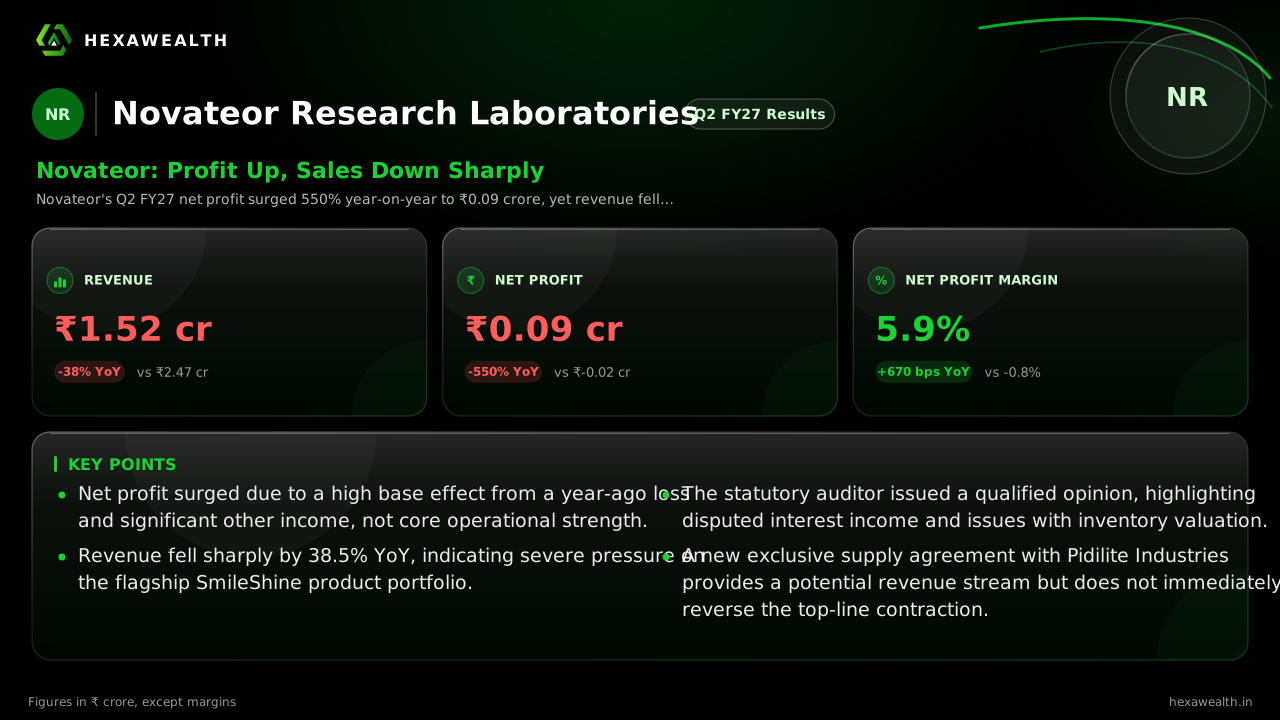
Novateor's Q2 FY27 net profit surged 550% year-on-year to ₹0.09 crore, yet revenue fell sharply by 38.5%. The profit is supported by other income, while its core SmileShine business faces a shrinking top line and operational challenges.
For Novateor Research Laboratories, the September quarter delivered a stark contradiction: a soaring bottom line atop a shrinking business. The maker of SmileShine teeth whitening products reported a net profit of ₹0.09 crore, a 550% jump from a loss a year ago. Yet this profit arrived alongside a 38.5% collapse in revenue to ₹1.52 crore, revealing a business where the core is weakening.
The numbers show a company moving in opposite directions. Sequentially, revenue improved 11.8% from the March quarter, but profit fell 25% as margins contracted.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 0.79
- Revenue (₹ Cr), Q4 FY25: 1.98
- Revenue (₹ Cr), Q2 FY26: 2.47
- Revenue (₹ Cr), Q4 FY26: 1.36
- Revenue (₹ Cr), Q2 FY27: 1.52
- Profit (₹ Cr), Q2 FY25: 0.03
- Profit (₹ Cr), Q4 FY25: 0.05
- Profit (₹ Cr), Q2 FY26: -0.02
- Profit (₹ Cr), Q4 FY26: 0.12
- Profit (₹ Cr), Q2 FY27: 0.09
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 0.79
- Revenue (₹ Cr), Q4 FY25: 1.98
- Revenue (₹ Cr), Q2 FY26: 2.47
- Revenue (₹ Cr), Q4 FY26: 1.36
- Revenue (₹ Cr), Q2 FY27: 1.52
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.03
- Profit (₹ Cr), Q4 FY25: 0.05
- Profit (₹ Cr), Q2 FY26: -0.02
- Profit (₹ Cr), Q4 FY26: 0.12
- Profit (₹ Cr), Q2 FY27: 0.09
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 3.8
- Net Profit Margin (%), Q4 FY25: 2.5
- Net Profit Margin (%), Q2 FY26: -0.8
- Net Profit Margin (%), Q4 FY26: 8.8
- Net Profit Margin (%), Q2 FY27: 5.9
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 1.52YoY -38% | 2.47 |
| Profit (₹ Cr) | 0.09YoY +550% | -0.02 |
| Net Profit Margin (%) | 5.9YoY +838% | -0.8 |
The Profit That Wasn't From Operations
The profit leap is largely not from selling products. According to mCapital.in, the company's reported profit for the half-year relies significantly on ₹1.66 crore of disputed interest income recognized despite legal uncertainty. Excluding this, the core oral care operations remain loss-making. The auditor's qualified opinion, cited by Newboard.in, flags this along with unverifiable inventory and missing provisions.
A Top Line Under Siege
The steep annual revenue decline points to fundamental challenges in scaling the branded SmileShine business. Management has cited low customer awareness and pricing pressure from regional brands as key threats. A new three-year supply deal with Pidilite Industries, announced in October, offers a potential anchor, but the current sales run-rate is concerning.
Analysts at mCapital.in estimate the annualized revenue is tracking about 30% below last year's level, with operating losses deepening. This suggests the company's foray into new products like herb-based toothpaste sachets has yet to offset the broader decline.
Live Chart
· NOVATEOR
(BSE)
ISIN: INE08JY01013
Key Points
- Net profit surged due to a high base effect from a year-ago loss and significant other income, not core operational strength.
- Revenue fell sharply by 38.5% YoY, indicating severe pressure on the flagship SmileShine product portfolio.
- The statutory auditor issued a qualified opinion, highlighting disputed interest income and issues with inventory valuation.
- A new exclusive supply agreement with Pidilite Industries provides a potential revenue stream but does not immediately reverse the top-line contraction.
Hexa Perspective
The quarter underscores a business at a crossroads. The reported profit is a fragile construct, heavily dependent on non-operational and contested income. For the stock's premium valuation—trading at over 160 times earnings—to hold, investors need to see a convincing turnaround in the core revenue trajectory.
The Pidilite contract and planned move to a semi-automated plant in Sanand are positive steps, but as Newboard.in notes, these plans lack concrete timelines. The path to sustainable profitability runs directly through rebuilding sales volume for SmileShine in a crowded, price-sensitive market.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.