Vashishtha Luxury Fashion (VASHISHTHA) Q4 FY26 Profit Dives 18% Despite Surging Revenue
A sharp rise in total expenses, outpacing strong revenue growth, led to a significant contraction in net profit margin for the March quarter.
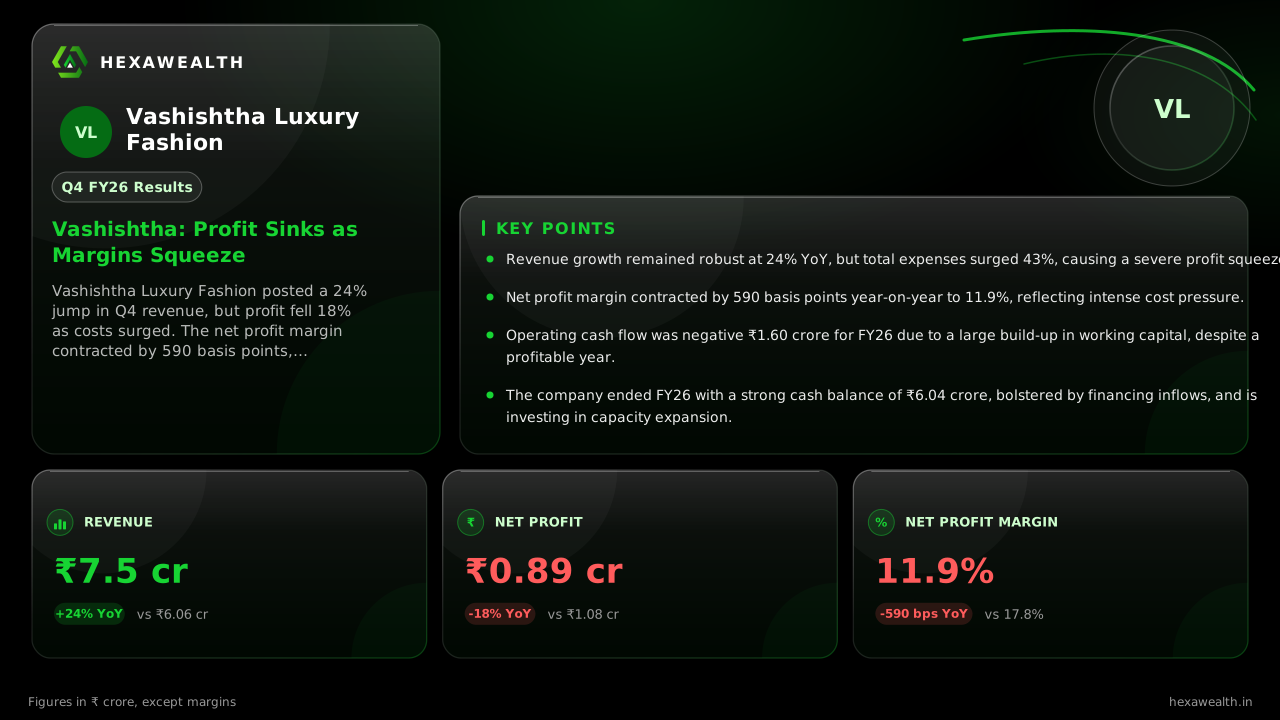
Vashishtha Luxury Fashion posted a 24% jump in Q4 revenue, but profit fell 18% as costs surged. The net profit margin contracted by 590 basis points, highlighting a severe profitability squeeze.
Vashishtha Luxury Fashion’s final quarter capped a year of rapid sales expansion with a stark profitability warning. Revenue climbed 24% year-on-year to ₹7.5 crore, but net profit fell 18% to ₹0.89 crore, as costs grew faster than the top line.
The numbers reveal a business growing but struggling to convert sales into earnings. Sequentially, revenue rose 11% from the September quarter, yet profit dropped 20%. The net profit margin fell to 11.9%, down 590 basis points from a year ago and 440 points from the prior quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 6.06
- Revenue (₹ Cr), Q2 FY26: 6.79
- Revenue (₹ Cr), Q4 FY26: 7.50
- Profit (₹ Cr), Q4 FY25: 1.08
- Profit (₹ Cr), Q2 FY26: 1.11
- Profit (₹ Cr), Q4 FY26: 0.89
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 6.06
- Revenue (₹ Cr), Q2 FY26: 6.79
- Revenue (₹ Cr), Q4 FY26: 7.50
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 1.08
- Profit (₹ Cr), Q2 FY26: 1.11
- Profit (₹ Cr), Q4 FY26: 0.89
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 17.8
- Net Profit Margin (%), Q2 FY26: 16.3
- Net Profit Margin (%), Q4 FY26: 11.9
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 7.50YoY +24% | 6.06 |
| Profit (₹ Cr) | 0.89YoY -18% | 1.08 |
| Net Profit Margin (%) | 11.9YoY -33% | 17.8 |
Why the bottom line fell apart
Total expenses surged 43% year-on-year, far outpacing revenue growth. A report from Newboard.in shows the operating profit margin for the half-year ending March 2026 halved to 12.4%, from 26.2% a year earlier. This indicates a fundamental cost pressure, likely from materials and employee costs, which The Economic Times notes accounted for over 21% of operating revenue in FY26.
A cash-rich but cash-consuming business
Despite posting a full-year profit of ₹2.01 crore, operating cash flow was deeply negative at -₹1.60 crore. Multibagg.ai analysis shows this was driven by a massive ₹4.02 crore increase in working capital, mainly from higher trade receivables and other current assets. The paradox is a balance sheet flush with cash—up from ₹0.09 crore to ₹6.04 crore in FY26—funded entirely by a ₹7.79 crore inflow from financing activities, per the cash flow statement.
The outlook beyond the squeeze
The company is investing for growth, having imported a multi-head embroidery machine in July 2026 as part of its capital expenditure. The broader market tailwind is favorable; a Deloitte India study cited by Apparel Resources notes India's premium apparel segment is projected to grow at over 45% CAGR, driven by a shift to quality-led consumption. For Vashishtha, the immediate task is to arrest the margin decline. Management has not provided formal guidance, but the H1 FY27 run-rate already exceeds FY26's full-year profit, suggesting the annual picture may look stronger than this difficult quarter.
Live Chart
· VASHISHTHA
(BSE)
ISIN: INE0WRP01016
Key Points
- Revenue growth remained robust at 24% YoY, but total expenses surged 43%, causing a severe profit squeeze.
- Net profit margin contracted by 590 basis points year-on-year to 11.9%, reflecting intense cost pressure.
- Operating cash flow was negative ₹1.60 crore for FY26 due to a large build-up in working capital, despite a profitable year.
- The company ended FY26 with a strong cash balance of ₹6.04 crore, bolstered by financing inflows, and is investing in capacity expansion.
Hexa Perspective
The quarter presents a classic growth-versus-profitability tension. The 34% revenue CAGR over five years is impressive, but the sudden margin collapse in Q4 demands scrutiny. It points to either a strategic investment in sales that sacrificed near-term margins, or an inability to pass on input cost increases. The cash flow disconnect—profit without cash—adds a layer of quality concern, though the clean balance sheet with zero debt provides a buffer. Investors are weighing strong sectoral demand against the company's ability to demonstrate operating leverage. The next few quarters must show whether this margin squeeze is a temporary blip or a new, less profitable normal.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.