Vani Commercials (VANICOM) Q2 FY27 Profit Dips as Funding Costs Bite Into Loan Growth
The NBFC's loan book surged 41% in six months, but a sharp rise in interest expense pushed its net profit margin down to 14%.
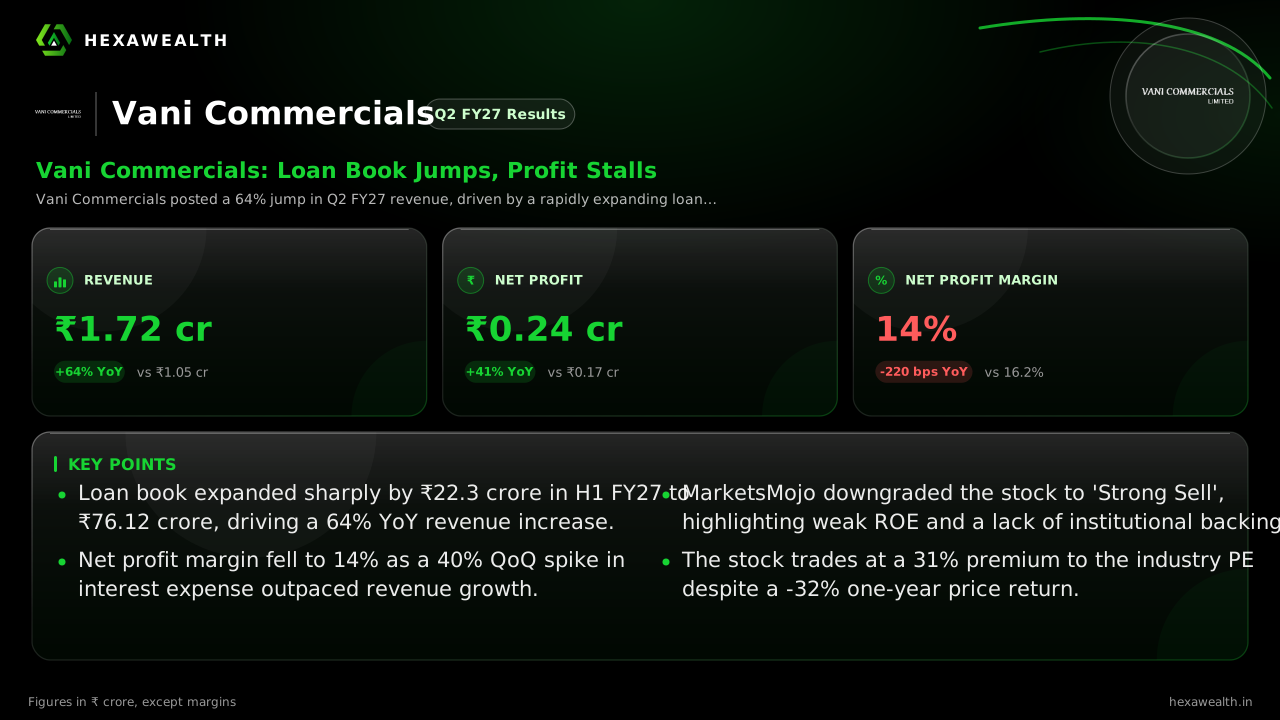
Vani Commercials posted a 64% jump in Q2 FY27 revenue, driven by a rapidly expanding loan book. However, profit fell 4% sequentially as a 40% spike in interest costs squeezed margins, highlighting the pressure on small NBFCs.
For a small NBFC, growth is measured by its loan book. Vani Commercials delivered that in the September quarter, with its lending assets surging 41% in just six months. Yet the cost of funding that expansion bit deeply, leaving profit lower than the quarter before.
The numbers tell a story of top-line momentum and bottom-line pressure. Revenue from operations rose 64% year-on-year to ₹1.72 crore, its highest in at least five quarters. But net profit slipped 4% sequentially to ₹0.24 crore, as the net profit margin contracted by 210 basis points to 14%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 1.31
- Revenue (₹ Cr), Q2 FY26: 1.05
- Revenue (₹ Cr), Q4 FY26: 1.55
- Revenue (₹ Cr), Q1 FY27: 1.58
- Revenue (₹ Cr), Q2 FY27: 1.72
- Profit (₹ Cr), Q1 FY26: 0.20
- Profit (₹ Cr), Q2 FY26: 0.17
- Profit (₹ Cr), Q4 FY26: 0.09
- Profit (₹ Cr), Q1 FY27: 0.25
- Profit (₹ Cr), Q2 FY27: 0.24
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 1.31
- Revenue (₹ Cr), Q2 FY26: 1.05
- Revenue (₹ Cr), Q4 FY26: 1.55
- Revenue (₹ Cr), Q1 FY27: 1.58
- Revenue (₹ Cr), Q2 FY27: 1.72
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY26: 0.20
- Profit (₹ Cr), Q2 FY26: 0.17
- Profit (₹ Cr), Q4 FY26: 0.09
- Profit (₹ Cr), Q1 FY27: 0.25
- Profit (₹ Cr), Q2 FY27: 0.24
Net Profit Margin (%)
- Net Profit Margin (%), Q1 FY26: 15.1
- Net Profit Margin (%), Q2 FY26: 16.2
- Net Profit Margin (%), Q4 FY26: 5.8
- Net Profit Margin (%), Q1 FY27: 16.1
- Net Profit Margin (%), Q2 FY27: 14.0
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1.72YoY +64% | 1.58 | 1.05 |
| Profit (₹ Cr) | 0.24YoY +41% | 0.25 | 0.17 |
| Net Profit Margin (%) | 14.0YoY -14% | 16.1 | 16.2 |
The squeeze from rising rates
The culprit was a 40% quarter-on-quarter jump in interest expense to ₹0.47 crore. According to a report by multibagg.ai, this surge in funding costs coincided with the loan book swelling to ₹76.12 crore. For a company that depends on borrowings to fund its lending, higher market rates are a direct hit to profitability.
This pressure is not unique to Vani Commercials. The Economic Times notes the NBFC sector faces a tougher second half as rising interest rates push up funding costs. The challenge for small lenders is to pass these costs on to borrowers without losing business.
A valuation disconnect
The market's reaction was muted, with the stock closing flat at ₹8 on results day. Yet analysts at MarketsMojo took a dimmer view, downgrading the stock to 'Strong Sell' after the results. They cited weak fundamentals, including a return on equity of just 6.76% and the absence of institutional investors.
Live Chart
· VANICOM
(BSE)
ISIN: INE661Q01017
This creates a tension. The company's loan growth is strong, but its ability to turn that into shareholder returns is in question. The valuation, at a 31% premium to the industry PE, seems to ignore these structural concerns.
Key Points
- Loan book expanded sharply by ₹22.3 crore in H1 FY27 to ₹76.12 crore, driving a 64% YoY revenue increase.
- Net profit margin fell to 14% as a 40% QoQ spike in interest expense outpaced revenue growth.
- MarketsMojo downgraded the stock to 'Strong Sell', highlighting weak ROE and a lack of institutional backing.
- The stock trades at a 31% premium to the industry PE despite a -32% one-year price return.
Hexa Perspective
The quarter underscores the classic NBFC bind: growth is available but expensive. Vani Commercials is clearly lending more, yet the cost of that capital is rising faster than what it earns, squeezing margins.
The path forward hinges on its pricing power and asset quality, which remains undisclosed. If it cannot reprice its loans or if credit costs rise, the margin pressure will persist. Investors are left weighing rapid asset growth against persistently weak returns on capital, a disconnect the market has yet to resolve.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.