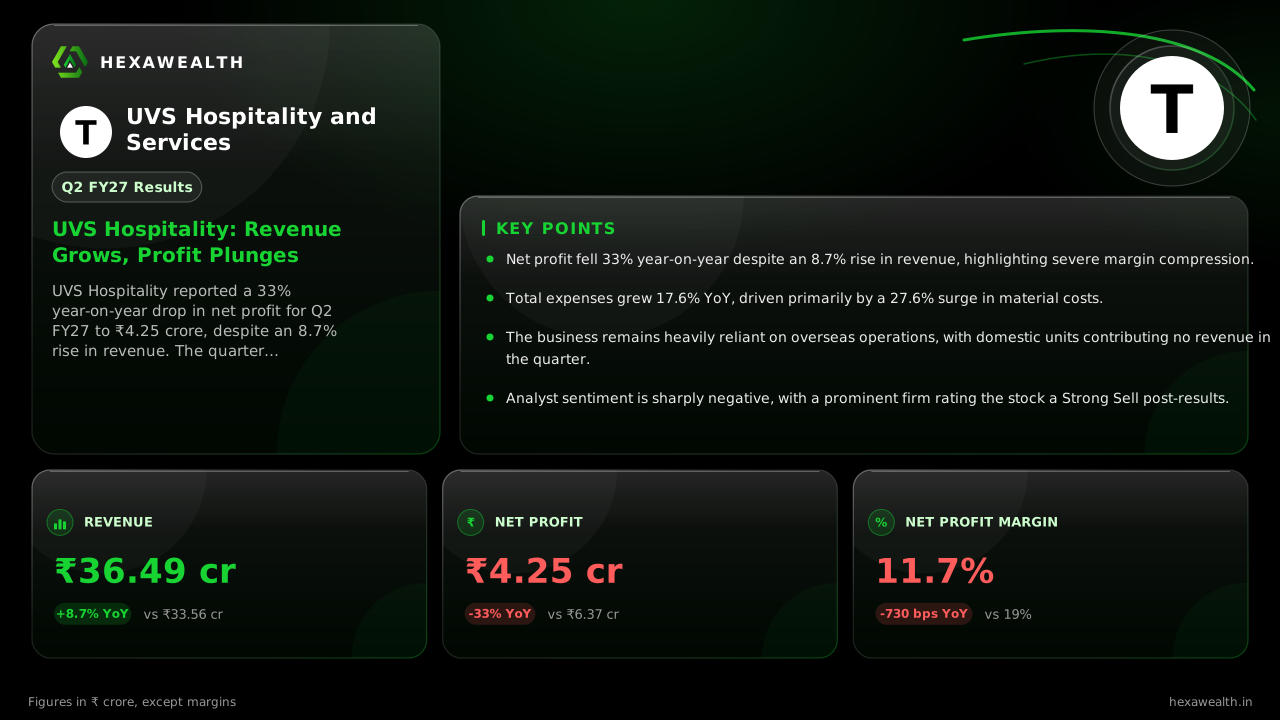
UVS Hospitality reported a 33% year-on-year drop in net profit for Q2 FY27 to ₹4.25 crore, despite an 8.7% rise in revenue. The quarter highlights a severe margin squeeze as total expenses grew nearly twice as fast as the top line.
For UVS Hospitality, the story of its transition from an NBFC to a food processor is written in volatile quarterly swings. The September quarter delivered a stark lesson: revenue growth alone does not guarantee profit, especially when costs run far ahead.
The numbers show a business under pressure. Revenue of ₹36.49 crore grew 8.7% from a year ago, but fell 19% sequentially from a strong June quarter. Profit collapsed 33% year-on-year to ₹4.25 crore, and the net profit margin shrank by 730 basis points to 11.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Revenue (₹ Cr), Q2 FY26 (Sep 2025): 33.56
Revenue (₹ Cr), Q3 FY26 (Dec 2025): 36.41
Revenue (₹ Cr), Q4 FY26 (Mar 2026): 37.25
Revenue (₹ Cr), Q1 FY27 (Jun 2026): 45.04
Revenue (₹ Cr), Q2 FY27 (Sep 2026): 36.49
Profit (₹ Cr), Q2 FY26 (Sep 2025): 6.37
Profit (₹ Cr), Q3 FY26 (Dec 2025): 6.21
Profit (₹ Cr), Q4 FY26 (Mar 2026): 2.35
Profit (₹ Cr), Q1 FY27 (Jun 2026): 7.91
Profit (₹ Cr), Q2 FY27 (Sep 2026): 4.25
Revenue (₹ Cr)
Revenue (₹ Cr), Q2 FY26 (Sep 2025): 33.56
Revenue (₹ Cr), Q3 FY26 (Dec 2025): 36.41
Revenue (₹ Cr), Q4 FY26 (Mar 2026): 37.25
Revenue (₹ Cr), Q1 FY27 (Jun 2026): 45.04
Revenue (₹ Cr), Q2 FY27 (Sep 2026): 36.49
Profit (₹ Cr)
Profit (₹ Cr), Q2 FY26 (Sep 2025): 6.37
Profit (₹ Cr), Q3 FY26 (Dec 2025): 6.21
Profit (₹ Cr), Q4 FY26 (Mar 2026): 2.35
Profit (₹ Cr), Q1 FY27 (Jun 2026): 7.91
Profit (₹ Cr), Q2 FY27 (Sep 2026): 4.25
Net Profit Margin (%)
Net Profit Margin (%), Q2 FY26 (Sep 2025): 19.0
Net Profit Margin (%), Q3 FY26 (Dec 2025): 17.1
Net Profit Margin (%), Q4 FY26 (Mar 2026): 6.3
Net Profit Margin (%), Q1 FY27 (Jun 2026): 17.6
Net Profit Margin (%), Q2 FY27 (Sep 2026): 11.7
Metric
CurrentQ2 FY27 (Sep 2026)
PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
36.49
45.04
Profit (₹ Cr)
4.25
7.91
Net Profit Margin (%)
11.7
17.6
Why the bottom line buckled
Revenue growth was entirely overshadowed by a 17.6% surge in total expenses year-on-year. According to a report by Cruxal, the cost of materials consumed jumped 27.6% and now eats up 40.8% of revenue, up from 34.8% a year ago. This was the single biggest driver of the margin collapse.
Finance costs also rose 84% year-on-year, though from a low base. Other income, which provided a cushion in past quarters, collapsed by 94% to just ₹0.01 crore. The result is a top line that grew, but a cost structure that grew much faster.
A business in transition
The company’s standalone Indian restaurant operations were temporarily closed, contributing no revenue. MarketsMojo notes that about 89% of sales came from its overseas subsidiary, concentrating both performance and risk. This reliance on a single foreign unit adds a layer of execution uncertainty to its ongoing business model shift.
Live Chart
· UVS
(BSE)
ISIN: INE528C01018
Management is taking steps to accelerate growth, including a planned acquisition of a stake in Calcio Restaurants. However, the immediate challenge is restoring profitability. The half-year picture is brighter, with profit up 61.5%, but the steep Q2 decline raises questions about quarterly consistency.
The market's verdict
The stock closed at ₹63.63 on November 13, down over 52% in the past year. Following the results, MarketsMoji issued a Strong Sell recommendation, citing deteriorating profitability, weak capital efficiency, and high earnings volatility. The firm's analysis points to fundamental weaknesses that outweigh any valuation appeal.
Key Points
Net profit fell 33% year-on-year despite an 8.7% rise in revenue, highlighting severe margin compression.
Total expenses grew 17.6% YoY, driven primarily by a 27.6% surge in material costs.
The business remains heavily reliant on overseas operations, with domestic units contributing no revenue in the quarter.
Analyst sentiment is sharply negative, with a prominent firm rating the stock a Strong Sell post-results.
“
Hexa Perspective
The quarter exposes the core tension in UVS Hospitality's transformation. It can generate revenue, but not yet at a sustainable level of profitability. The margin squeeze from input costs is acute and likely to persist in the near term, given the commodity-driven nature of the food business.
The path forward hinges on management's ability to pass on costs, achieve operating leverage, and successfully integrate new acquisitions. Until profitability stabilises, the stock's deep discount to its 52-week high reflects justified investor caution over this volatile transition story.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were UVS Hospitality's Q2 FY27 results?
UVS Hospitality reported Q2 FY27 revenue of ₹36.49 crore, an 8.7% increase year-on-year. However, net profit fell 33.3% to ₹4.25 crore. The net profit margin compressed sharply to 11.7% from 19.0% in the same quarter last year.
Why did UVS Hospitality's Q2 FY27 profit drop 33% despite higher sales?
UVS Hospitality's profit dropped because expenses grew much faster than revenue. Total expenses rose 17.6% year-on-year, largely due to a 27.6% jump in material costs, as reported by Cruxal. This severe cost inflation crushed margins even as sales increased.
What was UVS Hospitality's Q2 FY27 net profit?
UVS Hospitality's net profit for the quarter ended September 2026 (Q2 FY27) was ₹4.25 crore. This represents a 33.3% decline from the ₹6.37 crore profit reported in the same quarter of the previous fiscal year.
Why did UVS Hospitality's revenue decline 19% quarter-on-quarter in Q2 FY27?
UVS Hospitality's revenue fell 19% sequentially from Q1 FY27, indicating significant quarterly volatility. This drop followed an exceptionally strong previous quarter and highlights the lumpiness in the company's business operations as it transitions its model.
What caused the sharp drop in UVS Hospitality's other income in Q2 FY27?
UVS Hospitality's other income collapsed by 94% year-on-year to just ₹0.01 crore in Q2 FY27. This removed a cushion that had supported profitability in prior periods, exacerbating the impact of rising operational costs on the bottom line.
What guidance did UVS Hospitality management provide for future growth?
While specific quarterly guidance wasn't detailed in the research, management is taking proactive steps for growth. This includes plans to acquire a stake in Calcio Restaurants and a focus on expanding in the food and beverage sector, as noted in its annual report.
What is the status of UVS Hospitality's working capital and cash flow?
According to an analysis by mcapital.in, UVS Hospitality is in a net-cash position as of September 2026, with cash rising to ₹21.9 crore. This strong balance sheet provides financial flexibility despite the quarterly profit pressures.
What were the analyst estimates for UVS Hospitality's Q2 FY27 results?
The provided research snippets do not contain specific analyst consensus estimates for UVS Hospitality's Q2 FY27 results. The reported figures are compared against the company's own historical performance from the previous year and quarter.
Have any major brokerages changed their rating for UVS Hospitality after Q2 FY27?
Yes, following the results, MarketsMojo issued a Strong Sell rating for UVS Hospitality. Their analysis cited deteriorating profitability, margin compression, weak capital efficiency, and high earnings volatility as key reasons for the negative view.
How did UVS Hospitality's stock price react to the Q2 FY27 results?
According to MarketsMojo alerts, the stock price showed a muted reaction around the results announcement time, moving slightly. However, the stock is down over 52% in the past year, reflecting broader investor concern over the company's fundamentals.
What are the key risks for UVS Hospitality in its new food processing business?
Key risks include severe margin compression from input cost volatility, high earnings volatility, execution challenges in transitioning from an NBFC, and heavy reliance on a single overseas subsidiary for almost all its revenue and profit.
What drove UVS Hospitality's strong performance in Q1 FY27?
In Q1 FY27 (June 2026), UVS Hospitality reported sales of ₹45.04 crore and a net profit of ₹7.91 crore. This represented very strong growth from a low base in the year-ago period, but the momentum sharply reversed in the following September quarter.
UVS Hospitality Q2 profit drop
UVS Hospitality's Q2 FY27 net profit dropped 33% year-on-year to ₹4.25 crore. The decline was caused by a severe margin squeeze, as total expenses grew 17.6% while revenue increased only 8.7%, with material costs being the primary pressure point.
UVS Hospitality Q2 FY27 results August 2026
UVS Hospitality announced its Q2 FY27 results for the period ending September 2026 in November 2026. The company reported revenue of ₹36.49 crore and a net profit of ₹4.25 crore, marking a significant profit decline from the previous year due to soaring costs.