Uravi Defence (URAVIDEF) Q2 FY27 Profit Surge Relies on One-Off Income
Uravi Defence's Q2 net profit soared 113% sequentially, but its core operations slipped into the red as material costs surged and margins collapsed.
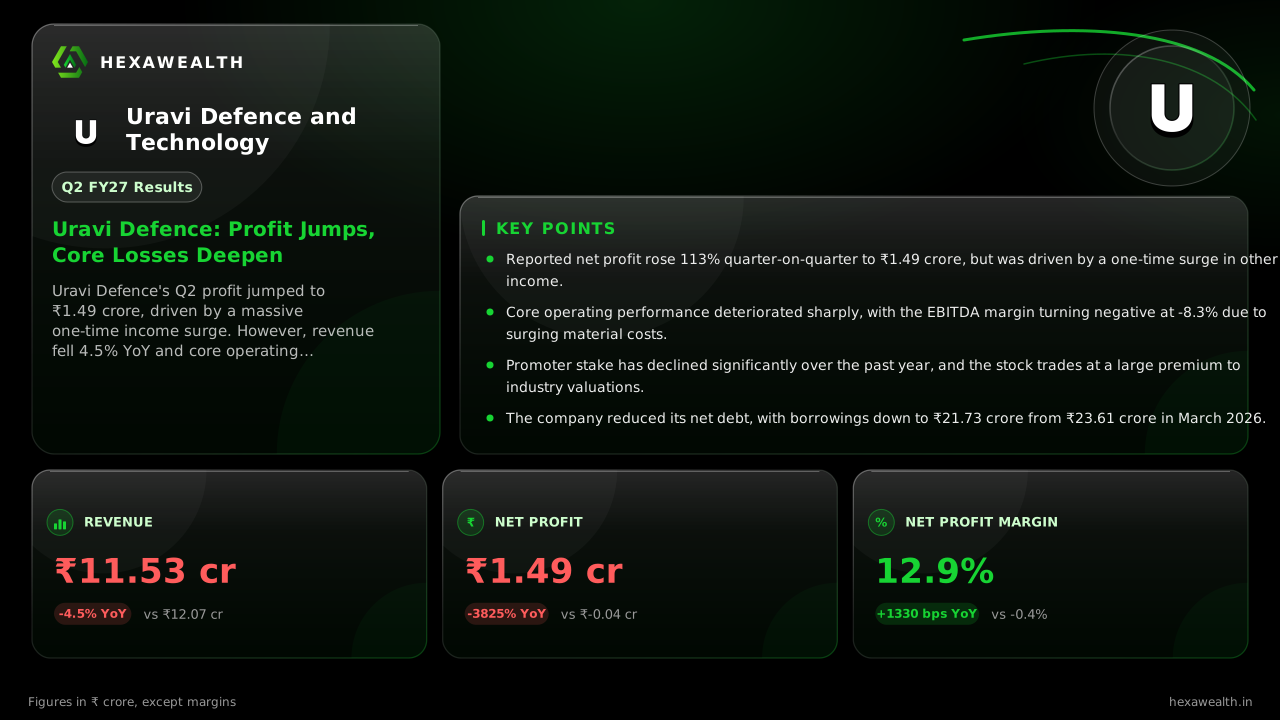
Uravi Defence's Q2 profit jumped to ₹1.49 crore, driven by a massive one-time income surge. However, revenue fell 4.5% YoY and core operating margins turned deeply negative, highlighting underlying business stress.
For an auto ancillary firm, the real test is whether its core manufacturing can turn a profit. Uravi Defence's September quarter passed that test only on paper, as a massive one-off income item delivered a headline profit while its main business bled.
Revenue of ₹11.53 crore was down 4.5% from a year ago, though up 11.6% from the June quarter. The reported net profit of ₹1.49 crore was a sharp 113% sequential jump, turning around from a loss a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep '25): 12.07
- Revenue (₹ Cr), Q3 FY26 (Dec '25): 10.20
- Revenue (₹ Cr), Q4 FY26 (Mar '26): 9.86
- Revenue (₹ Cr), Q1 FY27 (Jun '26): 10.33
- Revenue (₹ Cr), Q2 FY27 (Sep '26): 11.53
- Profit (₹ Cr), Q2 FY26 (Sep '25): -0.04
- Profit (₹ Cr), Q3 FY26 (Dec '25): 0.16
- Profit (₹ Cr), Q4 FY26 (Mar '26): 1.50
- Profit (₹ Cr), Q1 FY27 (Jun '26): 0.70
- Profit (₹ Cr), Q2 FY27 (Sep '26): 1.49
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep '25): 12.07
- Revenue (₹ Cr), Q3 FY26 (Dec '25): 10.20
- Revenue (₹ Cr), Q4 FY26 (Mar '26): 9.86
- Revenue (₹ Cr), Q1 FY27 (Jun '26): 10.33
- Revenue (₹ Cr), Q2 FY27 (Sep '26): 11.53
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep '25): -0.04
- Profit (₹ Cr), Q3 FY26 (Dec '25): 0.16
- Profit (₹ Cr), Q4 FY26 (Mar '26): 1.50
- Profit (₹ Cr), Q1 FY27 (Jun '26): 0.70
- Profit (₹ Cr), Q2 FY27 (Sep '26): 1.49
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep '25): -0.4%
- Net Profit Margin, Q3 FY26 (Dec '25): 1.5%
- Net Profit Margin, Q4 FY26 (Mar '26): 15.2%
- Net Profit Margin, Q1 FY27 (Jun '26): 6.8%
- Net Profit Margin, Q2 FY27 (Sep '26): 12.9%
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 11.53 | 10.33 |
| Profit (₹ Cr) | 1.49 | 0.70 |
| Net Profit Margin | 12.9% | 6.8% |
The One-Off That Made the Quarter
Profit before tax was just ₹0.69 crore. It would have been a significant loss without other income of ₹2.46 crore, which surged over 800% from last year. MarketPing notes this item was 359% of profit before tax.
The research suggests this spike included a ₹2.07 crore gain from surrendering insurance policies. A ₹1.94 crore share of profit from an associate also boosted the consolidated bottom line, as per MCapital.
Why Core Operations Are Slipping
While one-off income soared, the cost to make and sell goods jumped 27% from the prior quarter. Material costs rose 26% year-on-year to ₹7.42 crore, far outpacing the revenue decline.
Live Chart
· URAVIDEF
(BSE)
ISIN: INE568Z01015
This crushed operating margins. The EBITDA margin, excluding other income, was -8.3%, a sharp drop from 5.1% a year ago. Employee costs fell 41% annually, providing some relief, but not enough to offset the material cost surge.
The Market's Skeptical View
The stock fell slightly after the results, reflecting doubt. MarketsMojo points to a 'Strong Sell' rating, citing heavy reliance on non-core income and a collapse in operating margins.
Promoter confidence appears shaky. Their stake has fallen from 58% a year ago to 40% in September 2026, a trend MarketsMojo flags as a red flag. The valuation remains stretched, with a P/E of 124 against an industry average of 47.
Key Points
- Reported net profit rose 113% quarter-on-quarter to ₹1.49 crore, but was driven by a one-time surge in other income.
- Core operating performance deteriorated sharply, with the EBITDA margin turning negative at -8.3% due to surging material costs.
- Promoter stake has declined significantly over the past year, and the stock trades at a large premium to industry valuations.
- The company reduced its net debt, with borrowings down to ₹21.73 crore from ₹23.61 crore in March 2026.
Hexa Perspective
The quarter presents a clear divergence between accounting profit and business health. The sustainability of earnings is in question when core operations are loss-making and reliant on non-recurring items.
Investors are weighing a shrinking promoter stake and high valuation against a slight debt reduction and sequential revenue growth. For the stock to find a floor, the company must demonstrate it can pass on raw material costs or find operating efficiencies in its core manufacturing.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.