Shree Marutinandan (SHREE) Q2 FY27 Profit Doubles Despite a 32% Revenue Drop
The steel tube distributor's Q2 FY27 profit jumped 100% year-on-year to ₹2 crore, as aggressive cost-cutting more than offset a steep fall in sales.
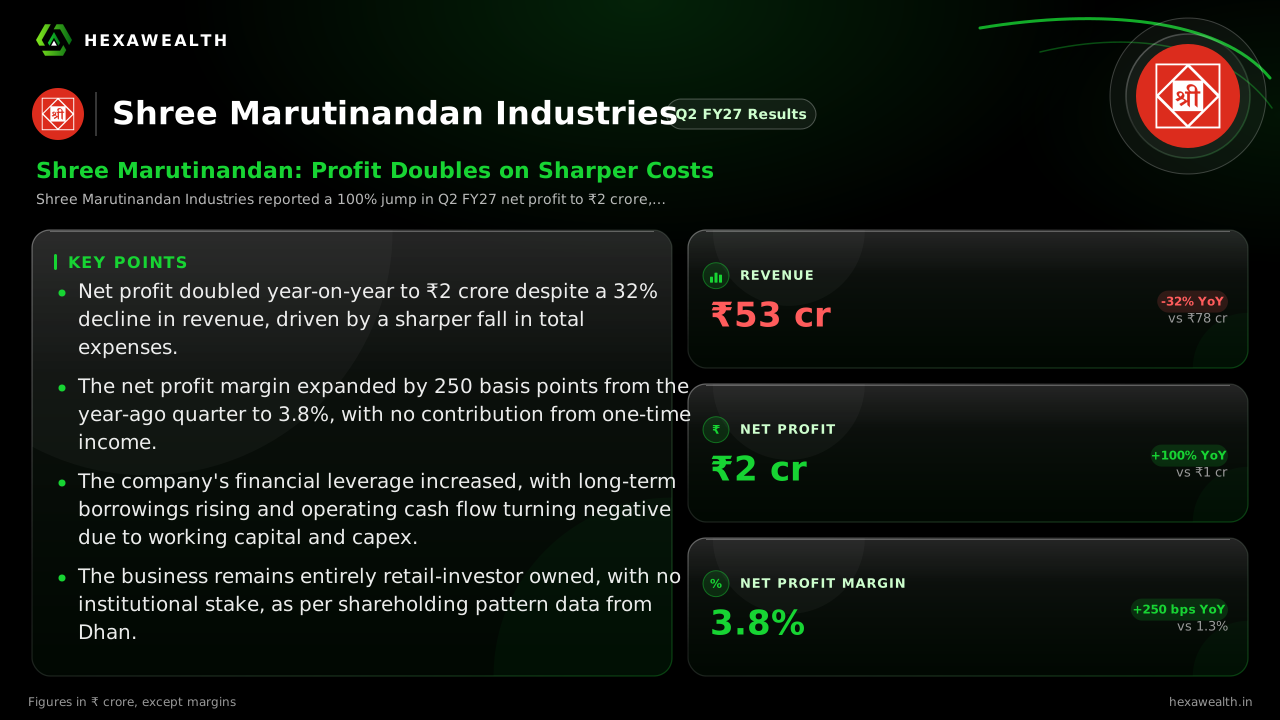
Shree Marutinandan Industries reported a 100% jump in Q2 FY27 net profit to ₹2 crore, even as revenue fell 32% to ₹53 crore. The profit surge was driven by a sharper decline in total expenses, which improved the net profit margin by 250 basis points.
For a steel pipe distributor, revenue swings often tell the demand story. Shree Marutinandan's latest quarter, however, writes a different script: profit doubled on much lower sales, a result of costs falling even faster than the top line.
The numbers show a stark divergence. Revenue for Q2 FY27 stood at ₹53 crore, down 32% from a year ago and 26% from the previous quarter. Net profit, however, rose 100% year-on-year to ₹2 crore, though it fell 33% sequentially from a high base.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 54.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 60.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 78.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 72.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 53.0
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 1.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 2.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 1.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 54.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 60.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 78.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 72.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 53.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 1.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 2.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 1.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.0
Net Profit Margin
- Net Profit Margin, Q2 FY25 (Sep 2024): 1.9%
- Net Profit Margin, Q4 FY25 (Mar 2025): 3.3%
- Net Profit Margin, Q2 FY26 (Sep 2025): 1.3%
- Net Profit Margin, Q4 FY26 (Mar 2026): 4.2%
- Net Profit Margin, Q2 FY27 (Sep 2026): 3.8%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 53.0 | 72.0 |
| Profit (₹ Cr) | 2.0 | 3.0 |
| Net Profit Margin | 3.8% | 4.2% |
The cost cut that drove the profit
The 250-basis-point year-on-year margin expansion was purely operational. According to a report by Multibagg.ai, total expenses fell faster than revenue, dropping ₹27.4 crore in the first half. This was largely due to a significant reduction in inventory-related expenses compared to the year-ago period.
There was no one-time gain flattering the bottom line. Other income was negligible, and interest costs actually rose, as per data from Stockscans.in. The profit jump came from running a leaner operation on lower sales volume.
A stretched balance sheet funds growth
This efficiency, however, comes with a financial trade-off. Reports from mCapital.in indicate operating cash flow was negative ₹2.77 crore in the first half as working capital stretched. Long-term borrowings rose sharply to ₹6.66 crore to fund capital expenditure and advances.
Live Chart
· SHREE
(BSE)
ISIN: INE0QIS01011
The company is investing for the future while navigating a volatile sales cycle. A new order worth ₹1.37 crore from Sahana Marine-Infra Tech, noted by mCapital.in, provides modest near-term visibility but is small relative to annual sales.
Key Points
- Net profit doubled year-on-year to ₹2 crore despite a 32% decline in revenue, driven by a sharper fall in total expenses.
- The net profit margin expanded by 250 basis points from the year-ago quarter to 3.8%, with no contribution from one-time income.
- The company's financial leverage increased, with long-term borrowings rising and operating cash flow turning negative due to working capital and capex.
- The business remains entirely retail-investor owned, with no institutional stake, as per shareholding pattern data from Dhan.
Hexa Perspective
The quarter presents a paradox of improving profitability atop declining scale. The margin lift from cost control is clear, but its sustainability hinges on a return to revenue growth. The rising debt and negative cash flow signal the cost of funding this transition. Investors are left weighing a cheap valuation—a PE of 4.6 against an industry average of 44.1—against the fundamental challenge of stabilizing sales. The path forward requires the new orders and capacity to convert into consistent top-line momentum, without which the margin gains may prove fleeting.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.