Glaam Up Jwel (GLAAMUP) Q4 FY26's Revenue Crashes 63% as Business Stalls, But Margins Inch Up
The commodity trader's Q4 revenue fell sharply year-on-year, though cost cuts lifted the net profit margin slightly from a weak base.
Glaam Up Jwel's Q4 FY26 revenue plunged 63% year-on-year to ₹4.53 crore, but net profit margin improved to 1.8%. The quarter caps a volatile year where trading volumes collapsed, overshadowed by a massive contingent tax penalty.
For a commodity trader like Glaam Up Jwel, volume is everything. The March quarter showed what happens when it vanishes, with revenue crashing 63% from a year ago to just ₹4.53 crore. The slight profit of ₹0.08 crore, a margin improvement from a loss-making base, does little to offset the stark reality of a business in severe contraction.
The numbers tell a story of abrupt deceleration. Sequentially, revenue fell 42% from the September quarter. For the full year FY26, revenue was essentially flat at ₹12.39 crore, while profit rose sharply on a low base of ₹0.01 crore in FY25. The quarterly trajectory, however, points to a steep decline in trading activity as the year closed.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.65
- Revenue (₹ Cr), Q2 FY25: 0.00
- Revenue (₹ Cr), Q4 FY25: 12.26
- Revenue (₹ Cr), Q2 FY26: 7.86
- Revenue (₹ Cr), Q4 FY26: 4.53
- Profit (₹ Cr), Q4 FY24: 0.15
- Profit (₹ Cr), Q2 FY25: 0.03
- Profit (₹ Cr), Q4 FY25: -0.02
- Profit (₹ Cr), Q2 FY26: 0.04
- Profit (₹ Cr), Q4 FY26: 0.08
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.65
- Revenue (₹ Cr), Q2 FY25: 0.00
- Revenue (₹ Cr), Q4 FY25: 12.26
- Revenue (₹ Cr), Q2 FY26: 7.86
- Revenue (₹ Cr), Q4 FY26: 4.53
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 0.15
- Profit (₹ Cr), Q2 FY25: 0.03
- Profit (₹ Cr), Q4 FY25: -0.02
- Profit (₹ Cr), Q2 FY26: 0.04
- Profit (₹ Cr), Q4 FY26: 0.08
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 4.53YoY -63% | 12.26 |
| Profit (₹ Cr) | 0.08YoY +500% | -0.02 |
| Net Margin (%) | 1.8YoY +1000% | -0.2 |
Why the top line collapsed
The company trades aluminum, scrap, and textiles, with metals contributing most revenue. Research from AL Circle and BigMint indicates India's aluminum scrap market faced tight global supply, rising prices, and a weakening rupee through early 2026, raising landed costs. This likely made fresh bookings unviable for a small trader, crushing volumes. The revenue drop was matched by a 64% cut in total expenses, a defensive move to preserve cash as sales evaporated.
The margin mirage and mounting risks
The net profit margin improved to 1.8%, up 200 basis points year-on-year, solely because costs fell in line with the revenue crash. This is not operating leverage but retrenchment. More critically, a report from mcapital.in highlights a ₹22.24 crore CGST penalty shown as a contingent liability, over three times the company's March 2026 net worth of ₹9.99 crore. An old Axis Bank default of ₹2.06 crore is also pending at the Debt Recovery Tribunal.
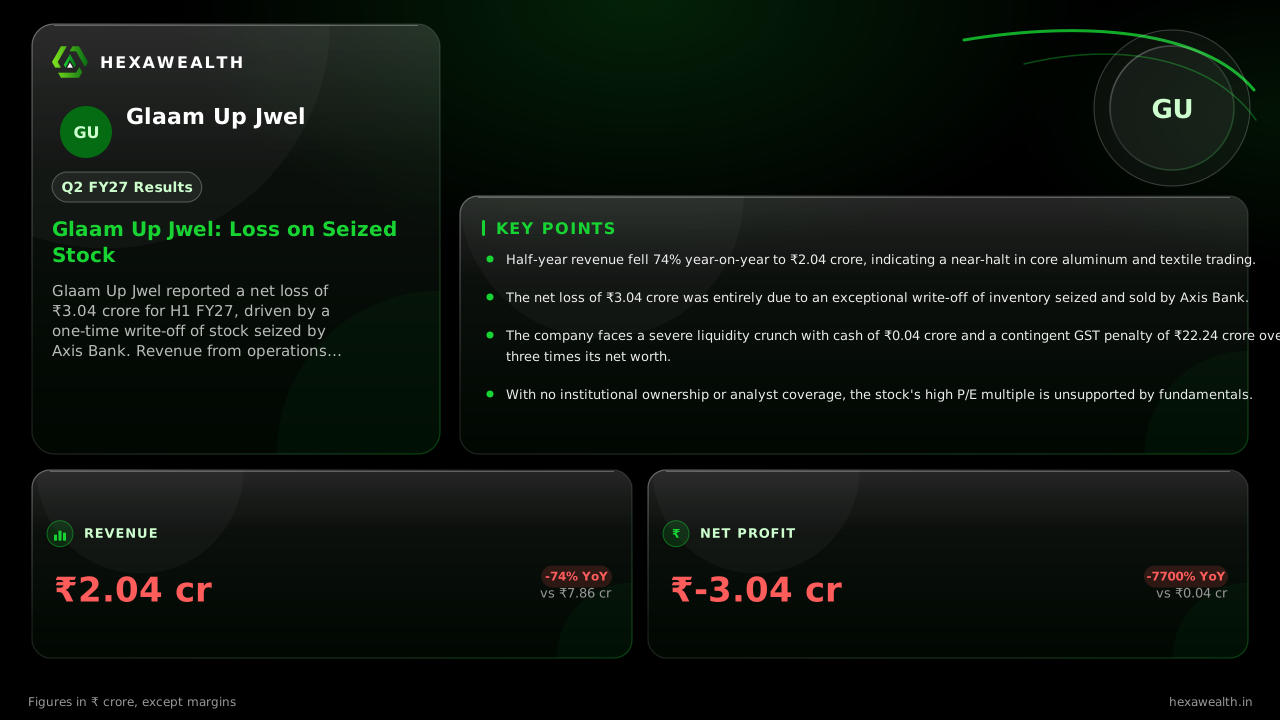
These overhangs create existential risk, compounded by a disastrous start to FY27. The same source notes a H1 FY27 net loss of ₹3.04 crore after writing off stock seized by a bank, eroding a third of the equity base from March. Revenue for that half fell 74% year-on-year, confirming the trading stall is worsening.
Live Chart
· GLAAMUP
(BSE)
ISIN: INE03CM01014
Key Points
- Quarterly revenue fell 63% year-on-year, reflecting a near-halt in core trading of aluminum and textiles amid tough market conditions.
- A net profit margin of 1.8% emerged from drastic cost-cutting, not sustainable business improvement.
- A contingent GST penalty of ₹22.24 crore and a bank default pose severe solvency risks, magnified by a loss-making start to FY27.
- The company has amended its charter to enter gems and jewellery, but this diversification remains a plan against a backdrop of severe financial stress.
Hexa Perspective
The quarter is a footnote to a larger crisis. The slight profitability is a statistical artifact of a shrinking cost base against a collapsing top line. The real story is the weight of contingent liabilities that dwarf the equity.
For the trading business to recover, global scrap availability and pricing must turn favorable—a factor entirely outside management's control. The planned diversification into gems is a long-term hope, but the immediate concern is liquidity and the potential crystallisation of the massive tax penalty. Investors are weighing a business with negligible current earnings against risks that threaten its going concern status.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.