Earthstahl (EARTH) Q2 FY27's Revenue Drops 36% as It Runs on One Furnace
Earthstahl & Alloys' Q2 FY27 revenue fell sharply to ₹21.69 crore, but its net loss improved sequentially as the company operated with just one furnace.
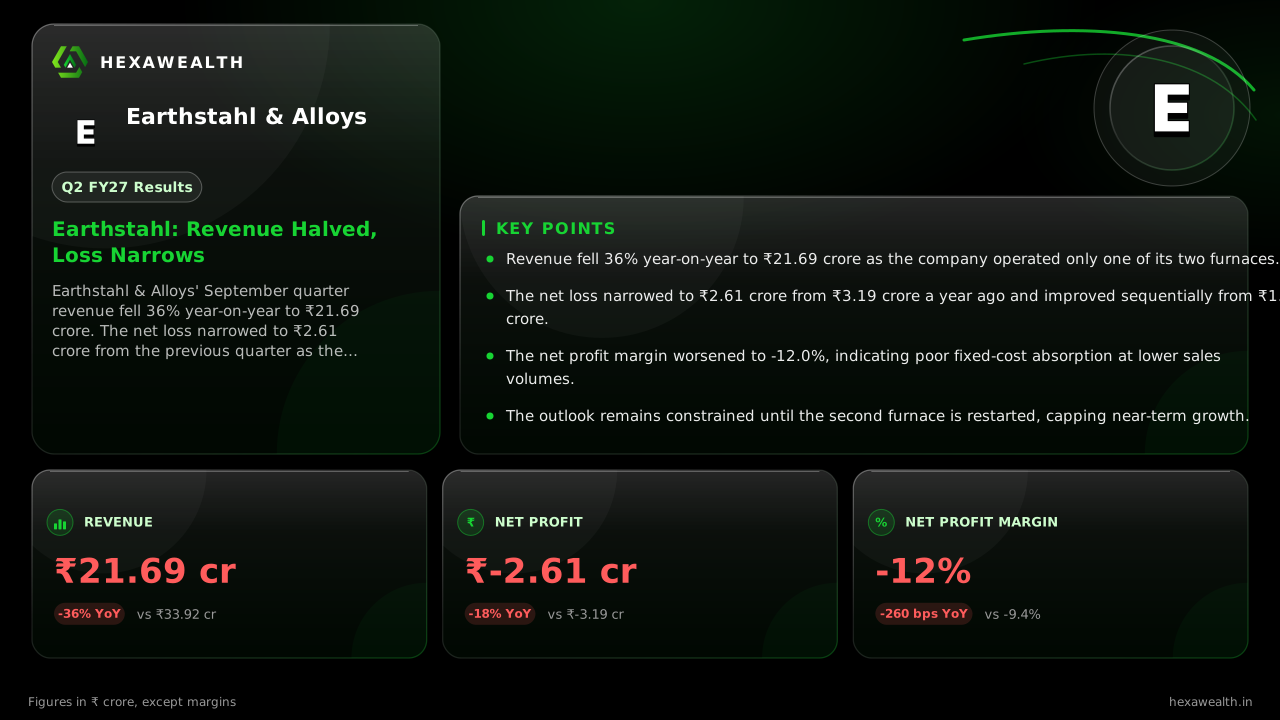
Earthstahl & Alloys' September quarter revenue fell 36% year-on-year to ₹21.69 crore. The net loss narrowed to ₹2.61 crore from the previous quarter as the company continues to operate only one of its two furnaces.
For a company that runs on two submerged arc furnaces, operating just one defines the quarter. Earthstahl & Alloys' September results show a business running at half its intended capacity, with revenue down sharply but losses improving from the prior quarter.
The numbers tell a story of constrained operations. Revenue fell 36% year-on-year to ₹21.69 crore, while the net loss narrowed to ₹2.61 crore from ₹3.19 crore a year ago. Sequentially, the loss improved from ₹1.71 crore even as revenue dropped 22%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 36.68
- Revenue (₹ Cr), Q4 FY25: 35.60
- Revenue (₹ Cr), Q2 FY26: 33.92
- Revenue (₹ Cr), Q4 FY26: 27.67
- Revenue (₹ Cr), Q2 FY27: 21.69
- Profit (₹ Cr), Q2 FY25: 0.68
- Profit (₹ Cr), Q4 FY25: -0.14
- Profit (₹ Cr), Q2 FY26: -3.19
- Profit (₹ Cr), Q4 FY26: -1.71
- Profit (₹ Cr), Q2 FY27: -2.61
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 36.68
- Revenue (₹ Cr), Q4 FY25: 35.60
- Revenue (₹ Cr), Q2 FY26: 33.92
- Revenue (₹ Cr), Q4 FY26: 27.67
- Revenue (₹ Cr), Q2 FY27: 21.69
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.68
- Profit (₹ Cr), Q4 FY25: -0.14
- Profit (₹ Cr), Q2 FY26: -3.19
- Profit (₹ Cr), Q4 FY26: -1.71
- Profit (₹ Cr), Q2 FY27: -2.61
Net Profit Margin
- Net Profit Margin, Q2 FY25: 1.9%
- Net Profit Margin, Q4 FY25: -0.4%
- Net Profit Margin, Q2 FY26: -9.4%
- Net Profit Margin, Q4 FY26: -6.2%
- Net Profit Margin, Q2 FY27: -12.0%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 21.69YoY -36% | 33.92 |
| Profit (₹ Cr) | -2.61YoY +18% | -3.19 |
| Net Profit Margin | -12.0%YoY -28% | -9.4% |
Why the top line collapsed
The 36% revenue drop stems directly from running one furnace instead of two. MarketPing reports the company has kept one furnace idle since November 2025 due to adverse market conditions. This halving of production capacity makes year-on-year comparisons difficult but explains the steep sales decline.
Costs fell in line with lower production, with total expenses down 34% year-on-year. However, the net profit margin worsened to -12%, deeper than the -9.4% margin a year ago. This suggests fixed costs are not being fully absorbed at the lower revenue run-rate.
The path forward is capacity-dependent
The near-term outlook remains tied to that second furnace. With no current guidance on restarting it, the company's revenue run-rate is likely to stay depressed. A report from mcapital.in estimates full-year revenue could be 22-32% below the FY26 baseline of ₹61.56 crore.
Live Chart
· EARTH
(BSE)
ISIN: INE0O4V01010
There is a structural demand story for ductile iron products, driven by government water programs. Indexbox research notes India's ductile and grey iron casting market could grow 5-7% annually through 2035. But Earthstahl cannot participate fully while operating at half-strength.
Key Points
- Revenue fell 36% year-on-year to ₹21.69 crore as the company operated only one of its two furnaces.
- The net loss narrowed to ₹2.61 crore from ₹3.19 crore a year ago and improved sequentially from ₹1.71 crore.
- The net profit margin worsened to -12.0%, indicating poor fixed-cost absorption at lower sales volumes.
- The outlook remains constrained until the second furnace is restarted, capping near-term growth.
Hexa Perspective
Earthstahl's quarter is a story of operational limbo. The business is generating just enough from one furnace to narrow its losses sequentially, but not enough to turn profitable or absorb fixed costs efficiently. The margin deterioration to -12% shows the strain.
The investment case now hinges on a single event: restarting the idle furnace. Until that happens, the company remains a spectator in a growing market. Investors are left weighing the cost of waiting against the potential for a sharp recovery if both furnaces eventually run.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.