Tuticorin Alkali (TUTIALKA) Q2 FY27 Profit Dives 57% as Costs Swallow Sales Jump
Revenue surged 42% year-on-year, but a near-doubling of raw material costs and a tripling of interest expense led to a steep 57% drop in net profit.
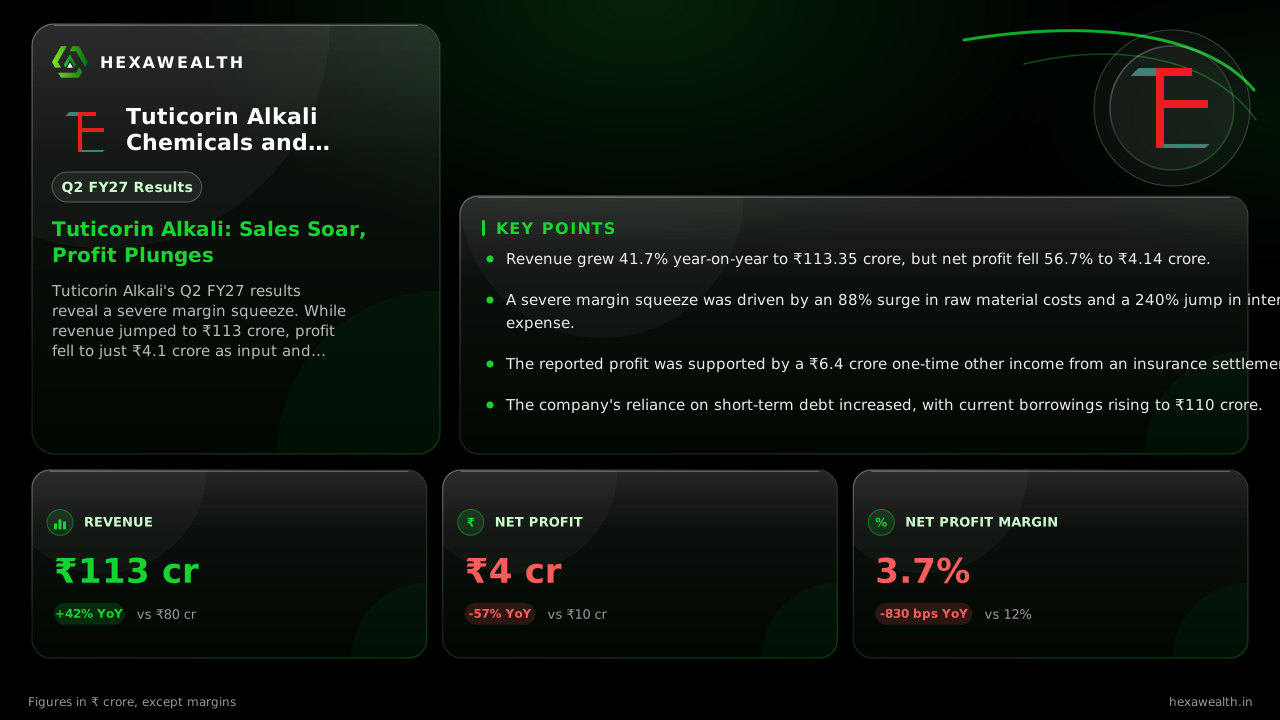
Tuticorin Alkali's Q2 FY27 results reveal a severe margin squeeze. While revenue jumped to ₹113 crore, profit fell to just ₹4.1 crore as input and finance costs soared, eroding profitability.
For a soda ash and ammonium chloride maker, a strong top line is only as good as the margins it can defend. Tuticorin Alkali Chemicals posted a 42% yearly sales jump in the September quarter, but its profit collapsed by more than half. The story is a textbook margin squeeze, where costs grew nearly twice as fast as revenue.
The numbers lay it bare. Revenue climbed to ₹113.35 crore, a sharp 40% sequential rise from the June quarter. Yet, net profit fell to ₹4.14 crore, down 57% from a year ago and 39% from last quarter. The net profit margin compressed to just 3.7%, a drop of 830 basis points year-on-year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 113.35YoY +42% | 80.71 | 79.99 |
| Profit (₹ Cr) | 4.14YoY -57% | 6.73 | 9.56 |
| PAT Margin (%) | 3.7YoY -69% | 8.3 | 12.0 |
Why the top-line win never reached the bottom line
A report by ScanX Trade points to two primary culprits. The cost of materials consumed nearly doubled year-on-year, surging 88% and far outpacing the 42% revenue growth. This was likely driven by volatile ammonia prices, which the company noted in its disclosures. Simultaneously, finance costs tripled to ₹4.92 crore.
This interest surge reflects a heavier debt load. ScanX Trade notes current borrowings rose to ₹110 crore in September from ₹70 crore in March, funding operations or working capital. The result was a core business that, according to Flash Finance, actually posted a pre-tax loss of ₹0.8 crore.
The one-off that kept profit in the black
The reported profit of ₹4.14 crore was only possible because of a large, non-recurring gain. Other income soared to ₹6.4 crore, up 540% from last year. ScanX Trade attributes this largely to insurance claim settlements for flood losses from December 2023. Without this, the quarter's profit would have been deeply negative.
A sector-wide headwind for pricing
The pain isn't unique to Tuticorin Alkali. Analysis from sector peer GHCL, cited by StoxBox, describes a global soda ash market facing oversupply and weak realizations. Indian demand growth slowed to just over 1% in the first half of FY27, pressured by geopolitical issues and delayed solar glass projects. This environment limits pricing power just as input costs spike.
Key Points
- Revenue grew 41.7% year-on-year to ₹113.35 crore, but net profit fell 56.7% to ₹4.14 crore.
- A severe margin squeeze was driven by an 88% surge in raw material costs and a 240% jump in interest expense.
- The reported profit was supported by a ₹6.4 crore one-time other income from an insurance settlement.
- The company's reliance on short-term debt increased, with current borrowings rising to ₹110 crore.
Hexa Perspective
This quarter underscores a fragile operating model where profitability is hostage to volatile input costs and a rising interest burden. The core business eroded to a loss, masked only by a one-off insurance gain. With the soda ash sector facing global oversupply and soft pricing, a near-term recovery in margins appears challenging. Investors are weighing whether the company's planned capacity expansion, noted in earlier reports, can be funded and executed profitably in this environment. The path forward requires either a sustained drop in input prices or a significant improvement in operational efficiency to rebuild profitability from today's thin base.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.