TPI India (TPINDIA) Q2 FY27 Profit Doubles on Strong Sales, But Costs Bite
TPI India's Q2 profit soared 109% on a 22% revenue jump, but a sharp rise in material costs pressured margins and a weak balance sheet remains a drag.
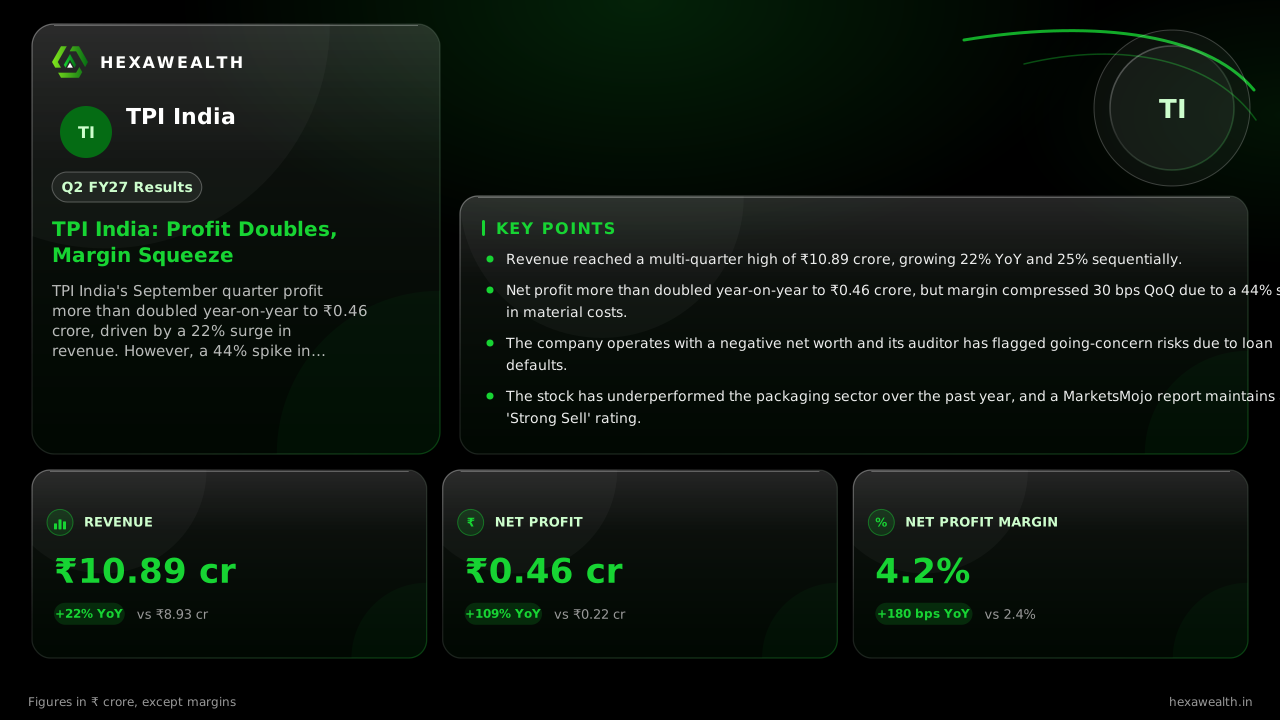
TPI India's September quarter profit more than doubled year-on-year to ₹0.46 crore, driven by a 22% surge in revenue. However, a 44% spike in material costs squeezed margins sequentially, and the company continues to operate with a negative net worth.
For TPI India, a polymer packaging maker with a history of losses, the September quarter brought a clear operational win: revenue hit a multi-quarter high and profit more than doubled. Yet, the numbers also show the business is still running against a structural headwind, as every rupee of new sales came with a heavier cost burden that kept full rewards from reaching the bottom line.
The company posted revenue of ₹10.89 crore, up 22% from a year ago and 25% from the June quarter. Net profit jumped 109% year-on-year to ₹0.46 crore, though the sequential gain was a more modest 18%. The profit margin improved sharply from last year's depressed base but slipped 30 basis points from the prior quarter.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Sep '25 (Q2 FY26): 8.93
- Revenue (₹ Cr), Dec '25 (Q3 FY26): 8.39
- Revenue (₹ Cr), Mar '26 (Q4 FY26): 9.85
- Revenue (₹ Cr), Jun '26 (Q1 FY27): 8.71
- Revenue (₹ Cr), Sep '26 (Q2 FY27): 10.89
- Net Profit (₹ Cr), Sep '25 (Q2 FY26): 0.22
- Net Profit (₹ Cr), Dec '25 (Q3 FY26): 0.52
- Net Profit (₹ Cr), Mar '26 (Q4 FY26): 1.87
- Net Profit (₹ Cr), Jun '26 (Q1 FY27): 0.39
- Net Profit (₹ Cr), Sep '26 (Q2 FY27): 0.46
Revenue (₹ Cr)
- Revenue (₹ Cr), Sep '25 (Q2 FY26): 8.93
- Revenue (₹ Cr), Dec '25 (Q3 FY26): 8.39
- Revenue (₹ Cr), Mar '26 (Q4 FY26): 9.85
- Revenue (₹ Cr), Jun '26 (Q1 FY27): 8.71
- Revenue (₹ Cr), Sep '26 (Q2 FY27): 10.89
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Sep '25 (Q2 FY26): 0.22
- Net Profit (₹ Cr), Dec '25 (Q3 FY26): 0.52
- Net Profit (₹ Cr), Mar '26 (Q4 FY26): 1.87
- Net Profit (₹ Cr), Jun '26 (Q1 FY27): 0.39
- Net Profit (₹ Cr), Sep '26 (Q2 FY27): 0.46
| Metric | CurrentSep '26 (Q2 FY27) | PreviousJun '26 (Q1 FY27) |
|---|---|---|
| Revenue (₹ Cr) | 10.89 | 8.71 |
| Net Profit (₹ Cr) | 0.46 | 0.39 |
| PAT Margin | 4.2% | 4.5% |
Why the profit jump didn't lift margins
The year-on-year profit surge was driven by core operations, not one-off income. A MarketsMojo report notes the company's operating margin, excluding other income, held above last year's level. However, the cost of materials surged 44% year-on-year to ₹9.11 crore, according to a MarketPing analysis. This rise, outpacing revenue growth, is why the net profit margin contracted from the previous quarter even as sales climbed.
A balance sheet that overshadows growth
Operational momentum is colliding with a fragile financial foundation. The auditor's review report, cited by MarketPing, highlights a going-concern assumption despite loan defaults and a completely eroded net worth. Shareholder funds stood at negative ₹11.7 crore as of March 2026. While interest costs have fallen, the interest cover is a thin 1.3 times, and the current ratio is a precarious 0.45.
The market's reaction was muted, with the stock closing at ₹13.70 on results day. This aligns with a MarketsMojo report that maintains a 'Strong Sell' rating, citing the negative book value and accumulated losses exceeding ₹16 crore. The structural weaknesses appear to cap investor enthusiasm despite the improving profit trend.
Live Chart
· TPINDIA
(BSE)
ISIN: INE578C01021
Key Points
- Revenue reached a multi-quarter high of ₹10.89 crore, growing 22% YoY and 25% sequentially.
- Net profit more than doubled year-on-year to ₹0.46 crore, but margin compressed 30 bps QoQ due to a 44% surge in material costs.
- The company operates with a negative net worth and its auditor has flagged going-concern risks due to loan defaults.
- The stock has underperformed the packaging sector over the past year, and a MarketsMojo report maintains a 'Strong Sell' rating.
Hexa Perspective
The quarter tells a story of two speeds. The operating business is finding demand, lifting sales and profit off a low base. Yet, the financial structure—negative equity, tight liquidity, and high raw material costs—acts as a governor on performance. For the recovery to be sustainable, TPI India needs to demonstrate it can consistently pass on cost inflation and, more critically, repair its balance sheet. Until then, the operational gains remain vulnerable to the next squeeze in input prices or a tightening in creditor terms.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.