TIL Q2 FY27 Revenue Triples on Acquisition, But Losses Persist
TIL's Q2 revenue surged 147% after consolidating its gas compressor unit, yet a heavy interest burden kept the company in the red.
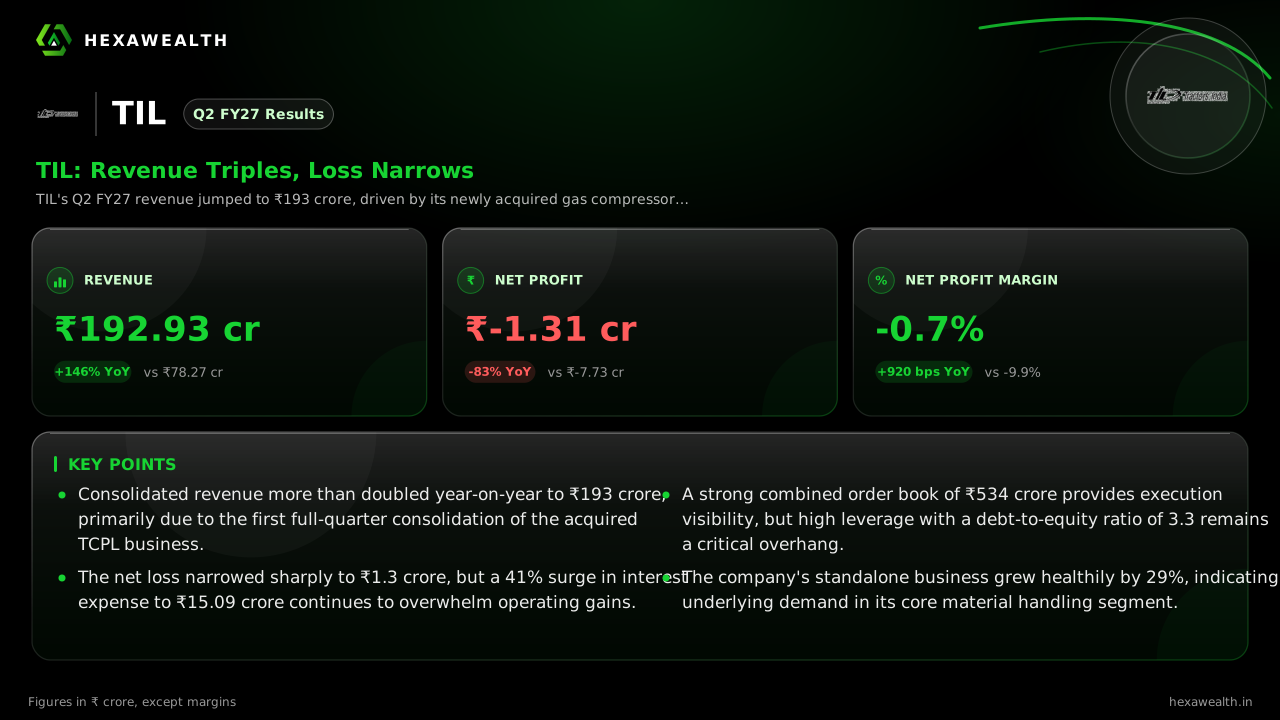
TIL's Q2 FY27 revenue jumped to ₹193 crore, driven by its newly acquired gas compressor business. While the net loss narrowed sharply, high interest costs continue to consume operational gains.
For TIL, a quarter defined by scale arrived through acquisition. The consolidation of Tulip Compression Private Limited (TCPL), bought in May, transformed the top line but left the old challenge of debt untouched.
The numbers show a business at two speeds. Consolidated revenue hit ₹192.9 crore, up 147% from a year ago. The net loss, however, was ₹1.3 crore. While that's an 83% improvement year-on-year, it marks the fifth consecutive quarter in the red.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 78.27
- Revenue (₹ Cr), Q3 FY26: 73.23
- Revenue (₹ Cr), Q4 FY26: 108.84
- Revenue (₹ Cr), Q1 FY27: 117.13
- Revenue (₹ Cr), Q2 FY27: 192.93
- Profit (₹ Cr), Q2 FY26: -7.73
- Profit (₹ Cr), Q3 FY26: -6.85
- Profit (₹ Cr), Q4 FY26: -9.97
- Profit (₹ Cr), Q1 FY27: -5.45
- Profit (₹ Cr), Q2 FY27: -1.31
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 78.27
- Revenue (₹ Cr), Q3 FY26: 73.23
- Revenue (₹ Cr), Q4 FY26: 108.84
- Revenue (₹ Cr), Q1 FY27: 117.13
- Revenue (₹ Cr), Q2 FY27: 192.93
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: -7.73
- Profit (₹ Cr), Q3 FY26: -6.85
- Profit (₹ Cr), Q4 FY26: -9.97
- Profit (₹ Cr), Q1 FY27: -5.45
- Profit (₹ Cr), Q2 FY27: -1.31
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 192.93YoY +146% | 117.13 | 78.27 |
| Profit (₹ Cr) | -1.31YoY +83% | -5.45 | -7.73 |
| Net Margin (%) | -0.7YoY +93% | -4.7 | -9.9 |
The Acquisition Engine
The headline growth is largely inorganic. According to Autocar Professional, TCPL contributed ₹92.3 crore, nearly half the quarter's revenue. The legacy material handling business grew a solid 29% to ₹100.7 crore, as reported by The Machine Maker. This dual-engine model delivered a beat against sparse expectations; StockWatch noted revenue came in well above a preview range of ₹130-150 crore.
The Crushing Cost of Capital
Operational improvements were erased by a soaring interest bill. Interest expense rose 41% year-on-year to ₹15.09 crore, its highest quarterly level. MarketsMojo highlighted that this cost exceeded the quarter's operating profit, leaving an interest cover ratio of just 0.84 times. The debt-to-equity ratio stands at 3.3, a burden that will not ease quickly.
Visibility Versus Viability
The path forward relies on executing a robust order book. Construction World reported TIL and TCPL have a combined order book of ₹534 crore, providing clear near-term visibility. Management, cited by StockWatch, aims for 15-16% EBITDA margins in the long term, up from about 6.5% now. Achieving this requires converting orders to cash profitably while managing the debt stack.
Live Chart
· TIL
(BSE)
ISIN: INE806C01018
Key Points
- Consolidated revenue more than doubled year-on-year to ₹193 crore, primarily due to the first full-quarter consolidation of the acquired TCPL business.
- The net loss narrowed sharply to ₹1.3 crore, but a 41% surge in interest expense to ₹15.09 crore continues to overwhelm operating gains.
- A strong combined order book of ₹534 crore provides execution visibility, but high leverage with a debt-to-equity ratio of 3.3 remains a critical overhang.
- The company's standalone business grew healthily by 29%, indicating underlying demand in its core material handling segment.
Hexa Perspective
This quarter confirms TIL's strategy to grow through acquisition, instantly scaling revenue. The catch is that it also scaled the balance sheet, locking the company into a high-interest cycle that consumes margin improvement. The story for the next few quarters is whether operational execution on a ₹534 crore order book can generate enough cash to start chipping away at that debt. Until interest coverage moves sustainably above 1, the journey to net profit remains precarious, regardless of top-line strength.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.