Tamilnadu Steel Tubes (TNSTLTU) Q2 FY27 Profit Plunges 80% Despite 48% Revenue Surge
The steel tube maker's Q2 FY27 sales hit a record high, but surging raw material and interest costs erased nearly all profitability, raising questions about its business model.
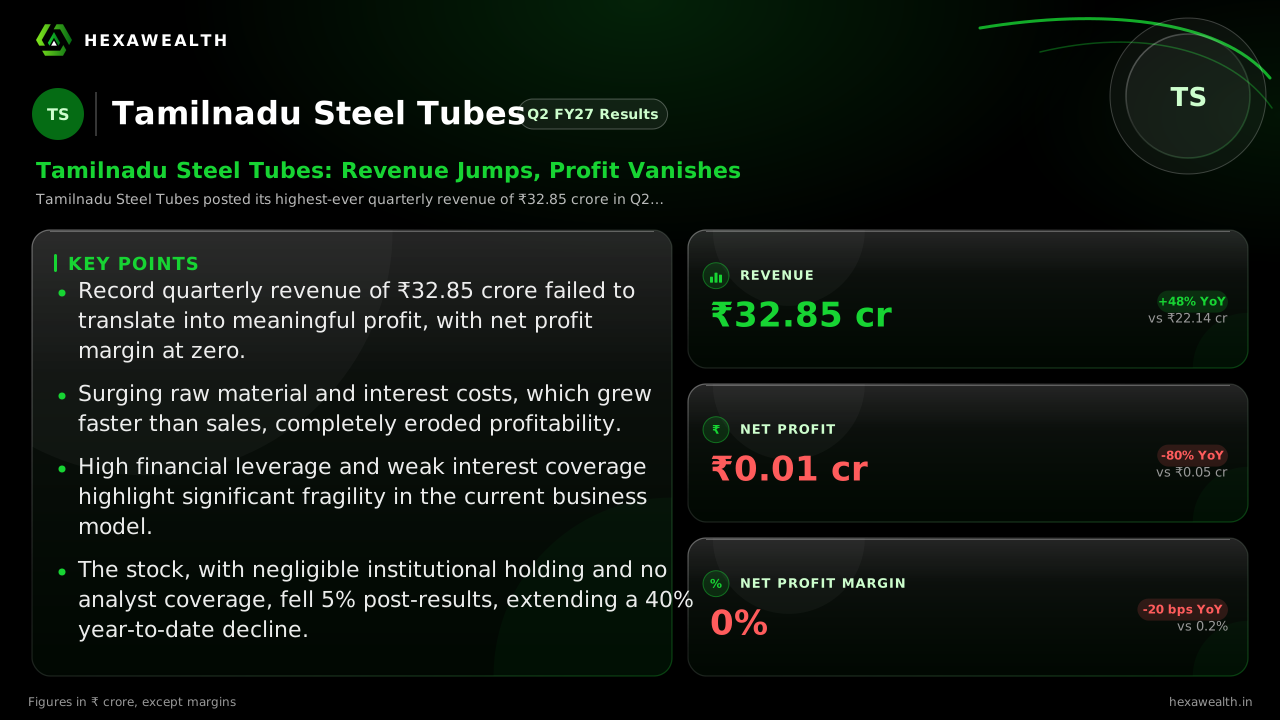
Tamilnadu Steel Tubes posted its highest-ever quarterly revenue of ₹32.85 crore in Q2 FY27, up 48% year-on-year. Yet, net profit collapsed to just ₹0.01 crore, down 80%, as costs outpaced sales growth.
For a small-scale steel tube manufacturer, a record sales quarter should signal a path to stronger earnings. Tamilnadu Steel Tubes' Q2 FY27 tells a different story, where booming volumes met a wall of costs that left the bottom line nearly erased.
The company's revenue surged 48.4% year-on-year to ₹32.85 crore, its highest in recent history. Sequentially, sales jumped 53.8% from a weak Q1. Yet, net profit collapsed 80% YoY to just ₹0.01 crore, with the net profit margin vanishing to 0.0%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Sep 2025 (Q2 FY26): 22.14
- Revenue (₹ Cr), Dec 2025 (Q3 FY26): 18.96
- Revenue (₹ Cr), Mar 2026 (Q4 FY26): 25.67
- Revenue (₹ Cr), Jun 2026 (Q1 FY27): 21.36
- Revenue (₹ Cr), Sep 2026 (Q2 FY27): 32.85
- Net Profit (₹ Cr), Sep 2025 (Q2 FY26): 0.05
- Net Profit (₹ Cr), Dec 2025 (Q3 FY26): -0.00
- Net Profit (₹ Cr), Mar 2026 (Q4 FY26): -0.04
- Net Profit (₹ Cr), Jun 2026 (Q1 FY27): 0.02
- Net Profit (₹ Cr), Sep 2026 (Q2 FY27): 0.01
Revenue (₹ Cr)
- Revenue (₹ Cr), Sep 2025 (Q2 FY26): 22.14
- Revenue (₹ Cr), Dec 2025 (Q3 FY26): 18.96
- Revenue (₹ Cr), Mar 2026 (Q4 FY26): 25.67
- Revenue (₹ Cr), Jun 2026 (Q1 FY27): 21.36
- Revenue (₹ Cr), Sep 2026 (Q2 FY27): 32.85
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Sep 2025 (Q2 FY26): 0.05
- Net Profit (₹ Cr), Dec 2025 (Q3 FY26): -0.00
- Net Profit (₹ Cr), Mar 2026 (Q4 FY26): -0.04
- Net Profit (₹ Cr), Jun 2026 (Q1 FY27): 0.02
- Net Profit (₹ Cr), Sep 2026 (Q2 FY27): 0.01
Net Profit Margin (%)
- Net Profit Margin (%), Sep 2025 (Q2 FY26): 0.2
- Net Profit Margin (%), Dec 2025 (Q3 FY26): -0.0
- Net Profit Margin (%), Mar 2026 (Q4 FY26): -0.1
- Net Profit Margin (%), Jun 2026 (Q1 FY27): 0.1
- Net Profit Margin (%), Sep 2026 (Q2 FY27): 0.0
| Metric | CurrentSep 2026 (Q2 FY27) | PreviousJun 2026 (Q1 FY27) |
|---|---|---|
| Revenue (₹ Cr) | 32.85 | 21.36 |
| Net Profit (₹ Cr) | 0.01 | 0.02 |
| Net Profit Margin (%) | 0.0 | 0.1 |
Why the growth didn't pay
The stark disconnect stems from costs rising faster than sales. According to analysis by MarketPing, raw material costs consumed over 92% of sales. Total expenses grew 49.4% YoY, outpacing the 48.4% revenue increase.
Finance costs surged 83.5% year-on-year to ₹0.31 crore. This was driven by higher working capital needs, with the company raising its overdraft limit by ₹3 crore in October, as noted in an mcapital.in report. Depreciation also rose sharply, suggesting recent capital expenditure that has yet to improve efficiency.
A fragile financial position
This margin squeeze occurs against a backdrop of high leverage. The company's debt-to-equity ratio stood at 1.44, and MarketsMojo analysis indicates an EBIT-to-interest coverage of just 0.27 times. Operating profit barely covers interest obligations, leaving no room for error if costs rise further.
Live Chart
· TNSTLTU
(BSE)
ISIN: INE176E01012
MarketsMojo also reports a lack of institutional investor interest, with holdings at just 1.38%. The shareholder base is overwhelmingly retail, and the stock has no active analyst coverage or price targets, reflecting its peripheral status.
Key Points
- Record quarterly revenue of ₹32.85 crore failed to translate into meaningful profit, with net profit margin at zero.
- Surging raw material and interest costs, which grew faster than sales, completely eroded profitability.
- High financial leverage and weak interest coverage highlight significant fragility in the current business model.
- The stock, with negligible institutional holding and no analyst coverage, fell 5% post-results, extending a 40% year-to-date decline.
Hexa Perspective
The quarter exposes a fundamental challenge: Tamilnadu Steel Tubes lacks pricing power or operational scale to protect margins in a competitive, input-cost-sensitive market. Growing sales on borrowed money, while costs consume over 92% of revenue, is not a sustainable model.
The path forward hinges on whether recent capital expenditure can drive meaningful efficiency gains or if the company can renegotiate input costs. With leverage high and margins razor-thin, any adverse movement in steel prices or demand could quickly push results back into the red. Investors are rightly questioning if top-line growth alone can ever repair this bottom line.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.