Tirupati Starch (TIRUSTA) Q2 FY27 Swings to a ₹6 Crore Loss as Margins Collapse
The starch maker reported its lowest quarterly revenue in two years and a sharp operating loss, raising concerns over its financial sustainability amid high debt.
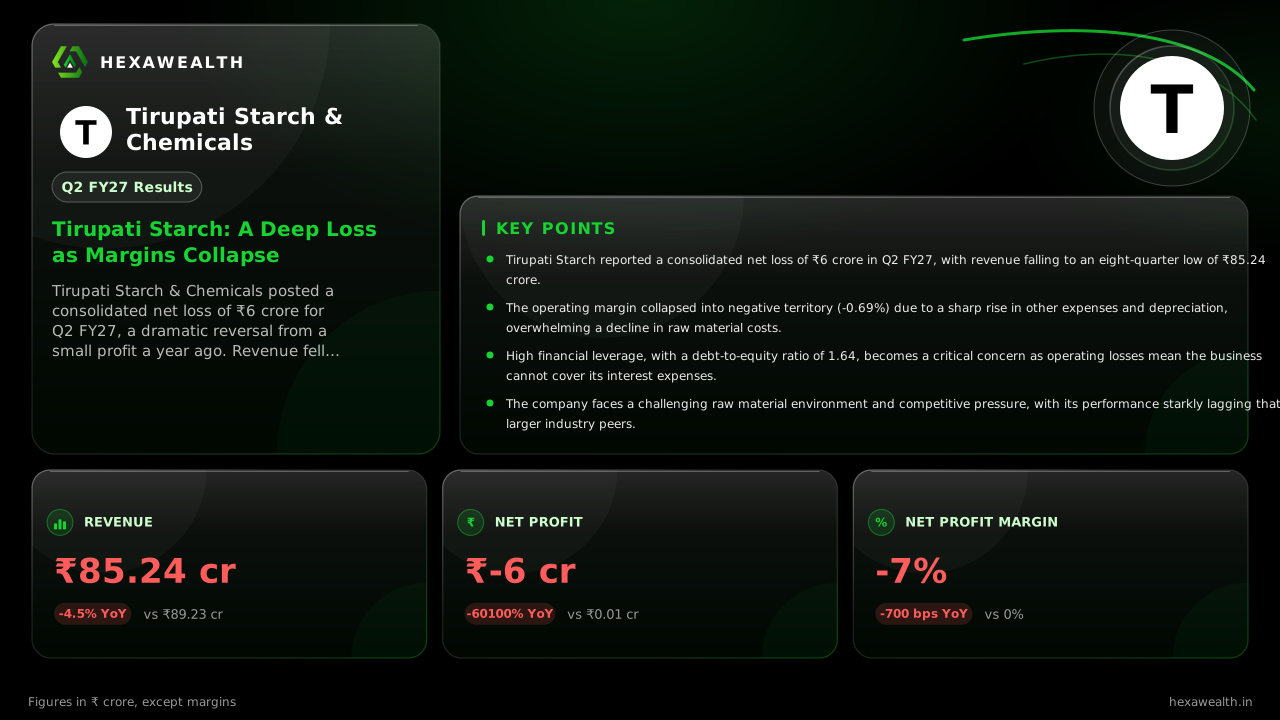
Tirupati Starch & Chemicals posted a consolidated net loss of ₹6 crore for Q2 FY27, a dramatic reversal from a small profit a year ago. Revenue fell 4.5% YoY to ₹85.24 crore, while a surge in costs pushed the company into an operating loss.
For Tirupati Starch & Chemicals, the September quarter was a severe breakdown. The company swung from a near-break-even position a year ago to a consolidated net loss of ₹6 crore, as its core operations began losing money for the first time in recent memory.
The numbers show a business under acute pressure. Revenue of ₹85.24 crore was down 4.5% from last year and 7% from the previous quarter, marking the lowest sales in the last eight quarters. The real damage was below the top line, where the net profit margin plunged 780 basis points sequentially to -7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 89.23
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 91.94
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 89.86
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 91.63
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 85.24
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.01
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 2.46
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 2.44
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.78
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 89.23
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 91.94
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 89.86
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 91.63
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 85.24
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.01
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 2.46
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 2.44
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.78
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -6.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 0.0
- Net Profit Margin (%), Q3 FY26 (Dec 2025): 2.7
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 2.7
- Net Profit Margin (%), Q1 FY27 (Jun 2026): 0.8
- Net Profit Margin (%), Q2 FY27 (Sep 2026): -7.0
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 85.24 | 91.63 |
| Profit (₹ Cr) | -6.0 | 0.78 |
| Net Profit Margin (%) | -7.0 | 0.8 |
Why the bottom fell out
The loss was driven by a collapse in operating profitability. According to MarketsMojo, the operating margin swung from a positive 5.72% in Q1 to a negative 0.69% in Q2. While raw material costs fell, other expenses surged 37.5% year-on-year to ₹20.90 crore. A 79% sequential jump in depreciation to ₹3.39 crore, which MarketsMojo links to recent capitalised expansion, added a heavy fixed cost just as sales weakened.
A debt burden with no cover
This operational failure creates a serious financial strain. With operating losses, the company cannot service its debt from core business cash flows. MarketsMojo notes the operating profit to interest coverage ratio plunged to negative 0.28 times. The debt-to-equity ratio stands at a high 1.64, and the stock has fallen nearly 35% over the past year.
The outlook in a tough market
The broader industry context offers little near-term relief. Reports point to a drought-induced maize crunch, pitting starch makers against ethanol and poultry producers for supply. While peer Sukhjit Starch reported strong growth, Tirupati's results signal it is losing pricing power and market share. The company is funding a ₹40 crore capacity expansion, but this new fixed cost arrives amid severe operational stress.
Live Chart
· TIRUSTA
(BSE)
ISIN: INE314D01011
Key Points
- Tirupati Starch reported a consolidated net loss of ₹6 crore in Q2 FY27, with revenue falling to an eight-quarter low of ₹85.24 crore.
- The operating margin collapsed into negative territory (-0.69%) due to a sharp rise in other expenses and depreciation, overwhelming a decline in raw material costs.
- High financial leverage, with a debt-to-equity ratio of 1.64, becomes a critical concern as operating losses mean the business cannot cover its interest expenses.
- The company faces a challenging raw material environment and competitive pressure, with its performance starkly lagging that of larger industry peers.
Hexa Perspective
This quarter reveals a company caught in a perfect storm. External pressures from input costs and competition are colliding with internal missteps—a significant expansion adding fixed costs precisely when sales are declining. The result is a broken operating model. The path back requires not just a recovery in sales but a fundamental improvement in cost control and pricing. With debt high and interest coverage now negative, the margin for error is gone. Investors are rightly questioning sustainability, as seen in the stock's steep decline over the past year.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.