Tega Industries (TEGA) Q2 FY27 Revenue Jumps 10x, But Costs Keep Profits in the Red
The mining consumables maker's transformational acquisition drove a tenfold revenue surge, but high interest and depreciation costs led to a second consecutive quarterly loss.
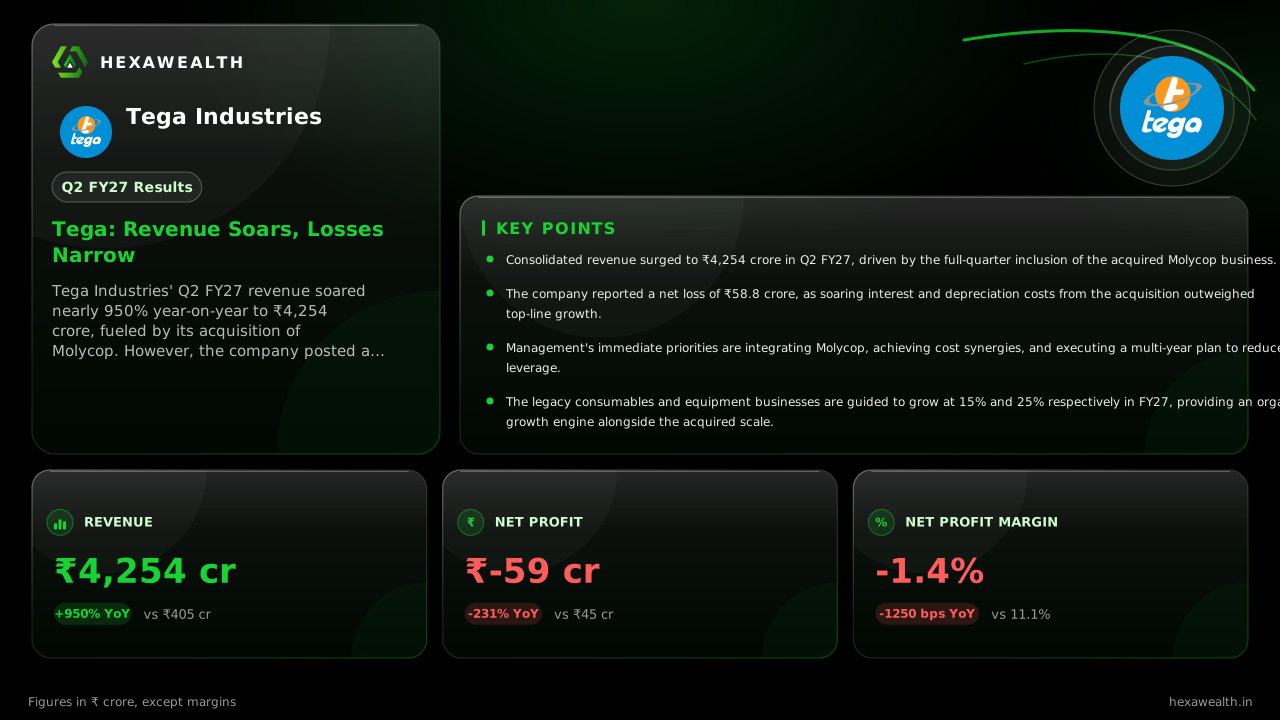
Tega Industries' Q2 FY27 revenue soared nearly 950% year-on-year to ₹4,254 crore, fueled by its acquisition of Molycop. However, the company posted a net loss of ₹58.8 crore as financing and depreciation costs from the deal overwhelmed the top-line growth.
For Tega Industries, the September quarter was the first full period showcasing its new scale after a transformational acquisition. The numbers tell a story of a company that has grown tenfold overnight, but is now grappling with the financial weight of that ambition.
Consolidated revenue leapt to ₹4,254 crore, up nearly 950% from a year ago. Sequentially, sales more than doubled from the June quarter. Yet, the bottom line remained deep red, with a net loss of ₹58.8 crore. While this is an improvement from the ₹108.3 crore loss in Q1, it marks a stark reversal from the ₹44.9 crore profit earned in the same quarter last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 4,254.03YoY +949% | 1,723.44 | 405.35 |
| Profit (₹ Cr) | -58.77YoY -231% | -108.25 | 44.94 |
| Net Profit Margin (%) | -1.4YoY -113% | -6.3 | 11.1 |
The Molycop Effect
The sheer scale of the revenue jump is almost entirely due to the consolidation of Molycop Group, a global grinding media producer. Tega completed this $1.5 billion acquisition on June 1, 2026, as reported by Investywise. Molycop contributed roughly 75% of the group's revenue in the prior quarter, according to an Inve.money summary, fundamentally reshaping the company.
This acquisition, however, came with a heavy financial structure. Interest expense ballooned to ₹291.9 crore, up nearly 5,000% year-on-year, reflecting the significant debt taken on to fund the deal. Depreciation and amortisation also surged over 600% to ₹168.6 crore as the company began accounting for Molycop's vast asset base.
The Path to Profitability
Management's focus is now on integration and deleveraging. On the Q1 FY27 earnings call, the company committed to reducing debt to about 3 times leverage within three to four years. It also expects revenue synergies from cross-selling Tega and Molycop products to ramp up from the third quarter onwards.
The core consumables business, excluding Molycop, is expected to grow at a 15% CAGR, while the equipment segment is targeted for 25% growth this fiscal year. A new plant in Chile is slated for commissioning by March 2027, adding to future capacity. However, the near-term profitability picture remains clouded by the high fixed-cost burden of the acquisition.
Key Points
- Consolidated revenue surged to ₹4,254 crore in Q2 FY27, driven by the full-quarter inclusion of the acquired Molycop business.
- The company reported a net loss of ₹58.8 crore, as soaring interest and depreciation costs from the acquisition outweighed top-line growth.
- Management's immediate priorities are integrating Molycop, achieving cost synergies, and executing a multi-year plan to reduce leverage.
- The legacy consumables and equipment businesses are guided to grow at 15% and 25% respectively in FY27, providing an organic growth engine alongside the acquired scale.
Hexa Perspective
The quarter confirms Tega's successful leap into the global mining consumables big league, but the financials are now those of a heavily leveraged industrial. The reported losses are a direct cost of that ambition, not an operating failure. The next few quarters will be a test of integration—whether the promised synergies can start offsetting the enlarged interest and depreciation lines.
Investors are paying for future synergy and market leadership, not current earnings. The stock's premium valuation, at over 100% above the industry PE, reflects this forward-looking bet. The risk is that the timeline for deleveraging and margin recovery stretches longer than anticipated, keeping profitability subdued.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.