Kronox Lab Sciences (KRONOX) Q2 FY27 Revenue Doubles as Costs Pinch Profit
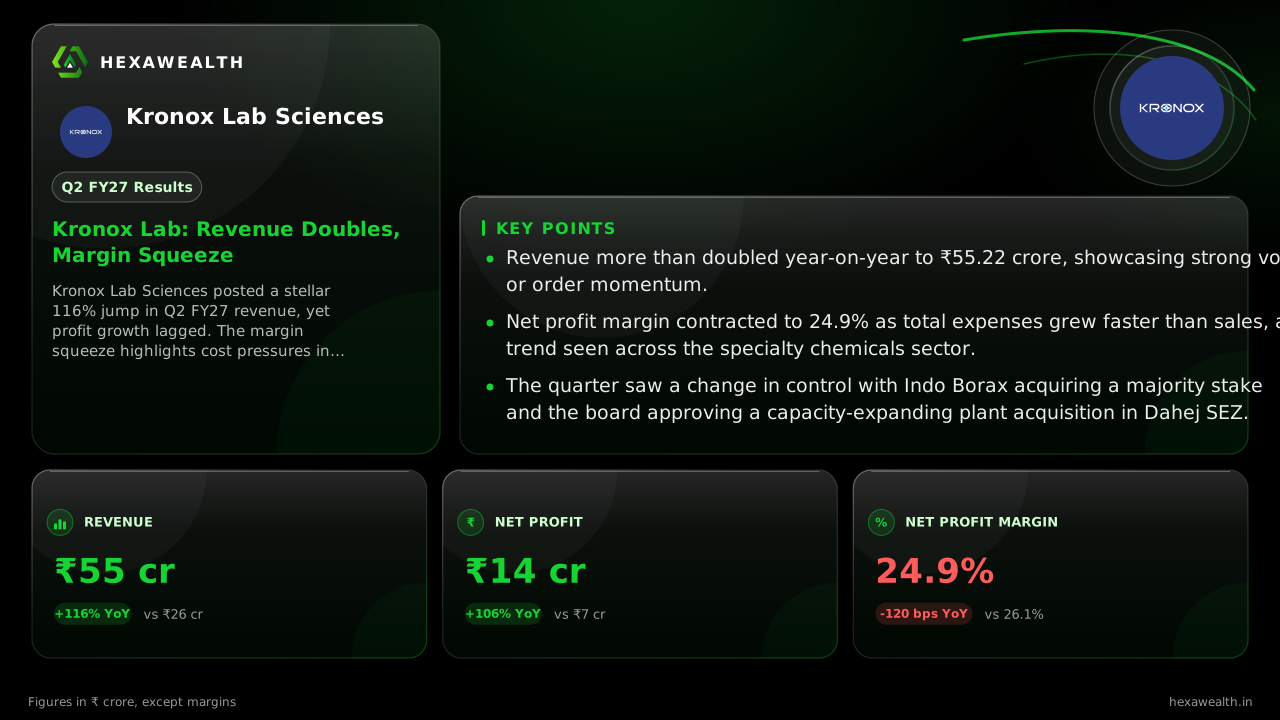
Revenue more than doubled year-on-year to ₹55 crore, but rising material and employee costs squeezed the net profit margin lower.
Kronox Lab Sciences posted a stellar 116% jump in Q2 FY27 revenue, yet profit growth lagged. The margin squeeze highlights cost pressures in the specialty chemicals sector amid a strategic ownership change.
For a specialty chemical maker, scaling up often means trading some profitability for volume. Kronox Lab Sciences delivered that exact dynamic in the September quarter, with revenue more than doubling from a year ago. The cost of that growth, however, was a noticeable compression in margins, as expenses rose even faster than the top line.
The numbers tell a story of powerful top-line expansion meeting stiff cost pressure. Revenue surged to ₹55.22 crore, up 116% from the same quarter last year and nearly doubling from the previous quarter. Profit followed, rising 106% year-on-year to ₹13.74 crore, but it grew slower than sales.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 55.22YoY +116% | 28.39 | 25.53 |
| Profit (₹ Cr) | 13.74YoY +106% | 7.30 | 6.68 |
| Net Profit Margin (%) | 24.9YoY -4.6% | 25.7 | 26.1 |
Why the profit didn't keep pace
The margin squeeze was broad-based. According to a report from ScanX, a sharp rise in the cost of materials consumed was the primary driver, alongside increases in employee and other expenses. This aligns with the payload data, which shows total expenses grew 123% year-on-year, outpacing revenue growth.
Interest costs, while small, also jumped significantly as the company likely funded its expansion. This cost inflation is a sector-wide theme, with Crisil Ratings noting margin pressure across specialty chemicals due to higher crude-linked input costs and subdued export realizations.
A quarter of strategic shifts
Beyond the P&L, this was a transformative period for Kronox. Indo Borax & Chemicals acquired a 64.26% controlling stake, becoming the new holding company in late September. This triggered an open offer and reduced the original promoters' stake, as noted in an analysis by StockFin.ai.
Concurrently, the board approved the acquisition of a 5,000 sq. metre plant in Dahej SEZ. Management, cited by News.AlfaFinder, aims to build a phased manufacturing pipeline targeting up to 18,000 MTPA capacity, signaling a clear intent to scale operations under new ownership.
The outlook amid sector headwinds
The near-term path balances ambitious growth against sector realities. While the Dahej acquisition adds capacity, integration and startup costs could pressure margins further in the coming quarters. The company's focus on high-purity chemicals for pharma and biotech provides a defensive end-market, but it is not immune to global feedstock volatility.
With promoter ownership now consolidated under a strategic buyer focused on chemical expansion, execution on the new capacity will be the critical swing factor. The market will watch for whether operational scaling can eventually restore the margin profile that has drifted below its trailing twelve-month average of 26.4%.
Key Points
- Revenue more than doubled year-on-year to ₹55.22 crore, showcasing strong volume or order momentum.
- Net profit margin contracted to 24.9% as total expenses grew faster than sales, a trend seen across the specialty chemicals sector.
- The quarter saw a change in control with Indo Borax acquiring a majority stake and the board approving a capacity-expanding plant acquisition in Dahej SEZ.
Hexa Perspective
This quarter captures Kronox at an inflection point: explosive revenue growth colliding with the cost realities of scaling a chemical business. The 120-basis-point year-on-year margin decline, while manageable, confirms that top-line leaps are not translating directly to the bottom line.
The strategic shift to a new, growth-oriented parent and the Dahej plant acquisition frame the next chapter. Success hinges on managing the margin squeeze during this capacity build-out. Investors are effectively betting that the new ownership can navigate these cost pressures and convert the expanded top line into more durable profitability over the medium term.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.