Sampann Utpadan (SAMPANN) Q2 FY27 Posts 40% Revenue Gain, Swings to Loss on Impairment
The reclaimed rubber business drove a sharp top-line increase, but a one-off asset write-down pushed the September quarter into the red.
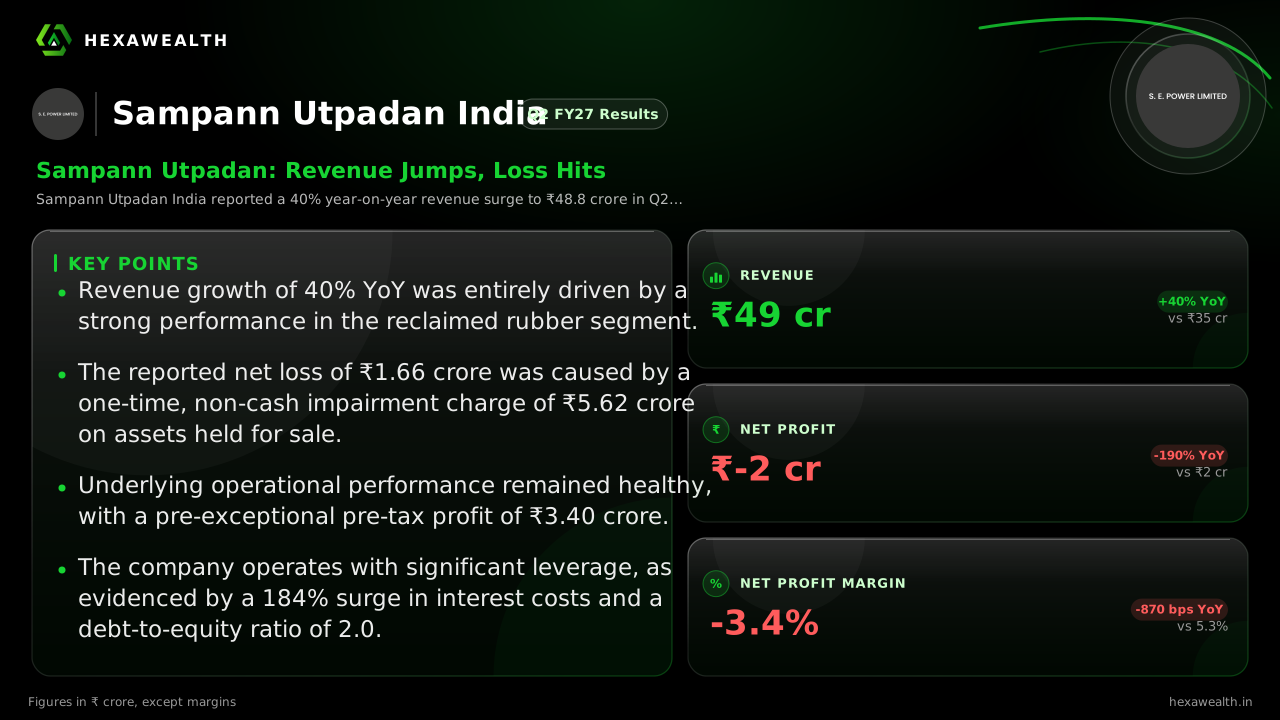
Sampann Utpadan India reported a 40% year-on-year revenue surge to ₹48.8 crore in Q2 FY27. However, a significant impairment charge led to a net loss of ₹1.66 crore, masking underlying operational strength in its core business.
For Sampann Utpadan, the September quarter was a story of two starkly different realities. Its core reclaimed rubber business delivered robust growth, yet the headline numbers told a tale of loss. The tension between a healthy operating engine and a one-time accounting charge defined the period.
The numbers show this split clearly. Revenue surged 40.1% year-on-year to ₹48.81 crore, continuing a strong sequential climb. Profit, however, swung to a loss of ₹1.66 crore from a profit of ₹1.85 crore a year ago. The net profit margin collapsed by 870 basis points to -3.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 48.81YoY +40% | 41.70 | 34.84 |
| Profit (₹ Cr) | -1.66YoY -190% | 2.05 | 1.85 |
| Net Profit Margin (%) | -3.4YoY -164% | 4.9 | 5.3 |
The Impairment That Masked Operations
The entire loss stemmed from a ₹5.62 crore impairment charge on assets held for sale, as reported by ScanX. This non-cash write-down, booked under 'other income', turned a pre-tax operating profit of ₹3.40 crore into a reported loss. Excluding this one-off, the underlying business momentum was positive.
The reclaimed rubber segment was the sole performer, contributing all ₹48.81 crore in revenue. ScanX notes its EBIT grew 44% year-on-year to ₹4.00 crore. The non-conventional energy segment, from which the company divested loss-making windmills last quarter, reported zero revenue and a small loss.
A Debt-Led Growth Model
Financing this growth came at a higher cost. Interest expense jumped 184% year-on-year to ₹0.84 crore, reflecting increased borrowing. Simply Wall St data shows a debt-to-equity ratio of 2.0, indicating a leveraged balance sheet. The company's cash position remained thin at ₹0.04 crore, with working capital absorbing funds as trade receivables grew alongside sales.
Management did not provide new formal guidance. The strategic focus remains squarely on the reclaimed rubber business, with the impairment charge effectively cleaning up the non-core asset portfolio. The broader rubber recycling sector outlook is supportive, with Multibagg.ai highlighting growing demand from automotive and infrastructure sectors.
Key Points
- Revenue growth of 40% YoY was entirely driven by a strong performance in the reclaimed rubber segment.
- The reported net loss of ₹1.66 crore was caused by a one-time, non-cash impairment charge of ₹5.62 crore on assets held for sale.
- Underlying operational performance remained healthy, with a pre-exceptional pre-tax profit of ₹3.40 crore.
- The company operates with significant leverage, as evidenced by a 184% surge in interest costs and a debt-to-equity ratio of 2.0.
Hexa Perspective
The quarter presents a clear case for looking past the headline loss. The impairment is a discrete, non-recurring accounting event tied to the company's ongoing strategic shift away from non-core energy assets. The core rubber business demonstrates it can deliver strong top-line growth and operating profit.
The sustainability of this model, however, hinges on managing the high financial leverage. The sharp rise in interest costs is a direct drag, and the thin cash buffer leaves little room for error. Investors are effectively betting on the reclaimed rubber segment's growth continuing to outpace its rising cost of capital.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.