Aspinwall (ASPINWALL) Q2 FY27 Revenue Jumps 163% as Profit Barely Budges
The diversified logistics and plantation firm saw a massive top-line surge in Q2 FY27, but a sharp rise in costs and interest expenses kept profit growth minimal.
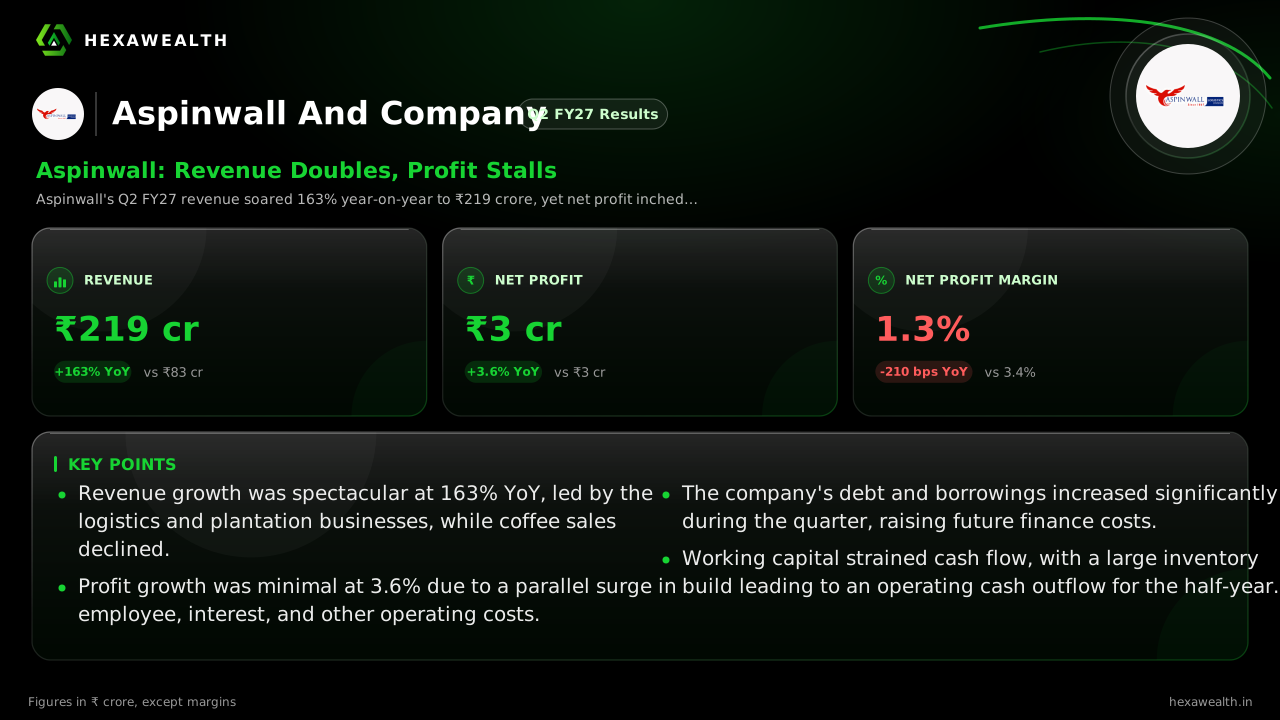
Aspinwall's Q2 FY27 revenue soared 163% year-on-year to ₹219 crore, yet net profit inched up just 3.6%. The quarter reveals a story of booming sales, led by logistics and plantations, but intense margin pressure from rising costs.
For Aspinwall, a company straddling logistics, coffee, and rubber, the September quarter is often its seasonal low. This year flipped that script with a top-line explosion, but the bottom line tells a more complicated story of costs racing ahead of sales.
Revenue more than doubled from a year ago to ₹218.9 crore, while net profit edged up to just ₹2.9 crore. The net profit margin collapsed by 210 basis points to 1.3%, showing how little of the sales surge reached shareholders.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 218.92 | 113.18 |
| Net Profit (₹ Cr) | 2.9 | -0.7 |
| Net Profit Margin (%) | 1.3 | -0.6 |
Where the growth came from
The revenue surge was not broad-based. According to Arthneeti.com, the logistics and plantation divisions drove it. Logistics revenue jumped about 50% year-on-year, while the plantation segment rose 54%. The coffee segment, however, contracted by 36%, highlighting the volatile commodity mix within the conglomerate.
The costs that ate the profit
A 163% rise in sales was met with a 153% rise in total expenses. Employee costs more than doubled, and interest expense also doubled year-on-year. This suggests the sales boom required significantly higher operational and financial leverage. The company also reported an operating cash outflow of ₹22.37 crore for the first half, which Multibagg.ai attributed to a ₹22.40 crore inventory build-up.
Borrowings increased sharply, from ₹75 crore at the end of March to nearly ₹107 crore by September. With finance costs already up, this debt load adds a persistent pressure on future margins unless the new capital fuels higher-margin growth.
A seasonal shift or a new trend?
The quarter marks a return to profit after a loss in Q1, but at a much weaker margin than historical September quarters. Management did not provide formal guidance, but the board approved the appointment of a new CEO alongside the results. No major new capital expenditure plans were identified in recent reports, per Multibagg.ai.
The outlook is clouded by commodity swings. The Economic Times reports India's coffee output is set to miss forecasts due to poor rains, which could pressure Aspinwall's processing business. Conversely, domestic rubber prices in Kerala have held firm despite global weakness.
Key Points
- Revenue growth was spectacular at 163% YoY, led by the logistics and plantation businesses, while coffee sales declined.
- Profit growth was minimal at 3.6% due to a parallel surge in employee, interest, and other operating costs.
- The company's debt and borrowings increased significantly during the quarter, raising future finance costs.
- Working capital strained cash flow, with a large inventory build leading to an operating cash outflow for the half-year.
Hexa Perspective
The quarter presents a clear dichotomy: explosive top-line growth constrained by severe margin compression. The revenue jump appears driven by specific segmental strength rather than a company-wide boom, and the cost structure has expanded in lockstep.
For this performance to sustain, Aspinwall needs the high-growth logistics and plantation segments to not only maintain volume but also improve pricing power. The rising interest burden from increased borrowings is a fixed cost that will weigh on profits until those new funds generate a superior return. Investors are left weighing a promising sales rebound against a profitability engine that is still sputtering.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.