Ceigall India (CEIGALL) Q2 FY27 Profit Jumps 64% as Margins Expand Sharply
Ceigall India's Q2 FY27 profit surged 64% YoY, driven by a sharp 240 bps margin expansion, even as revenue grew 27% on strong project execution.
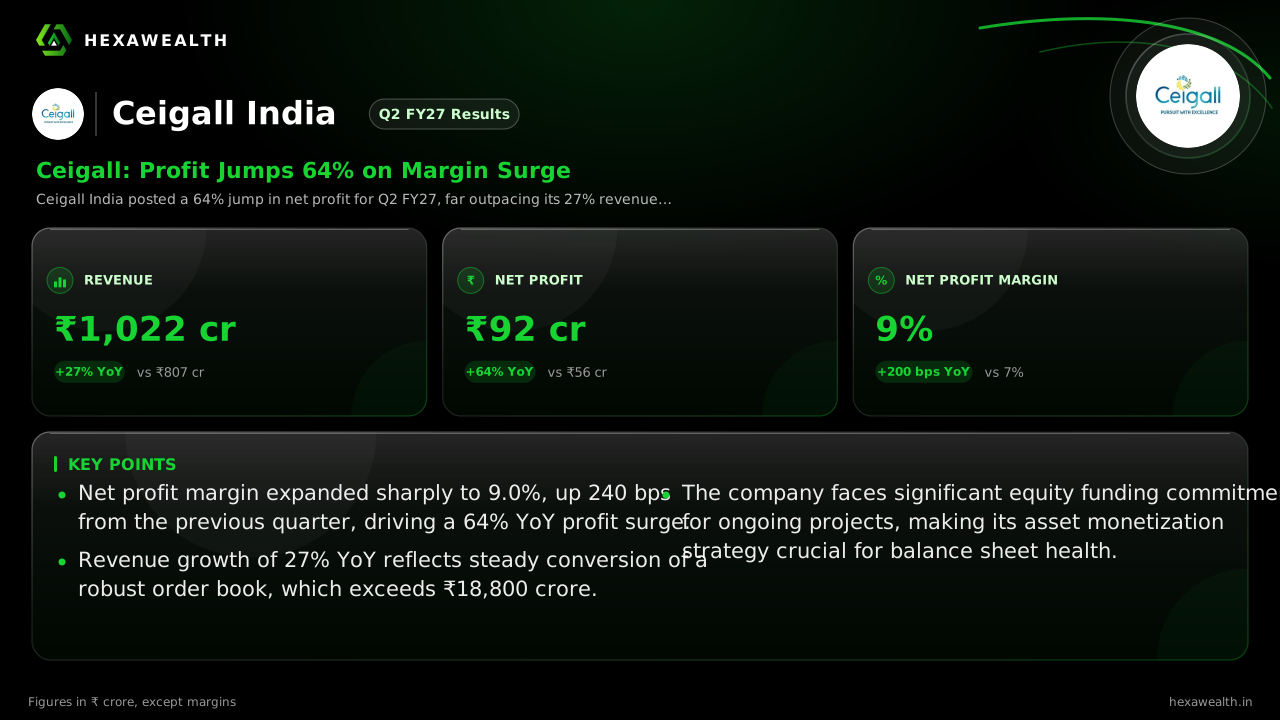
Ceigall India posted a 64% jump in net profit for Q2 FY27, far outpacing its 27% revenue growth. The surge was powered by a sharp 240 bps expansion in net profit margin, reflecting improved operational efficiency.
For infrastructure builders like Ceigall India, the story is about converting a massive order book into profitable execution. The September quarter shows that transition accelerating, with profit growth far outstripping the top line as operational efficiency improves.
Revenue rose 27% year-on-year to ₹1,022 crore, while net profit jumped 64% to ₹92 crore. The real story is the margin expansion: the net profit margin widened by 240 basis points sequentially to 9.0%, its highest level in the last five quarters.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,022.48YoY +27% | 969.64 | 806.57 |
| Profit (₹ Cr) | 92.17YoY +64% | 63.75 | 56.16 |
| Net Profit Margin | 9.0%YoY +29% | 6.6% | 7.0% |
The efficiency leap behind the profit surge
Profit grew more than twice as fast as revenue because costs were tightly managed. Total expenses rose just 2.4% quarter-on-quarter, while employee costs and interest saw single-digit increases. A sharp 19% year-on-year drop in depreciation also helped.
Management attributed earlier margin improvements to new project starts. According to a GuruFocus earnings call summary, the CFO noted that three new projects commencing in Q1 supported margins. This operational leverage appears to have carried into Q2.
A full pipeline with a funding question
The company's growth runway is clear. Its order book stood at ₹18,554 crore at the end of FY26, as reported by Multibagg.ai. ScanX.trade notes it has since grown to over ₹18,800 crore, providing visibility for years.
However, funding this execution is the critical test. The company has guided for equity commitments of ₹859 crore in FY27 for HAM and solar projects, according to a GuruFocus transcript. Its strategy of monetizing mature HAM assets to recycle capital will be key to managing this without straining leverage.
Key Points
- Net profit margin expanded sharply to 9.0%, up 240 bps from the previous quarter, driving a 64% YoY profit surge.
- Revenue growth of 27% YoY reflects steady conversion of a robust order book, which exceeds ₹18,800 crore.
- The company faces significant equity funding commitments for ongoing projects, making its asset monetization strategy crucial for balance sheet health.
Hexa Perspective
This quarter confirms Ceigall is in an execution sweet spot, translating order visibility into earnings with improving efficiency. The margin expansion is the standout, suggesting better project mix or cost control is taking hold.
The sustainability of this performance hinges on two factors: continued smooth execution without land or monsoon delays, and successful capital recycling from HAM asset sales to fund new equity commitments. If both hold, the current momentum has room to run.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.