Pritika Engineering Components (PRITIKA) Q2 FY27 Revenue More Than Doubles, But Profit Margins Shrink
The auto ancillary firm's September quarter revenue surged over 170% year-on-year, but higher costs from expansion and a weaker tractor market pressured profitability.
Pritika Engineering Components posted a massive 170% revenue jump in Q2 FY27, yet net profit margin slipped. The growth is driven by capacity ramp-up, but rising employee and interest costs are squeezing earnings.
For a precision components maker riding an auto industry upcycle, the test is whether sales growth can outrun the costs of building for it. Pritika Engineering Components’ September quarter shows the tension in full view: revenue more than doubled from a year ago, but profitability softened under the weight of its own expansion.
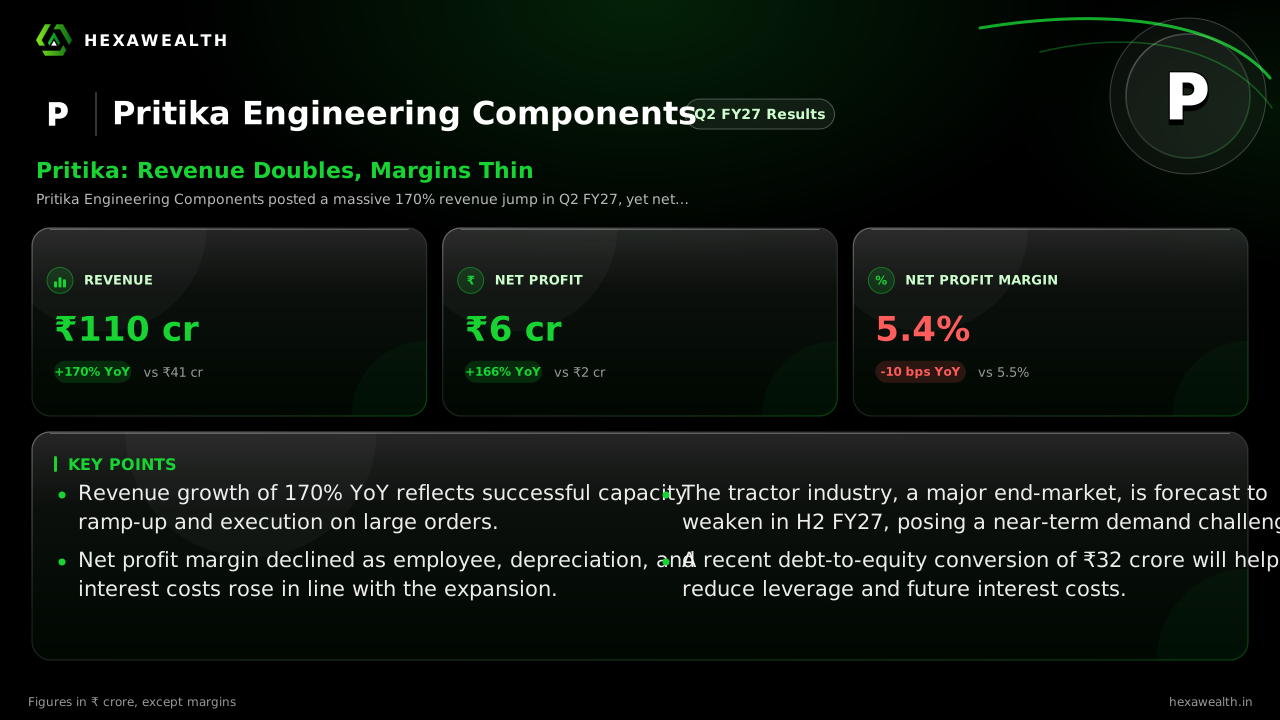
The numbers tell a story of powerful top-line momentum meeting operational strain. Consolidated revenue reached ₹109.86 crore, a 170% leap from the year-ago quarter. Profit followed at ₹5.99 crore, up 166%. Yet the net profit margin contracted to 5.4%, down 10 basis points year-on-year and 20 basis points sequentially.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 109.86 | 52.93 |
| Profit (₹ Cr) | 5.99 | 2.98 |
| Net Profit Margin (%) | 5.4 | 5.6 |
The costs of building capacity
The surge in sales is no accident. Flash Finance notes the company is in the midst of a significant capacity push, with capital work in progress nearly doubling since March. This expansion explains the sharp run-up in costs that kept pace with revenue. Employee costs soared 195% year-on-year, while depreciation rose 170% and interest climbed 132%.
These are the fixed costs of a business investing ahead of demand. The company is targeting an installed capacity of 100,000 tonnes per annum by FY27, according to a Reuters summary cited by Zerodha. The resulting higher operational leverage means every rupee of new sales is currently carrying more baggage to the bottom line.
A mixed demand outlook
Growth is being driven by execution on long-term orders, including a ₹70 crore deal for large castings. However, the broader market is turning. The tractor segment, a key end-market, is facing a sharp slowdown. Escorts Kubota forecasts a double-digit industry decline for the second half of FY27, as reported by Autocar Professional.
This creates a headwind just as Pritika’s new lines come online. While the company has diversified into railway and defense components, the near-term earnings trajectory will depend on how well it can offset softer tractor demand with other segments and maintain utilization of its new capacity.
A balance sheet in transition
Financing this growth has relied on debt, with a debt-to-equity ratio of 1.84. The company is actively addressing this. Shareholders recently approved converting ₹32 crore of promoter loans into equity, a move Flash Finance says will materially deleverage the balance sheet and cut future interest expense.
This financial engineering provides a clearer path to future margin improvement once the capital expenditure phase moderates. For now, the market reaction has been muted, with the stock largely flat around ₹78 following the results announcement, per data from Sharpely.
Key Points
- Revenue growth of 170% YoY reflects successful capacity ramp-up and execution on large orders.
- Net profit margin declined as employee, depreciation, and interest costs rose in line with the expansion.
- The tractor industry, a major end-market, is forecast to weaken in H2 FY27, posing a near-term demand challenge.
- A recent debt-to-equity conversion of ₹32 crore will help reduce leverage and future interest costs.
Hexa Perspective
The quarter captures Pritika at an inflection point. The explosive revenue growth validates its expansion strategy, but the margin compression shows the cost of that ambition arriving first. The coming quarters will test whether demand, particularly outside the softening tractor segment, can absorb the new capacity swiftly enough to restore operating leverage.
The planned deleveraging is a prudent step that shifts the financial structure from debt to equity, easing a persistent pressure point. Investors are left weighing the proven ability to scale sales against the cyclical risks in its core markets and the timeline for margins to recover.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.