Shahlon Silk (SHAHLON) Q2 FY27 Profit Falls 59% as Revenue More Than Halves
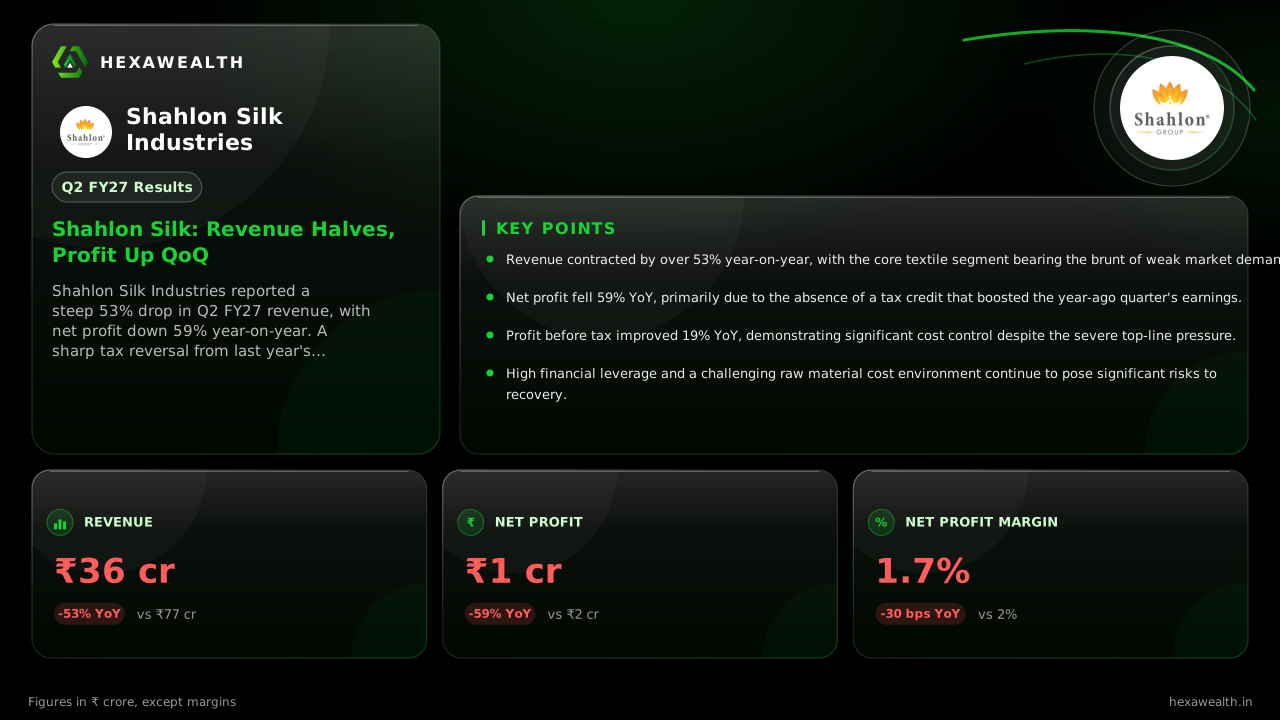
The textile manufacturer's revenue fell 53% year-on-year to ₹36.19 crore, while net profit dropped 59% to ₹0.63 crore despite a sequential improvement.
Shahlon Silk Industries reported a steep 53% drop in Q2 FY27 revenue, with net profit down 59% year-on-year. A sharp tax reversal from last year's credit drove the profit decline, even as pre-tax earnings improved.
For a textile manufacturer, a quarter where revenue more than halves is a severe demand shock. Shahlon Silk Industries' Q2 FY27 delivered exactly that, with sales dropping 53% year-on-year to ₹36.19 crore. Yet, a closer look reveals a business that cut costs sharply and actually improved its pre-tax earnings, only to be undone by a tax reversal from a one-off benefit last year.
The numbers show a company in a deep contraction. Revenue fell from ₹77.49 crore a year ago to ₹36.19 crore, and net profit dropped 59% to ₹0.63 crore. On a brighter note, profit rose 26% from the previous quarter, and the net profit margin inched up 40 basis points sequentially to 1.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 36.19 | 37.40 |
| Profit (₹ Cr) | 0.63 | 0.50 |
| Net Profit Margin | 1.7% | 1.3% |
The Tax Twist That Hid Operational Grit
A report from scanx.trade highlights a critical divergence. Profit before tax actually rose 19% year-on-year to ₹1.44 crore. The collapse in net profit was driven by a swing in tax treatment. In Q2 FY26, the company had a net tax credit of ₹0.34 crore, which flattered the bottom line. This quarter, it paid a net tax expense of ₹0.81 crore, a swing of over ₹1.15 crore that explains most of the profit decline.
A Sector-Wide Squeeze on Sales
The revenue plunge was led by the core textile segment, where sales more than halved, according to scanx.trade. The real estate and construction services segment fared slightly better but still declined 28%. This reflects a brutal environment for synthetic textiles, where manufacturers are caught between volatile raw material costs and weak demand. Reports note cotton yarn prices rose about 60% this year, squeezing downstream fabric makers.
Can Cost Cuts Sustain the Margin?
Total expenses fell 54% in line with the revenue drop, showing the company's ability to cut costs. However, this defensive posture has limits. MarketsMojo maintains a 'Sell' rating, citing a high debt-to-EBITDA ratio of 4.8 times and weak interest coverage. With revenue at a fraction of past levels, the heavy debt load of ₹123 crore as of March 2026 remains a persistent overhang on financial flexibility.
Key Points
- Revenue contracted by over 53% year-on-year, with the core textile segment bearing the brunt of weak market demand.
- Net profit fell 59% YoY, primarily due to the absence of a tax credit that boosted the year-ago quarter's earnings.
- Profit before tax improved 19% YoY, demonstrating significant cost control despite the severe top-line pressure.
- High financial leverage and a challenging raw material cost environment continue to pose significant risks to recovery.
Hexa Perspective
The quarter presents a paradox of operational discipline amid a demand collapse. Shahlon Silk managed to protect its pre-tax earnings by slashing costs in lockstep with falling sales. Yet, this is a survival tactic, not a growth strategy. The company's high debt and thin margins leave it vulnerable. A sustained recovery hinges on a meaningful rebound in textile demand, which the current industry volatility makes uncertain. Investors are left weighing the company's cost-control grit against a balance sheet that offers little room for error.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.