Simmonds Marshall (SIMMOND) Q2 FY27 Profit Jumps 32% as Revenue Hits Record High
The auto ancillary firm posted its highest-ever quarterly sales, with profit growth outpacing revenue on the back of strong commercial vehicle demand and lower interest costs.
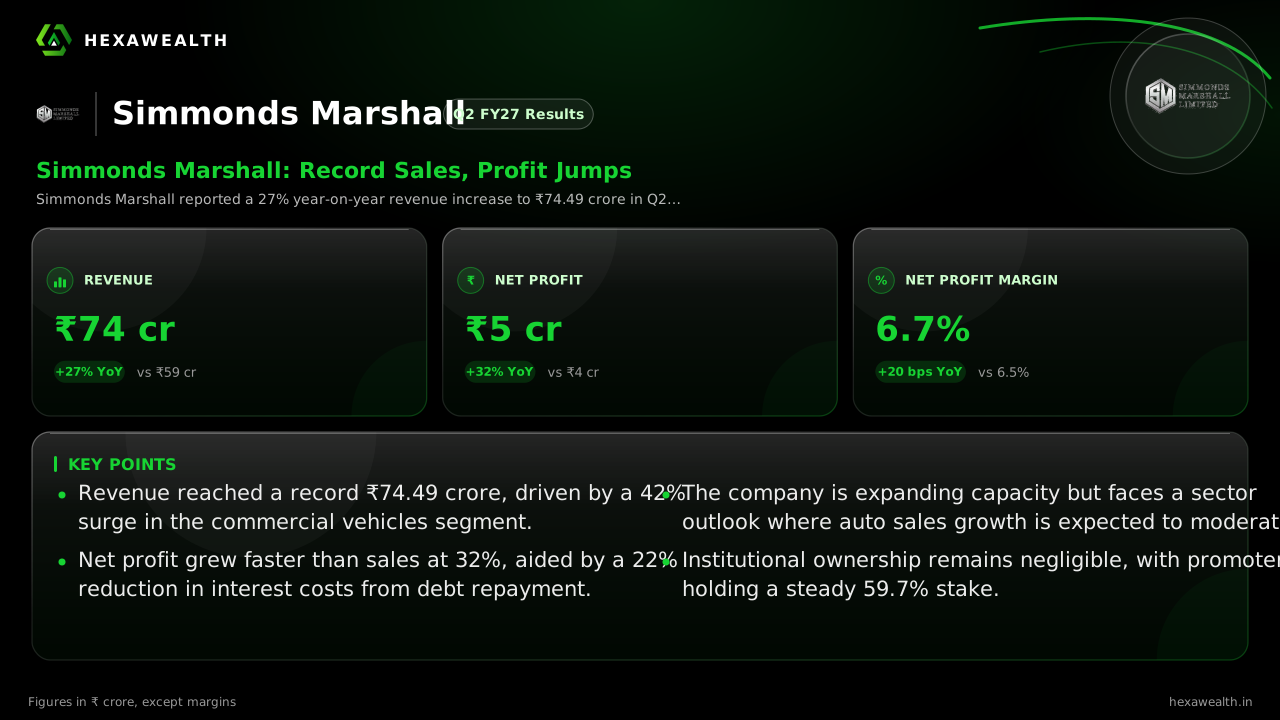
Simmonds Marshall reported a 27% year-on-year revenue increase to ₹74.49 crore in Q2 FY27, a record high. Net profit grew even faster, rising 32% to ₹4.99 crore, supported by a sharp reduction in debt and interest expenses.
For an industrial fastener maker, growth hinges on the health of its key automotive segments. Simmonds Marshall's September quarter showed that demand, particularly for commercial vehicles, remains robust, propelling the company to its strongest sales period on record.
Revenue rose 27% year-on-year to ₹74.49 crore, while net profit climbed 32% to ₹4.99 crore. The profit growth outpaced sales, lifting the net profit margin to 6.7%, an 80 basis point improvement from the June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 74.49 | 64.64 |
| Profit (₹ Cr) | 4.99 | 3.84 |
| Net Profit Margin (%) | 6.7 | 5.9 |
Growth Led by Commercial Vehicles
The revenue surge was led by the commercial vehicles segment, which grew 42% year-on-year in the first half, as reported by ScanX. The two-wheeler segment, contributing half of total revenue, also grew a healthy 19%. This broad-based demand helped the company bounce back strongly from a softer June quarter.
A Leaner Balance Sheet Lifts Profit
Profit growth was amplified by a significant reduction in finance costs, which fell 22% year-on-year. According to ScanX, this was the result of a deliberate deleveraging strategy, with total borrowings cut by 23% since March 2026. Lower interest expenses flowed directly to the bottom line.
The Outlook and Market Read
Management has not provided formal guidance, but the company is expanding its annual cold-forming capacity from 12,000 MT to 15,000 MT to support growth. The broader sector outlook, however, suggests a moderation. The Economic Times cites Monarch Networth Capital expecting auto sales growth to cool in the second half of FY27 after strong festive demand.
MarketsMojo upgraded the company's financial trend to 'very positive' but maintains a 'Hold' rating, noting operational challenges like slower collection cycles. The stock has delivered strong returns, up 56% over the past year, but trades at a significant discount to the industry average P/E.
Key Points
- Revenue reached a record ₹74.49 crore, driven by a 42% surge in the commercial vehicles segment.
- Net profit grew faster than sales at 32%, aided by a 22% reduction in interest costs from debt repayment.
- The company is expanding capacity but faces a sector outlook where auto sales growth is expected to moderate.
- Institutional ownership remains negligible, with promoters holding a steady 59.7% stake.
Hexa Perspective
This quarter showcases Simmonds Marshall's ability to capitalize on cyclical upturns while actively strengthening its balance sheet. The profit beat was more about financial engineering through debt reduction than a dramatic operating margin expansion. The sustainability of this performance now depends on whether end-market demand holds up against a forecasted slowdown. The capacity expansion is a vote of confidence, but the thin net profit margin leaves little room for error if input costs rise or growth falters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.