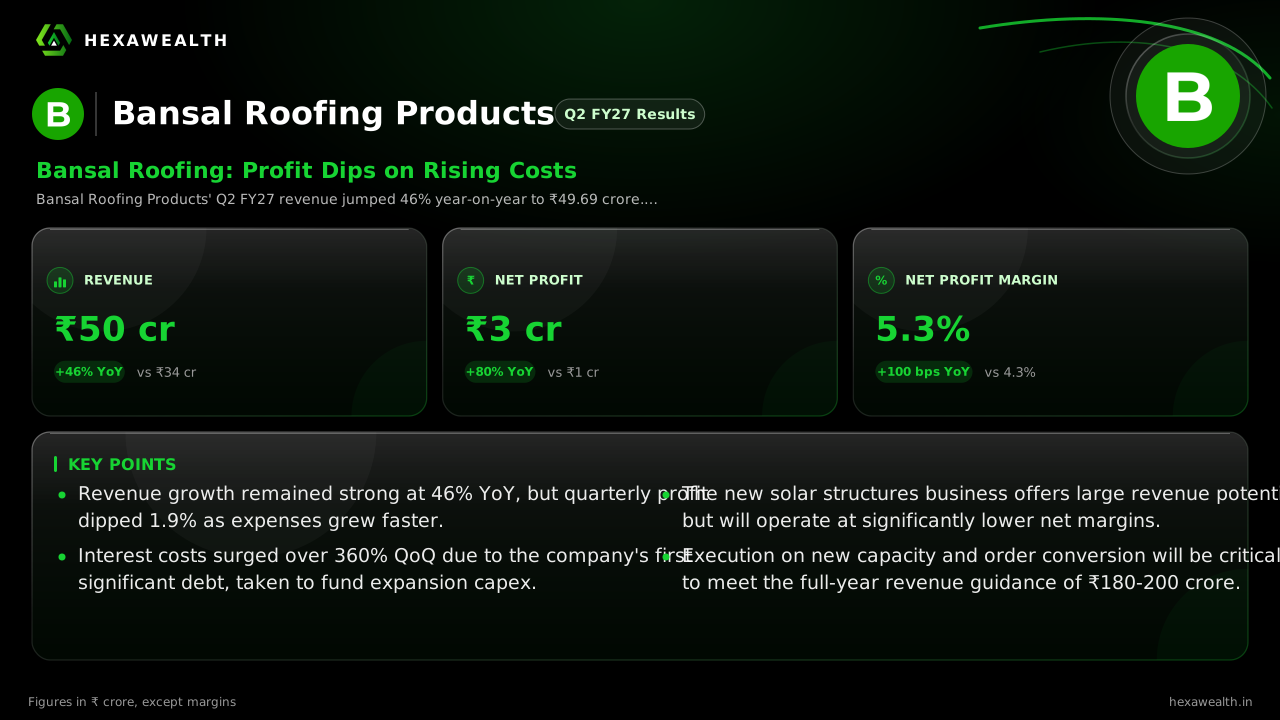
Bansal Roofing Products' Q2 FY27 revenue jumped 46% year-on-year to ₹49.69 crore. However, net profit slipped 1.9% from the previous quarter to ₹2.62 crore as interest costs rose sharply.
For Bansal Roofing Products, the September quarter was a story of robust demand meeting the costs of funding its own growth. The company delivered a 46% surge in revenue from a year ago, yet profit slipped slightly from the June quarter as interest expenses ballooned.
Revenue reached ₹49.69 crore, up 8.3% sequentially. Net profit, however, eased to ₹2.62 crore, a 1.9% dip from Q1. This pushed the net profit margin down 50 basis points to 5.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Metric
CurrentQ2 FY27 (Sep 26)
PreviousQ1 FY27 (Jun 26)
Revenue (₹ Cr)
49.69
45.89
Profit (₹ Cr)
2.62
2.67
PAT Margin (%)
5.3
5.8
The squeeze from higher costs
The year-on-year profit jump of 79.5% tells a story of recovery from a low base. The sequential dip reveals a cost pinch. Total expenses rose 9.3% quarter-on-quarter, slightly outpacing revenue growth. The standout was a 361.5% surge in interest costs, which the company attributed to its first debt of ₹5-6 crore for machinery capex, according to a Q1 earnings call summary.
This debt funded a ₹5 crore capital expenditure in Q1, part of a major capacity expansion. Management, cited in an investor presentation, expects better margin retention once new machinery reduces reliance on third-party job work.
A strategic shift into solar
Growth is not just about more of the same. The company has strategically entered the solar module mounting structures (MMS) business, with production beginning this quarter. Reports from an earnings call summary note this segment could bring ₹20 crore in monthly revenue at full scale, but with net margins of just 2.5-3%.
This is a trade-off: volume for margin. It also coincides with rising input costs. Data from the Press Information Bureau shows galvanized plain (GP) sheet prices were up 27.7% year-on-year in September, pressuring the core roofing business.
The outlook hinges on execution
The company's order book stood at about two months of revenue as of the last update, according to a scanx.trade report. Its Phase 5 and 6 expansions, adding 200 metric tons of monthly PEB capacity, were slated for completion by mid-September 2026.
Management has reaffirmed its FY27 revenue guidance of ₹180-200 crore, calling it conservative as it excludes potential solar revenue. The path to hitting that target now depends on smoothly ramping up new capacity and managing the margin mix between high-margin PEB work and the new, lower-margin solar vertical.
Key Points
Revenue growth remained strong at 46% YoY, but quarterly profit dipped 1.9% as expenses grew faster.
Interest costs surged over 360% QoQ due to the company's first significant debt, taken to fund expansion capex.
The new solar structures business offers large revenue potential but will operate at significantly lower net margins.
Execution on new capacity and order conversion will be critical to meet the full-year revenue guidance of ₹180-200 crore.
“
Hexa Perspective
Bansal Roofing is in a classic growth investment phase. The stellar top-line growth is real, but profitability is being tested by the costs of that expansion and a strategic pivot. The 50 bps sequential margin compression, while modest, signals that operating leverage is not yet kicking in.
The coming quarters will show if the new PEB capacity can be filled with high-margin orders to offset the dilutive effect of the solar business and elevated steel prices. The company's historically strong return on equity of nearly 25% provides a buffer, but the margin trajectory from here will define the quality of this growth cycle.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Bansal Roofing Products' Q2 FY27 results?
Bansal Roofing Products reported Q2 FY27 revenue of ₹49.69 crore, a 45.8% increase from the same quarter last year. Net profit for the quarter was ₹2.62 crore, up 79.5% year-on-year but down 1.9% from the previous quarter (Q1 FY27).
Why did Bansal Roofing Products' Q2 profit dip sequentially?
Bansal Roofing's Q2 FY27 net profit dipped 1.9% quarter-on-quarter to ₹2.62 crore despite higher revenue. This was primarily due to a sharp 361.5% increase in interest expense, linked to debt taken for machinery capex, which outpaced revenue growth for the quarter.
What is Bansal Roofing Products' FY27 revenue guidance?
Bansal Roofing Products management has reaffirmed its FY27 revenue guidance of ₹180-200 crore, as noted in an earnings call summary. This represents 25-32% growth over FY26 revenue and is considered conservative as it excludes potential revenue from the new solar structures business.
What drove the 45.8% YoY revenue growth for Bansal Roofing in Q2?
Bansal Roofing's 45.8% year-on-year revenue growth in Q2 FY27 was driven by robust demand in the roofing and insulation sector, according to a scanx.trade report. The company has also been expanding its pre-engineered building (PEB) capacity, which supported higher sales volumes.
Why did interest expense surge in Q2 FY27?
Bansal Roofing's interest expense surged 361.5% quarter-on-quarter in Q2 FY27. This was due to the company taking on its first significant debt of ₹5-6 crore, as mentioned in a Q1 earnings call summary, to fund machinery capital expenditure for its ongoing expansion plans.
What is Bansal Roofing's new solar business?
Bansal Roofing has entered the Solar Module Mounting Structures (MMS) business, with production starting in Q2 FY27. An investor call summary notes it has a capacity of 2,500 MT per month and could contribute up to ₹20 crore in monthly revenue, though with net margins of only 2.5-3%.
What is Bansal Roofing's current order book status?
As of the last management commentary, Bansal Roofing's order book was around two months of revenue, or roughly ₹30-35 crore. The company has recently secured an order worth ₹8.5 crore, as reported by scanx.trade.
What are Bansal Roofing's capacity expansion plans?
Bansal Roofing is undergoing Phase 5 and 6 expansions, expected to add 200 metric tons per month of light fabrication PEB capacity by mid-September 2026. The company also commissioned a solar MMS line with a capacity of 2,500 MT per month in Q2 FY27.
Did Bansal Roofing Q2 results beat analyst estimates?
There is no widely published analyst consensus for Bansal Roofing's Q2 FY27. A Flash Finance tracker measured the quarter against the company's own historical trend, noting sales were 5% above its trend line while net profit was 10% above, classifying it as 'above trend'.
What is the update on Bansal Roofing's working capital?
Bansal Roofing's working capital efficiency improved in H1 FY27. A multibagg.ai report states operating cash flow surged to ₹13.26 crore, aided by a ₹1.88 crore reduction in trade receivables and a ₹3.72 crore increase in other current liabilities.
Bansal Roofing Products reported a 79% year-on-year rise in net profit to ₹2.62 crore for Q2 FY27, ending September 2026. This growth came on a 46% increase in revenue to ₹49.69 crore, though profit was slightly down from the ₹2.67 crore reported in the previous quarter.
Bansal Roofing Products Q2 Results FY27: PAT Rs 2.62 Cr
Bansal Roofing Products Q2 FY27 results, declared on November 4, 2026, show a Profit After Tax (PAT) of ₹2.62 crore. This is a 79.45% increase from the ₹1.46 crore PAT in Q2 FY26, according to the company's filing.
Bansal Roofing net profit up 79% in Q2FY27; approves DIPPL acquisition
Bansal Roofing's net profit rose 79% year-on-year to ₹2.62 crore in Q2 FY27. The board also approved the acquisition of a 79.959% stake in Durapuf Insutech Panels Private Limited (DIPPL) for ₹3.91 crore, expanding its product portfolio into insulated panels.