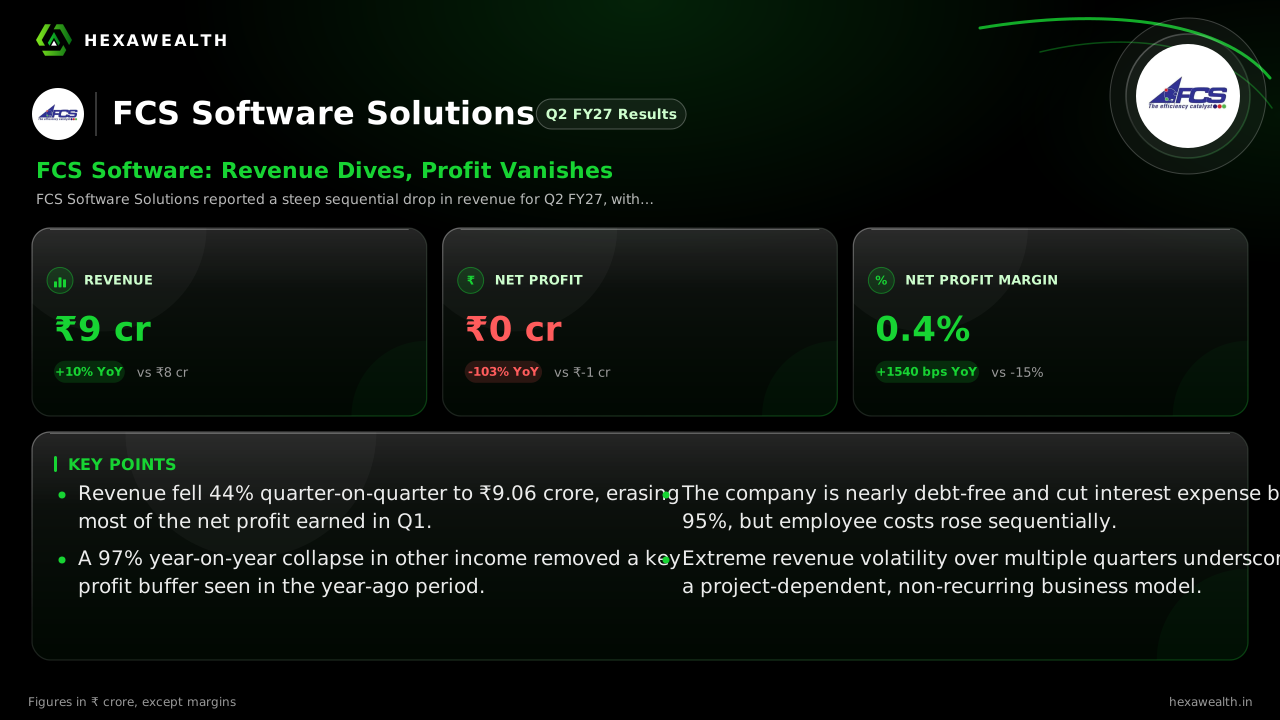
FCS Software (FCSSOFT) Q2 FY27 Profit Nears Zero as Revenue Plunges 44% Sequentially
FCS Software's September quarter revenue fell sharply from June, erasing most of its net profit and underscoring a volatile, project-driven business model.
FCS Software Solutions reported a steep sequential drop in revenue for Q2 FY27, with profit nearly wiped out. While the company improved year-on-year, the quarter highlights its struggle to maintain consistent top-line momentum.
For FCS Software, the story is one of extreme quarterly volatility, where revenue can swing by tens of crores and profits evaporate overnight. The September quarter delivered the latest chapter, as a sharp sequential drop in sales left the company with barely any net profit, despite a cleaner cost sheet.
Revenue for Q2 FY27 was ₹9.06 crore, up 10.4% from a weak year-ago quarter but down a steep 43.8% from the ₹16.12 crore posted in June. Net profit shrank to just ₹0.04 crore, a 93.7% sequential drop. The company's net profit margin, at 0.4%, is a fraction of its trailing twelve-month average of 6.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 9.06 | 16.12 |
| Profit (₹ Cr) | 0.04 | 0.63 |
| Net Profit Margin (%) | 0.4 | 3.9 |
The Collapse in Other Income
A key driver of the profit squeeze was a near-total disappearance of other income, which fell 97% year-on-year to just ₹0.07 crore. According to reports from scanx.trade, consolidated other income also fell sharply. This suggests the prior-year quarter was flattered by non-operational gains that did not repeat, making the underlying operational performance appear weaker in comparison.
Costs and Cash
Total expenses fell 24.5% year-on-year, aided by a 95% drop in interest costs as the company remains nearly debt-free, per analysis from univest.in. However, employee costs rose 7.3% sequentially even as revenue fell, hinting at a sticky cost structure. The company also executed a significant share buyback, with scanx.trade reporting a consolidated cash outflow of ₹36.4 crore for this purpose in the half-year.
A Volatile Path Forward
The company has not published formal guidance, but its investor presentation highlighted an "improving margin outlook," according to arthneeti.com. For investors, the core challenge is the firm's wildly inconsistent revenue, which has swung from ₹27 crore to ₹8 crore over the past five quarters. This pattern points to a business reliant on large, episodic projects rather than stable recurring streams.
Key Points
- Revenue fell 44% quarter-on-quarter to ₹9.06 crore, erasing most of the net profit earned in Q1.
- A 97% year-on-year collapse in other income removed a key profit buffer seen in the year-ago period.
- The company is nearly debt-free and cut interest expense by 95%, but employee costs rose sequentially.
- Extreme revenue volatility over multiple quarters underscores a project-dependent, non-recurring business model.
Hexa Perspective
The quarter lays bare the operational reality behind the headline year-on-year improvement. Moving from a loss to a tiny profit is progress, but the precipitous sequential drop in revenue is the more telling signal. It suggests the business lacks the contract visibility or annuity streams to smooth out its earnings.
The path to stability requires converting project wins into sustained client relationships. Until that happens, the stock's valuation—trading at a P/E of 77.1, a 301% premium to the industry—appears disconnected from the fundamental volatility on display. Investors are paying for a transformation that the quarterly numbers have yet to demonstrate.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.