EMA Partners India (EMAPARTNER) Q2 FY27 Profit Lags as Revenue Doubles on Taggd Acquisition
The executive search firm's revenue more than doubled year-on-year in Q2 FY27, but profit grew only 27% as new business investments and debt costs weighed on margins.
EMA Partners India's Q2 FY27 revenue surged 107% YoY to ₹83.93 crore, primarily from its acquisition of recruitment firm Taggd. However, net profit grew just 27% as heavy investments in new businesses and rising interest expenses sharply contracted profitability.
For EMA Partners India, the September quarter was about scaling up through acquisition. The executive search firm integrated Taggd, a large recruitment process outsourcing business it bought earlier this year, instantly boosting its top line. The result was a quarter of explosive revenue growth but a significant squeeze on the bottom line, as the costs of funding and running new ventures arrived ahead of their full profit contribution.
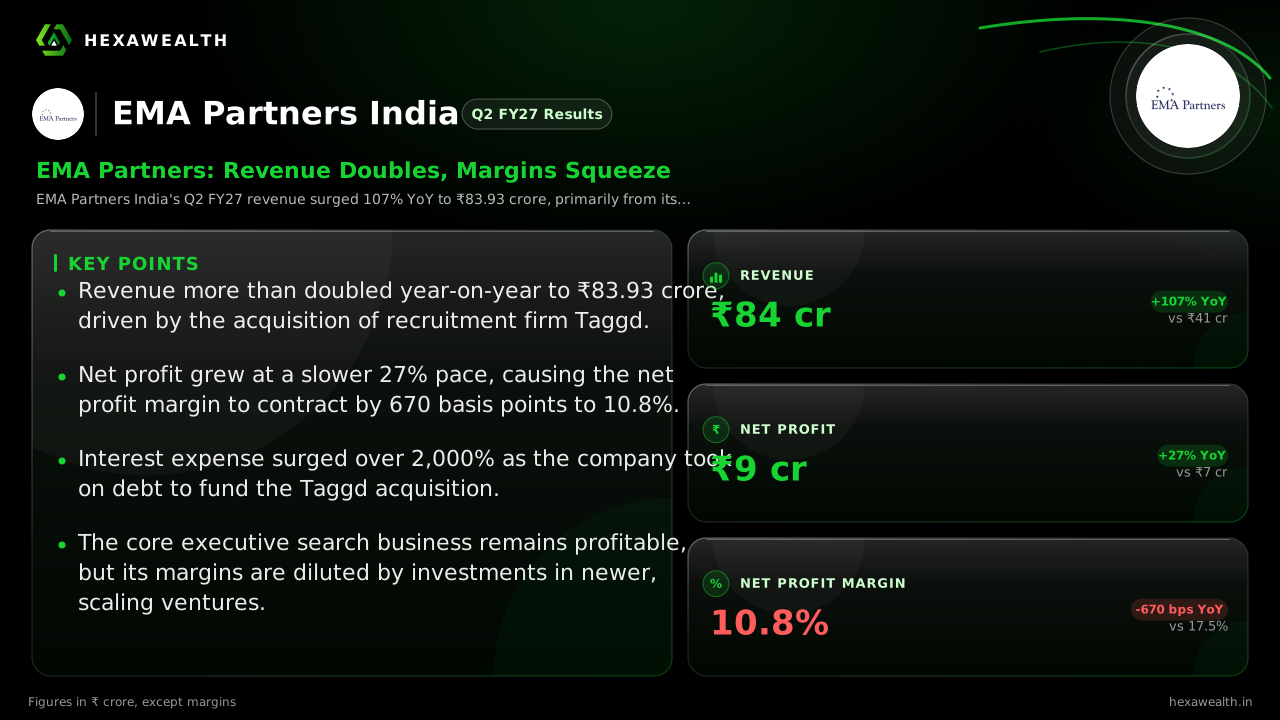
The numbers show the tension. Revenue more than doubled year-on-year to ₹83.93 crore. Profit after tax grew a more modest 27% to ₹9.04 crore. The net profit margin fell 670 basis points from a year ago to 10.8%, as detailed in the table below.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
Metric
CurrentSep 2026 (Q2 FY27)
PreviousMar 2026 (Q4 FY26)
Revenue (₹ Cr)
83.93
46.84
Profit (₹ Cr)
9.04
5.20
Net Profit Margin (%)
10.8
11.1
The Acquisition That Changed the Scale
The revenue surge was driven by the consolidation of Taggd, according to the company's investor presentation cited by Arthneeti. New business revenue, which includes Taggd and the scaling James Douglas brand, grew 6.4 times year-on-year. The firm's mature executive search business grew a steadier 9%.
This acquisition-fueled growth came with immediate costs. Employee expenses rose 124% year-on-year, likely from integrating Taggd's workforce. More strikingly, interest costs surged over 2,000% as the company took on debt to fund the deal. Long-term borrowings rose sharply from ₹2.28 million in FY26 to ₹212.82 million in H1 FY27, the presentation noted.
A Market Ready for Growth
The underlying demand environment remains strong. The Economic Times reported that India's executive search firms saw business grow 15-25% in the first half of the financial year. EMA's Managing Director Krishnan Sudarshan told the paper the market was "looking pretty good," with industrial and manufacturing mandates particularly strong.
This robust sector tailwind supports the core business, which the company says maintains a healthy EBITDA margin around 25.5%. The challenge is that this profitable core is now diluted by the newer, loss-making ventures as they scale.
The Path to Profitability
Management has previously set a clear expectation. On an April 2026 earnings call, they stated the newer James Douglas and MyRCloud businesses should be EBITDA and profit positive in FY27. The current quarter's margin squeeze is the cost of reaching that milestone.
The stock market's reaction has been muted historically. Data from Inve.money shows the share price moved an average of ±1.7% following the last two results. The stock trades at a P/E of 16.9, a significant discount to the industry average of 34.3, reflecting investor caution over the margin trajectory.
Key Points
Revenue more than doubled year-on-year to ₹83.93 crore, driven by the acquisition of recruitment firm Taggd.
Net profit grew at a slower 27% pace, causing the net profit margin to contract by 670 basis points to 10.8%.
Interest expense surged over 2,000% as the company took on debt to fund the Taggd acquisition.
The core executive search business remains profitable, but its margins are diluted by investments in newer, scaling ventures.
“
Hexa Perspective
EMA Partners is in a deliberate investment phase, trading near-term margins for scale and a broader service stack. The Taggd acquisition has instantly made it a larger player in tech-led recruitment, but the benefits of integration and operating leverage are yet to fully materialize.
The next few quarters will test management's ability to steer the new businesses to profitability as guided. Success would mean a return to healthier consolidated margins. The stock's discount to the sector suggests the market is pricing in execution risk, waiting for proof that the margin sacrifice will pay off.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were EMA Partners India's Q2 FY27 results?
EMA Partners India reported revenue of ₹83.93 crore and a net profit of ₹9.04 crore for the quarter ended September 2026 (Q2 FY27). Revenue more than doubled year-on-year, while profit grew 27%. The net profit margin contracted to 10.8% from 17.5% a year ago.
Why did EMA Partners India's profit grow only 27% YoY despite revenue doubling?
Profit growth lagged revenue because of a sharp contraction in margins. Costs surged due to investments in new business lines and debt taken on for the Taggd acquisition. Employee costs rose 124% and interest expense jumped over 2,000% year-on-year, significantly pressuring profitability.
What drove the 107% YoY revenue surge for EMA Partners India in Q2 FY27?
The revenue surge was primarily driven by the consolidation of Taggd, a recruitment process outsourcing firm EMA Partners acquired. According to Arthneeti, new business revenue, which includes Taggd, grew 6.4 times year-on-year during the first half of FY27.
Why did employee costs at EMA Partners India rise 124% YoY in Q2 FY27?
Employee costs rose sharply due to the integration of the newly acquired Taggd business and investments in scaling newer verticals like James Douglas. The company's headcount and related expenses increased significantly as it built out these growth platforms.
What caused the 2068% YoY increase in interest expense for EMA Partners India?
Interest expense surged because the company took on significant debt to fund the acquisition of Taggd. According to Arthneeti, long-term borrowings rose from ₹2.28 million in FY26 to ₹212.82 million in H1 FY27, leading to the dramatic increase in finance costs.
What is the cash flow position of EMA Partners India?
The cash flow position tightened due to acquisition spending. A separate entity, EMA India Limited, reported in its unaudited results a net decrease in cash and cash equivalents of ₹107.17 lakhs for the half-year ended September 2026, with cash used in operating activities.
What guidance did EMA Partners India management provide for FY27?
In prior commentary, management stated the newer James Douglas and MyRCloud businesses are expected to be EBITDA and profit positive in FY27. They also aim to maintain the core search business's EBITDA margin around 24-25% as it adds capacity.
What is the current demand environment for executive search services in India?
Demand is strong. The Economic Times reported executive search firms saw 15-25% business growth in H1 FY27. EMA's MD noted the market looks good, with industrial, manufacturing, and a reviving financial services sector driving mandates.
Is EMA Partners India gaining market share from global firms?
EMA Partners holds an estimated 2.6% share of the Indian executive search market. While it is among the top domestic players, the top four or five international firms together command roughly half the market, leaving room for a focused local player to grow.
Did EMA Partners India's Q2 FY27 results beat analyst estimates?
The available research does not cite specific analyst estimates for Q2 FY27. The results presentation from Arthneeti focuses on the company's reported figures, showing revenue doubled and profit grew 27% with significant margin pressure.
What are brokerages saying about EMA Partners India stock after Q2 FY27 results?
The research snippets do not contain specific post-results brokerage commentary, ratings, or target price changes from major firms like ICICI Securities or Motilal Oswal for the Q2 FY27 period.
How did EMA Partners India's stock price react to the Q2 FY27 results?
Specific price action following the November 14, 2026 announcement is not detailed in the research. Historical data from Inve.money shows the stock has moved an average of ±1.7% following recent results releases.
Does EMA Partners India have client concentration risk?
The revenue base appears diversified. According to Newboard, repeat customers gave 76.4% of FY24 revenue, and the ten largest clients contributed 34.5%, with the single largest at 13.2%, indicating moderate concentration.
EMA Partners India Q2 profit drop
EMA Partners India's Q2 FY27 net profit did not drop; it increased 27% year-on-year to ₹9.04 crore. However, this growth was far slower than the 107% revenue surge, leading to a significant contraction in net profit margin.
EMA Partners India Q2 FY27 results order book
The provided research on EMA Partners India's Q2 FY27 results does not contain specific information or figures regarding the company's order book for the quarter ended September 2026.