Lloyds Luxuries (LLOYDS) Q2 FY27 Revenue Jumps 28% but Profit Stalls at ₹0.35 Crore
The luxury grooming franchisee posted strong top-line growth but barely turned a profit, as rising costs consumed its sales gains.
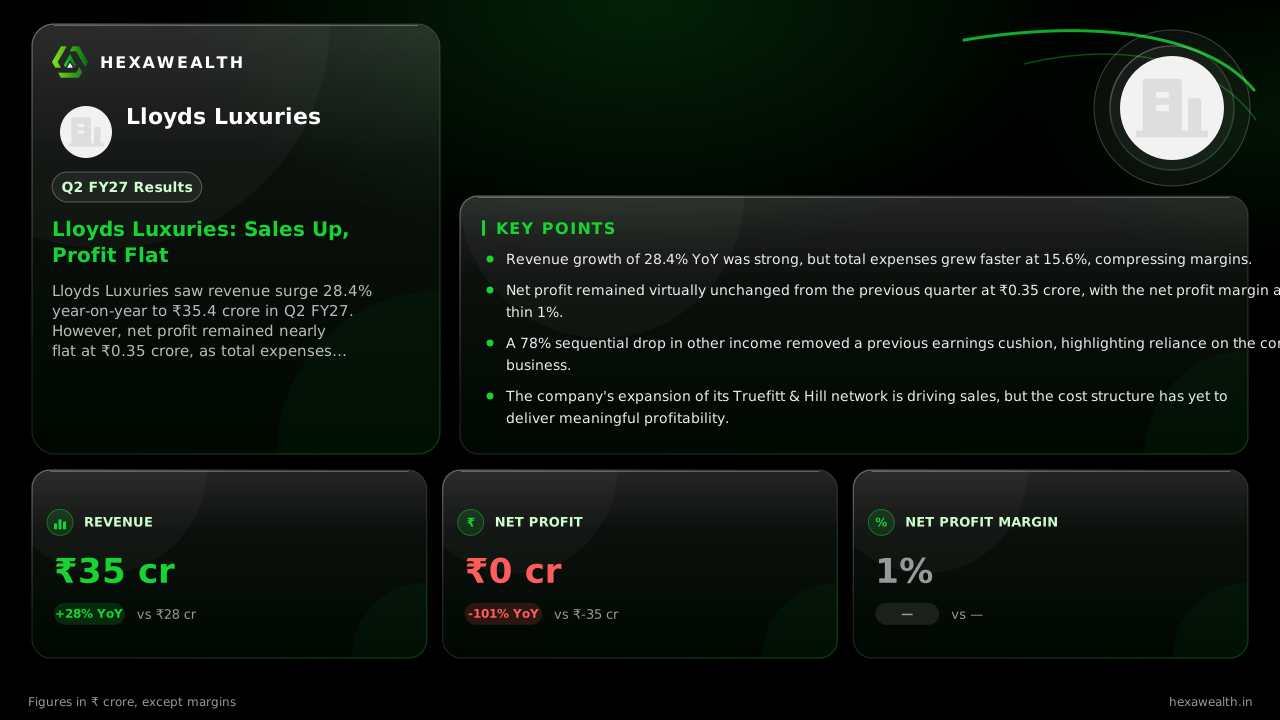
Lloyds Luxuries saw revenue surge 28.4% year-on-year to ₹35.4 crore in Q2 FY27. However, net profit remained nearly flat at ₹0.35 crore, as total expenses grew faster than sales.
For a luxury grooming franchise built on a 220-year-old brand, growth is measured in new outlets and premium service uptake. Lloyds Luxuries delivered on the first count, with revenue jumping 28.4% year-on-year. Yet the bottom line tells a different story, with profit barely budging from the previous quarter.
The numbers show a business expanding but not yet earning. Revenue reached ₹35.4 crore, up 6.6% sequentially. Net profit, however, was a wafer-thin ₹0.35 crore, essentially flat from Q4 FY26. The net profit margin slipped to 1.0%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin %
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 35.4YoY +28% | 27.57 |
| Profit (₹ Cr) | 0.35YoY +101% | -34.73 |
| Net Profit Margin % | 1.0 | – |
Where the sales growth went
Expenses rose 15.6% from a year ago, outpacing revenue. Employee costs climbed 9.6% YoY and 3.8% sequentially, reflecting the staff needed to run a growing network. According to a report by Sharpely, total operating expenses have consistently run ahead of revenue, a trend that continued this quarter.
The other income line, which provided a small cushion last quarter, collapsed by 78% sequentially to just ₹0.04 crore. This sharp drop eliminated a minor profit buffer, leaving the core business to carry the entire load.
The path to real profitability
Management has pointed to capital spending for past losses. The company's master franchise for Truefitt & Hill runs to 2043, and its store locator shows 38 outlets across India. Expansion is the stated goal, with a plan to reach 50 stores.
Yet the economics of scaling a premium service business are tough. The Indian salon and spa chain market is growing at over 11%, but it is also intensely competitive and labor-intensive. For Lloyds, the challenge is to translate its historic brand appeal into operating leverage.
The stock closed at ₹65.00 on November 4, the day the board met to approve results. It has fallen 21.5% over the past year. With negligible institutional ownership, the market is waiting for proof that growth can turn into earnings.
Key Points
- Revenue growth of 28.4% YoY was strong, but total expenses grew faster at 15.6%, compressing margins.
- Net profit remained virtually unchanged from the previous quarter at ₹0.35 crore, with the net profit margin a thin 1%.
- A 78% sequential drop in other income removed a previous earnings cushion, highlighting reliance on the core business.
- The company's expansion of its Truefitt & Hill network is driving sales, but the cost structure has yet to deliver meaningful profitability.
Hexa Perspective
The quarter confirms Lloyds Luxuries is in a growth investment phase. Revenue is climbing as it opens stores, but the cost of that expansion—both in staff and overhead—is eating the gains. The path to sustainable profit requires operating leverage it hasn't yet shown.
Investors are weighing the value of the exclusive, long-dated franchise against a history of losses. The stock's decline suggests skepticism. The next few quarters must demonstrate that sales growth can outrun the cost base, or the story remains one of potential, not performance.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.