Talbros Engineering (TALBROSENG) Q2 FY27 Profit Drops 7% as Costs Outrun Strong Sales
The axle shaft maker's revenue grew 12% year-on-year, but a sharp rise in raw material and employee costs pushed net profit lower.
Talbros Engineering reported a 12% jump in quarterly revenue, driven by higher sales volumes. However, net profit fell 7% as raw material and employee costs rose faster, squeezing margins amid an aggressive expansion cycle.
For an auto ancillary supplier, a strong quarter hinges on turning robust vehicle production into stable profits. Talbros Engineering’s September quarter delivered the first part, with revenue hitting a record ₹146 crore, but saw the second slip away as costs ran ahead.
The numbers show a clear split. Revenue grew 12% from a year ago and sequentially from the June quarter. Profit, however, fell 7% year-on-year and 3% quarter-on-quarter to ₹6.1 crore. The net profit margin compressed to 4.2%, down 80 basis points from last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 146.21YoY +12% | 130.37 | 130.70 |
| Profit (₹ Cr) | 6.09YoY -6.9% | 6.28 | 6.54 |
| Net Margin (%) | 4.2YoY -16% | 4.8 | 5.0 |
Why the growth didn't reach the bottom line
This was a margin story, not a volume one. According to a Stockwatch report, the cost of raw materials consumed jumped nearly 16% year-on-year, outpacing the 12% revenue growth. Employee benefit expense surged 25% in the same period.
These twin pressures squeezed the operating line. Below that, finance costs rose 14% year-on-year and a sharp 34% from the prior quarter to ₹4.2 crore. This aligns with a significant capital expenditure push.
The expansion behind the interest bill
Long-term borrowings rose to ₹88 crore at the end of September from ₹60 crore at the end of March, as noted by Stockwatch. The company funded ₹40 crore of fixed-asset purchases in the first half of the year, with capital work-in-progress nearly doubling. It is also setting up a new manufacturing unit in Madhya Pradesh.
The market reaction was negative, with the stock declining after the results. MarketsMojo reported a downgrade in its proprietary grade from Hold to Sell, citing margin contraction and elevated interest expenses.
Key Points
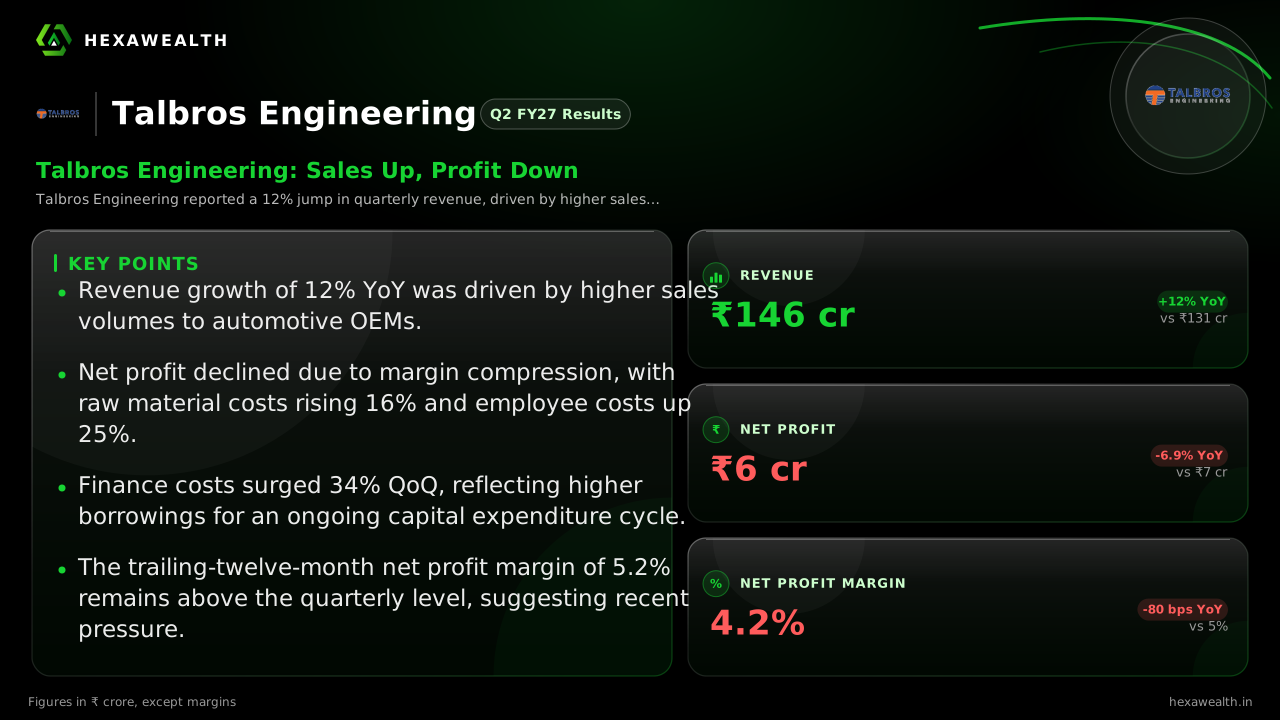
- Revenue growth of 12% YoY was driven by higher sales volumes to automotive OEMs.
- Net profit declined due to margin compression, with raw material costs rising 16% and employee costs up 25%.
- Finance costs surged 34% QoQ, reflecting higher borrowings for an ongoing capital expenditure cycle.
- The trailing-twelve-month net profit margin of 5.2% remains above the quarterly level, suggesting recent pressure.
Hexa Perspective
Talbros is caught between a cyclical uptick in auto demand and a structural rise in its own costs. The quarter confirms that top-line growth alone is insufficient when input inflation and an ambitious capex plan bite simultaneously.
The squeeze has at least another quarter to run. Relief depends on whether raw material costs moderate and if new capacity can start contributing to output before interest costs climb further. For now, the balance sheet is funding growth, but profitability is paying the price.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.