Tai Industries (TAIIND) Q2 FY27 Profit Returns on a Thin Margin After Revenue Triples
The distributor's sales soared 171% year-on-year, but its net profit margin stayed at 1.2%, with cash flow deeply negative as working capital swelled.
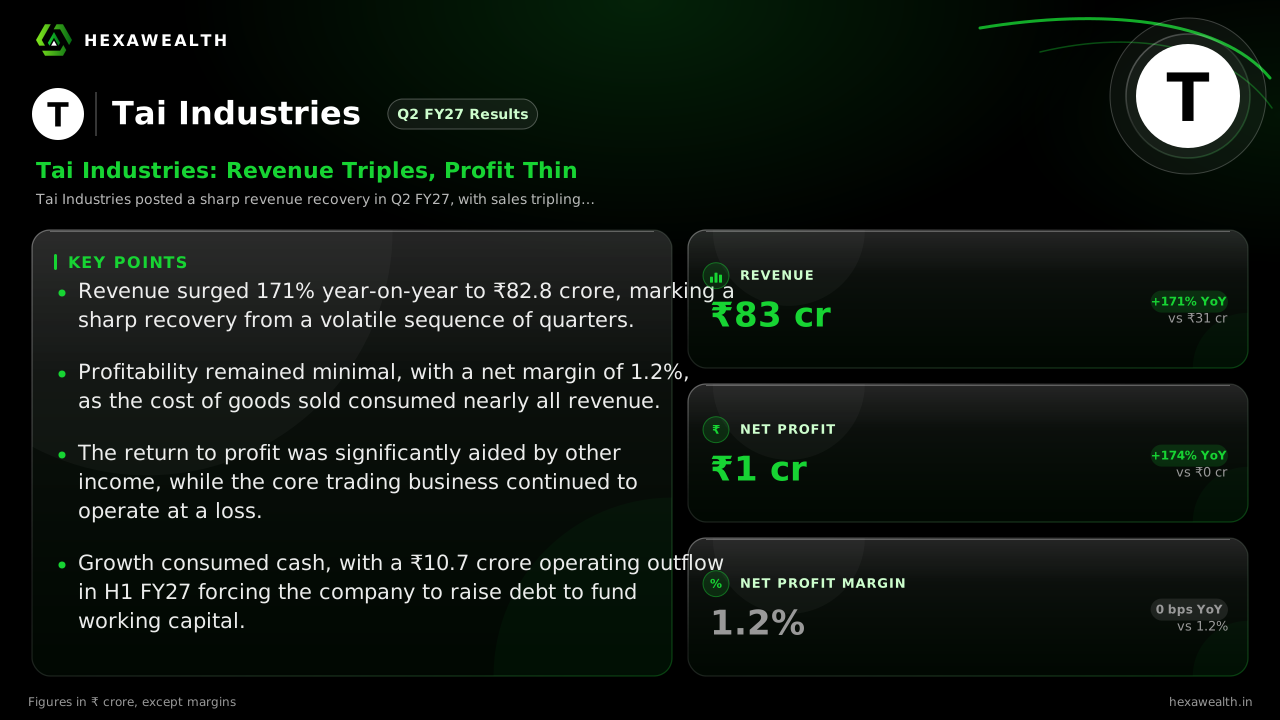
Tai Industries posted a sharp revenue recovery in Q2 FY27, with sales tripling year-on-year to ₹82.8 crore. However, profitability remained wafer-thin, and a large cash outflow highlighted the cost of funding this volatile trading growth.
For a distributor like Tai Industries, growth is measured in turnover, but survival hinges on the slim margin left after covering the cost of goods. The September quarter delivered a surge in the first metric, with revenue more than tripling from a year ago, while the second remained stubbornly thin.
The numbers show a business in high gear, but not yet a profitable one. Revenue hit ₹82.8 crore, up 171% from last year and 134% from the prior quarter. Net profit was ₹0.96 crore, a recovery from last quarter's loss. Yet the net profit margin was just 1.2%, unchanged from a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 30.57
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 39.96
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 61.60
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 35.44
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 82.78
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.35
- Profit (₹ Cr), Q3 FY26 (Dec 2025): -0.30
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.04
- Profit (₹ Cr), Q1 FY27 (Jun 2026): -0.43
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.96
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 30.57
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 39.96
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 61.60
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 35.44
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 82.78
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.35
- Profit (₹ Cr), Q3 FY26 (Dec 2025): -0.30
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.04
- Profit (₹ Cr), Q1 FY27 (Jun 2026): -0.43
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.96
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 1.2%
- Net Profit Margin, Q3 FY26 (Dec 2025): -0.8%
- Net Profit Margin, Q4 FY26 (Mar 2026): 0.1%
- Net Profit Margin, Q1 FY27 (Jun 2026): -1.2%
- Net Profit Margin, Q2 FY27 (Sep 2026): 1.2%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 82.78 | 35.44 |
| Profit (₹ Cr) | 0.96 | -0.43 |
| Net Profit Margin | 1.2% | -1.2% |
Why the profit didn't keep pace
A look at the cost structure reveals the core challenge. Purchases of stock-in-trade consumed 96.7% of revenue, according to a scanx.trade report. This left almost no room for error. The move from loss to profit was driven not by operating leverage, but by a five-fold jump in other income to ₹1.9 crore. Flashfinance.news noted that all pre-tax profit came from this line.
The cash cost of growth
Funding this sales burst strained the balance sheet. The company reported a ₹10.7 crore operating cash outflow for the first half, as per multibagg.ai. Inventories and other current assets swelled, while cash reserves dwindled to ₹0.85 crore. To bridge the gap, Tai Industries raised ₹4.2 crore in term loans.
This working capital intensity is a sector-wide reality. A Trading & Distributors Sector Outlook from October 2026 notes the industry faces structurally thin margins and rising financing costs, which limit profitability even when volumes grow.
Live Chart
· TAIIND
(BSE)
ISIN: INE358D01018
Key Points
- Revenue surged 171% year-on-year to ₹82.8 crore, marking a sharp recovery from a volatile sequence of quarters.
- Profitability remained minimal, with a net margin of 1.2%, as the cost of goods sold consumed nearly all revenue.
- The return to profit was significantly aided by other income, while the core trading business continued to operate at a loss.
- Growth consumed cash, with a ₹10.7 crore operating outflow in H1 FY27 forcing the company to raise debt to fund working capital.
Hexa Perspective
The quarter confirms Tai Industries operates in the toughest part of the distribution chain, where high turnover does not guarantee healthy earnings. The revenue rebound is clear, but the 1.2% margin offers no buffer against shocks. With cash flow deeply negative and reliant on borrowing, the sustainability of this growth model is in question. Investors are left weighing a top-line recovery against a business model that struggles to convert sales into cash or meaningful profit.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.