Silicon Rental Solutions (SRSOLTD) Q2 FY27 Profit Jumps 40% Despite Revenue Decline
The IT rental firm posted a 40% jump in Q2 FY27 profit on a leaner business mix, even as revenue fell 23% year-on-year.
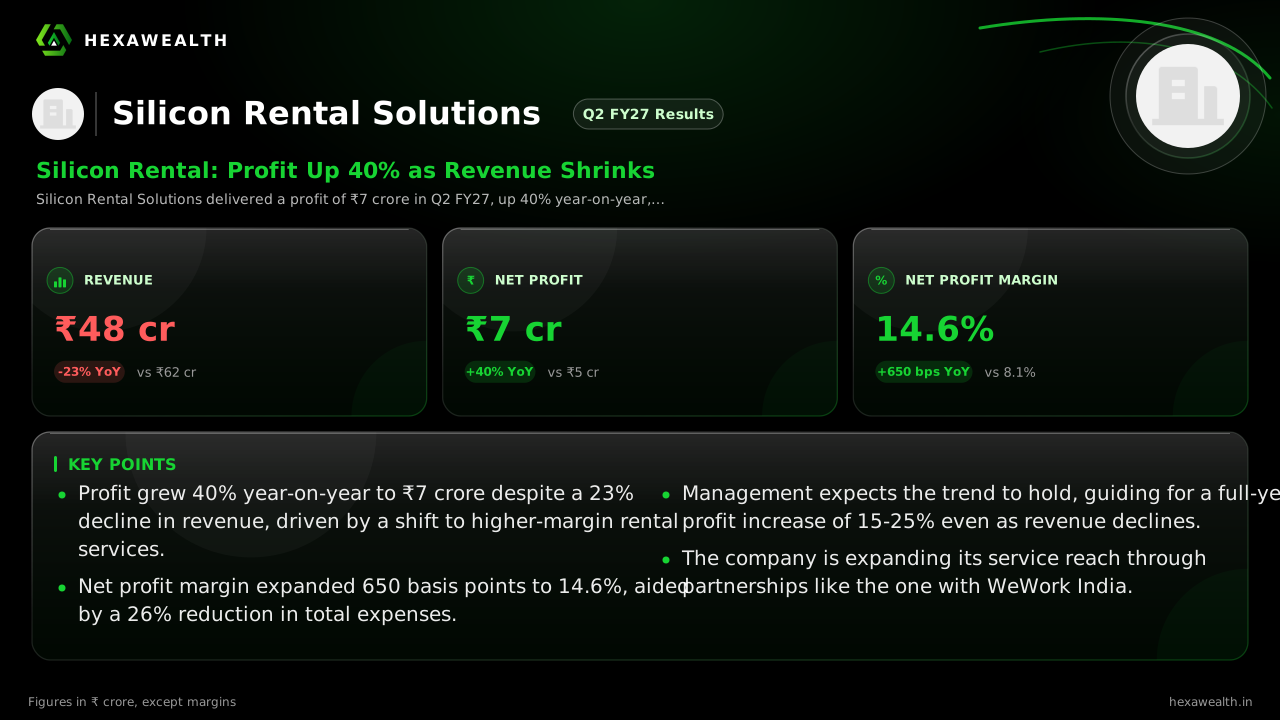
Silicon Rental Solutions delivered a profit of ₹7 crore in Q2 FY27, up 40% year-on-year, despite a 23% drop in revenue. The margin expansion reflects a strategic shift toward higher-margin rental services.
For a company that rents out IT hardware, the story is usually told in revenue growth. Silicon Rental Solutions flipped that script this quarter, delivering a 40% jump in profit on a 23% smaller top line. The shift reveals a business choosing margin over volume.
The numbers show a clear trade-off. Revenue fell to ₹48 crore from ₹62 crore a year ago. Yet, profit rose to ₹7 crore, and the net profit margin expanded sharply to 14.6%, up 650 basis points. Sequentially, profit also grew while revenue softened.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 55.0
- Revenue (₹ Cr), Q4 FY25: 47.0
- Revenue (₹ Cr), Q2 FY26: 62.0
- Revenue (₹ Cr), Q4 FY26: 52.0
- Revenue (₹ Cr), Q2 FY27: 48.0
- Profit (₹ Cr), Q2 FY25: 7.0
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 5.0
- Profit (₹ Cr), Q4 FY26: 6.0
- Profit (₹ Cr), Q2 FY27: 7.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 55.0
- Revenue (₹ Cr), Q4 FY25: 47.0
- Revenue (₹ Cr), Q2 FY26: 62.0
- Revenue (₹ Cr), Q4 FY26: 52.0
- Revenue (₹ Cr), Q2 FY27: 48.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 7.0
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 5.0
- Profit (₹ Cr), Q4 FY26: 6.0
- Profit (₹ Cr), Q2 FY27: 7.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 12.7
- Net Profit Margin (%), Q4 FY25: 12.8
- Net Profit Margin (%), Q2 FY26: 8.1
- Net Profit Margin (%), Q4 FY26: 11.5
- Net Profit Margin (%), Q2 FY27: 14.6
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 48.0YoY -23% | 62.0 |
| Profit (₹ Cr) | 7.0YoY +40% | 5.0 |
| Net Profit Margin (%) | 14.6YoY +80% | 8.1 |
The margin engine behind the profit
The profit surge was powered by a deliberate business mix change. According to analysis from mcapital.in, the company is shifting from low-margin trading or sales of equipment to higher-margin rental services. This pivot allowed profit to grow even as the top line contracted.
Costs fell in lockstep with the revenue decline. Total expenses dropped 26% year-on-year, and depreciation fell 14%. This suggests better asset utilization and a leaner cost structure, amplifying the margin gains from the service mix shift.
A strategy set to continue
Management's guidance, noted by mcapital.in, points to this being a sustained shift, not a one-quarter event. The outlook suggests a full-year revenue decline of 10-15% but a net profit increase of 15-25%. The focus is squarely on profitability.
Live Chart
· SRSOLTD
(BSE)
ISIN: INE0MNV01014
New partnerships, like the three-year deal with WeWork India to offer rental services to its members, support this higher-margin growth path. It expands reach without the capital intensity of a sales-driven model.
Key Points
- Profit grew 40% year-on-year to ₹7 crore despite a 23% decline in revenue, driven by a shift to higher-margin rental services.
- Net profit margin expanded 650 basis points to 14.6%, aided by a 26% reduction in total expenses.
- Management expects the trend to hold, guiding for a full-year profit increase of 15-25% even as revenue declines.
- The company is expanding its service reach through partnerships like the one with WeWork India.
Hexa Perspective
The quarter marks a clear strategic pivot. Silicon Rental is demonstrating it can generate more earnings from less revenue by optimizing its business mix and cost base. The market will now judge the company on the sustainability and quality of these profits.
The guidance implies investors should value the margin expansion over top-line growth in the near term. The key test will be whether this profitable, asset-light service model can scale without reigniting the cost base or facing renewed competitive pressure.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.