Times Green Energy (TIMESGREEN) Q2 FY27 Profit Triples as Revenue Crashes 70%
Times Green Energy's Q2 FY27 saw a 70% revenue plunge, yet net profit tripled sequentially, highlighting a business in severe contraction.
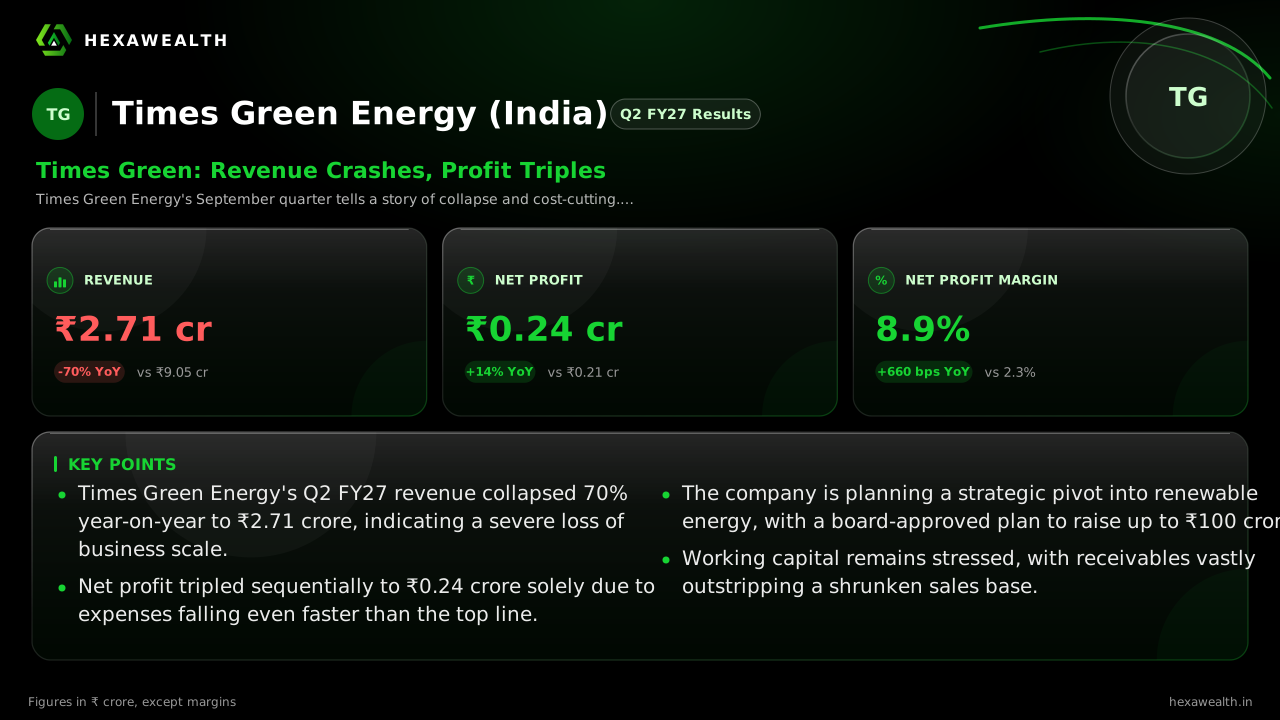
Times Green Energy's September quarter tells a story of collapse and cost-cutting. Revenue fell 70% year-on-year, but net profit tripled from the previous quarter as expenses fell even faster.
For Times Green Energy, the September quarter was a story of a business shrinking to its barest bones. The company, which operates in organic fertilizers and hygiene products, reported a severe contraction in scale, with revenue plunging 70% from a year ago. Yet, a drastic cut in expenses allowed it to post a net profit that tripled from the prior quarter, creating a paradox of profitability amid collapse.
The numbers lay out the stark reality. Revenue for Q2 FY27 was just ₹2.71 crore, down from ₹9.05 crore a year earlier and ₹13.01 crore in the March quarter. Net profit, however, rose to ₹0.24 crore, up 14% year-on-year and a 300% jump sequentially. This pushed the net profit margin to 8.9%, a sharp 840 basis point improvement from the previous quarter.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
- Revenue (₹ Cr.), Q2 FY25: 10.06
- Revenue (₹ Cr.), Q4 FY25: 29.98
- Revenue (₹ Cr.), Q2 FY26: 9.05
- Revenue (₹ Cr.), Q4 FY26: 13.01
- Revenue (₹ Cr.), Q2 FY27: 2.71
- Profit (₹ Cr.), Q2 FY25: 0.16
- Profit (₹ Cr.), Q4 FY25: 0.22
- Profit (₹ Cr.), Q2 FY26: 0.21
- Profit (₹ Cr.), Q4 FY26: 0.06
- Profit (₹ Cr.), Q2 FY27: 0.24
Revenue (₹ Cr.)
- Revenue (₹ Cr.), Q2 FY25: 10.06
- Revenue (₹ Cr.), Q4 FY25: 29.98
- Revenue (₹ Cr.), Q2 FY26: 9.05
- Revenue (₹ Cr.), Q4 FY26: 13.01
- Revenue (₹ Cr.), Q2 FY27: 2.71
Profit (₹ Cr.)
- Profit (₹ Cr.), Q2 FY25: 0.16
- Profit (₹ Cr.), Q4 FY25: 0.22
- Profit (₹ Cr.), Q2 FY26: 0.21
- Profit (₹ Cr.), Q4 FY26: 0.06
- Profit (₹ Cr.), Q2 FY27: 0.24
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 1.6
- Net Profit Margin (%), Q4 FY25: 0.7
- Net Profit Margin (%), Q2 FY26: 2.3
- Net Profit Margin (%), Q4 FY26: 0.5
- Net Profit Margin (%), Q2 FY27: 8.9
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr.) | 2.71YoY -70% | 9.05 |
| Profit (₹ Cr.) | 0.24YoY +14% | 0.21 |
| Net Profit Margin (%) | 8.9YoY +287% | 2.3 |
The cost-cut mirage
The profit jump was not a sign of health but of deep retrenchment. Analysis by mcapital.in points to a sharp drop in trading volumes for its agri-produce business as the primary driver of the revenue crash. As sales evaporated, the company slashed total expenses by 80% from the March quarter. Interest costs also fell by 20%, providing a minor lift. The result is a business running on fumes, where profitability is an artifact of cutting costs faster than sales disappear.
A pivot from distress
Facing this collapse, the company is attempting a strategic shift. In August 2026, its board approved altering its Memorandum of Association to formally enter wind, solar, and hybrid renewable energy projects, as reported by multibagg.ai. It also proposed raising up to ₹100 crore, signaling a potential pivot away from its struggling core operations. This move is a response to distress, not an extension of existing strength.
The working capital anchor
Even as the business shrinks, a legacy issue persists. Analysis by mcapital.in notes that trade receivables, while down from March, remained high at ₹10.21 crore against annualized sales of roughly ₹5.4 crore. This implies extremely stretched debtor days, tying up precious capital in a vanishing business and creating a persistent drag.
Live Chart
· TIMESGREEN
(BSE)
ISIN: INE0B6101012
Key Points
- Times Green Energy's Q2 FY27 revenue collapsed 70% year-on-year to ₹2.71 crore, indicating a severe loss of business scale.
- Net profit tripled sequentially to ₹0.24 crore solely due to expenses falling even faster than the top line.
- The company is planning a strategic pivot into renewable energy, with a board-approved plan to raise up to ₹100 crore.
- Working capital remains stressed, with receivables vastly outstripping a shrunken sales base.
Hexa Perspective
The Q2 results underscore a business in retreat, where the soaring margin is a symptom of collapse, not efficiency. The elevated P/E of 188.5, a 235% premium to the industry, prices in a promised transformation into renewables that is yet to begin. For the premium to hold, the pivot must quickly transition from a clause in the MoA to concrete projects and cash flows. Investors are betting on a rebirth, but the next few quarters must show whether this is a viable new path or merely a retreat from a failing model.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.