KMS Medisurgi (KMSMEDI) Q2 FY27 Posts Q2 Loss as Costs Outpace Sales Recovery
The surgical equipment maker saw a quarterly loss of ₹0.22 crore as higher employee costs and depreciation squeezed margins, with auditors flagging accounting issues.
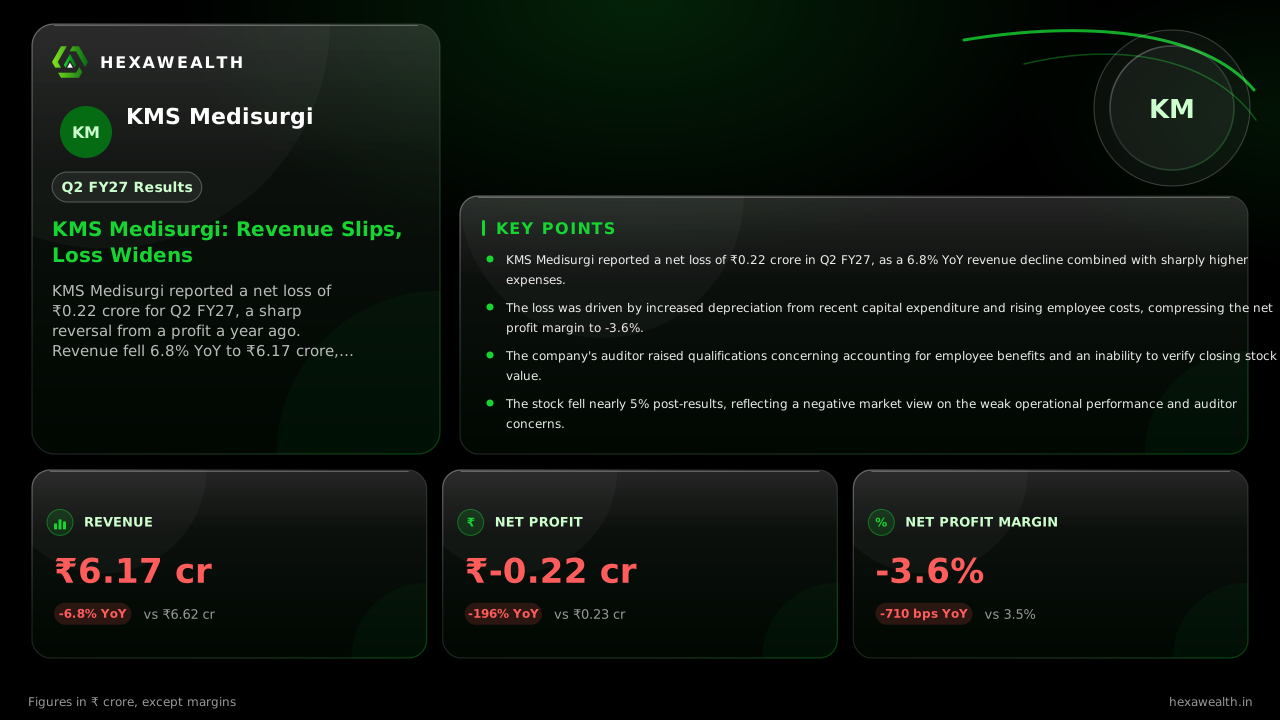
KMS Medisurgi reported a net loss of ₹0.22 crore for Q2 FY27, a sharp reversal from a profit a year ago. Revenue fell 6.8% YoY to ₹6.17 crore, while total expenses rose, compressing margins. The company's auditor raised concerns over employee benefits and stock valuation.
For a small surgical equipment maker, the challenge is balancing investment in new capacity with the reality of current demand. KMS Medisurgi's second quarter shows that tension clearly, as a modest sales recovery was overwhelmed by rising fixed costs and accounting uncertainties.
The numbers tell a story of pressure on both ends. Revenue of ₹6.17 crore was down 6.8% from a year earlier, though it improved 10.4% sequentially. The bottom line swung to a loss of ₹0.22 crore, a stark contrast to the ₹0.23 crore profit in Q2 FY26. This pushed the net profit margin to -3.6%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 7.81
- Revenue (₹ Cr), Q4 FY25: 6.12
- Revenue (₹ Cr), Q2 FY26: 6.62
- Revenue (₹ Cr), Q4 FY26: 5.59
- Revenue (₹ Cr), Q2 FY27: 6.17
- Profit (₹ Cr), Q2 FY25: 0.08
- Profit (₹ Cr), Q4 FY25: 0.36
- Profit (₹ Cr), Q2 FY26: 0.23
- Profit (₹ Cr), Q4 FY26: 0.01
- Profit (₹ Cr), Q2 FY27: -0.22
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 7.81
- Revenue (₹ Cr), Q4 FY25: 6.12
- Revenue (₹ Cr), Q2 FY26: 6.62
- Revenue (₹ Cr), Q4 FY26: 5.59
- Revenue (₹ Cr), Q2 FY27: 6.17
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.08
- Profit (₹ Cr), Q4 FY25: 0.36
- Profit (₹ Cr), Q2 FY26: 0.23
- Profit (₹ Cr), Q4 FY26: 0.01
- Profit (₹ Cr), Q2 FY27: -0.22
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 1.0
- Net Profit Margin (%), Q4 FY25: 5.9
- Net Profit Margin (%), Q2 FY26: 3.5
- Net Profit Margin (%), Q4 FY26: 0.2
- Net Profit Margin (%), Q2 FY27: -3.6
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 6.17YoY -6.8% | 6.62 |
| Profit (₹ Cr) | -0.22YoY -196% | 0.23 |
| Net Profit Margin (%) | -3.6YoY -203% | 3.5 |
The Cost of Unused Capacity
The primary driver of the loss was a 16.1% quarter-on-quarter jump in total expenses, far outpacing the 10.4% revenue increase. Research from Scanx.trade points to a significant rise in depreciation, up 77% in FY26 due to capital additions of ₹1.72 crore in plant and machinery. This suggests the company is bearing the cost of a new coating line, commissioned last year, before it has generated meaningful sales growth.
Employee costs also rose, adding to the margin squeeze. Meanwhile, the company's auditor, H H Dedhia & Associates, qualified its review report. As noted by ForgeUp and Stockwatch.live, the auditor flagged a departure from accounting standards on post-employment benefits and could not ascertain the value of closing stock pending reconciliation.
A Market Awash with Imports
The revenue decline points to a tough competitive environment. India's medical device market remains heavily import-dependent, with low-cost products from ASEAN nations creating pricing pressure. This backdrop makes it difficult for small domestic manufacturers like KMS Medisurgi to gain traction, even with new capacity.
Live Chart
· KMSMEDI
(BSE)
ISIN: INE870V01014
Management has not provided specific FY27 guidance, but the market reaction was clear. Analysis from MCapital categorized the results as having a 'very negative' impact, noting the stock fell nearly 5% following the announcement. The absence of institutional investors, with promoters holding 74.42% of the stake, leaves the stock exposed to sharp moves on operational setbacks.
Key Points
- KMS Medisurgi reported a net loss of ₹0.22 crore in Q2 FY27, as a 6.8% YoY revenue decline combined with sharply higher expenses.
- The loss was driven by increased depreciation from recent capital expenditure and rising employee costs, compressing the net profit margin to -3.6%.
- The company's auditor raised qualifications concerning accounting for employee benefits and an inability to verify closing stock value.
- The stock fell nearly 5% post-results, reflecting a negative market view on the weak operational performance and auditor concerns.
Hexa Perspective
The quarter underscores the operational risk of expanding capacity ahead of demand. The new coating line, intended to nearly double output, is now a fixed cost drag with sales yet to respond. The auditor's qualifications add a layer of financial reporting uncertainty that investors typically discount heavily.
The path forward hinges on utilizing that new capacity. The company's plan to launch adhesive tapes for automotive and electrical uses, mentioned in its annual report, remains a concept without a confirmed launch or customer. Until sales can rise to absorb the higher depreciation, profitability will remain under pressure. For now, the story is one of investment waiting for a market answer.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.