Amkay Products (AMKAY) Q2 FY27 Profit Crashes 88% as Costs Soar
The healthcare manufacturer's profit collapsed despite flat revenue, as material costs surged and short-term borrowings tripled to fund working capital.
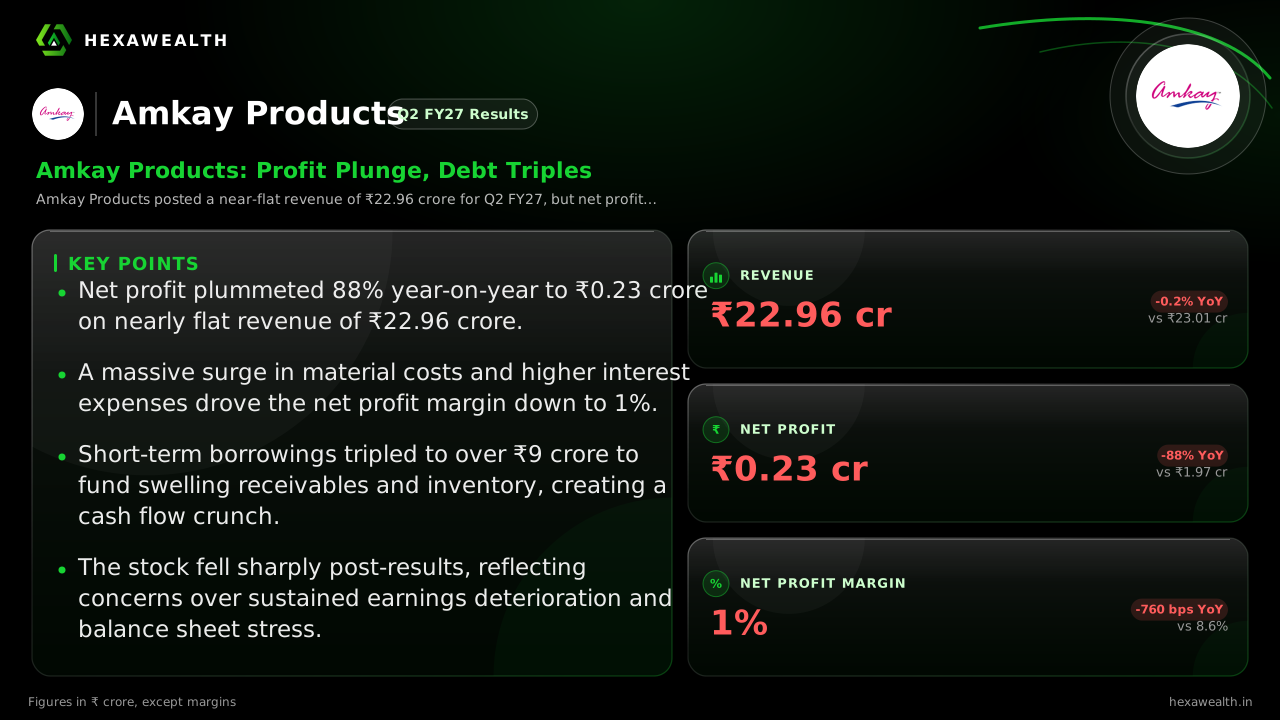
Amkay Products posted a near-flat revenue of ₹22.96 crore for Q2 FY27, but net profit plunged 88% year-on-year to ₹0.23 crore. A sharp rise in material consumption and a tripling of short-term debt to fund receivables and inventory crippled profitability.
For a manufacturer of medical disposables, holding sales steady should protect the bottom line. Amkay Products kept revenue flat year-on-year at ₹22.96 crore in the September quarter, but its profit collapsed by 88%. The gap tells a story of costs running far ahead of the top line.
The numbers show a business under severe pressure. Net profit margin shrank to just 1%, down from 8.6% a year ago. While other income provided a ₹0.81 crore lift from investment sales, it was no match for a 13% year-on-year jump in total expenses.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 17.84
- Revenue (₹ Cr), Q4 FY25: 20.55
- Revenue (₹ Cr), Q2 FY26: 23.01
- Revenue (₹ Cr), Q4 FY26: 19.02
- Revenue (₹ Cr), Q2 FY27: 22.96
- Profit (₹ Cr), Q2 FY25: 1.83
- Profit (₹ Cr), Q4 FY25: 1.51
- Profit (₹ Cr), Q2 FY26: 1.97
- Profit (₹ Cr), Q4 FY26: 0.34
- Profit (₹ Cr), Q2 FY27: 0.23
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 17.84
- Revenue (₹ Cr), Q4 FY25: 20.55
- Revenue (₹ Cr), Q2 FY26: 23.01
- Revenue (₹ Cr), Q4 FY26: 19.02
- Revenue (₹ Cr), Q2 FY27: 22.96
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 1.83
- Profit (₹ Cr), Q4 FY25: 1.51
- Profit (₹ Cr), Q2 FY26: 1.97
- Profit (₹ Cr), Q4 FY26: 0.34
- Profit (₹ Cr), Q2 FY27: 0.23
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 10.3
- Net Profit Margin (%), Q4 FY25: 7.3
- Net Profit Margin (%), Q2 FY26: 8.6
- Net Profit Margin (%), Q4 FY26: 1.8
- Net Profit Margin (%), Q2 FY27: 1.0
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 22.96YoY -0.2% | 23.01 |
| Profit (₹ Cr) | 0.23YoY -88% | 1.97 |
| Net Profit Margin (%) | 1.0YoY -88% | 8.6 |
The cost surge that erased profits
Material consumption more than doubled year-on-year for the half-year, reports from Reports Radar indicate. This raw material inflation, alongside rising depreciation and a 50% quarter-on-quarter jump in interest costs, drove total expenses up by 24% from the March quarter. With revenue growth unable to keep pace, profitability evaporated.
A balance sheet now funding the squeeze
Higher costs are only half the strain. The company's short-term borrowings tripled to ₹9.14 crore between March and September 2026, as per analysis from mcapital.in. This debt funded a sharp increase in trade receivables and inventory, turning operating cash flow deeply negative at ₹2.71 crore for the half-year. Profit is not converting to cash.
The market's read was clear. The stock fell 5.7% in the days following the November 14 results announcement, according to MarketsMojo. With net profit annualizing to a fraction of last year's figure, a mcapital.in estimate suggests the market cap could see a 12-18% de-rating from current levels.
Live Chart
· AMKAY
(BSE)
ISIN: INE0QSB01016
Key Points
- Net profit plummeted 88% year-on-year to ₹0.23 crore on nearly flat revenue of ₹22.96 crore.
- A massive surge in material costs and higher interest expenses drove the net profit margin down to 1%.
- Short-term borrowings tripled to over ₹9 crore to fund swelling receivables and inventory, creating a cash flow crunch.
- The stock fell sharply post-results, reflecting concerns over sustained earnings deterioration and balance sheet stress.
Hexa Perspective
The quarter reveals a dual squeeze: input costs have broken away from sales, and the business is borrowing heavily to fund its own operations. For profitability to recover, Amkay needs either significant pricing power or a reversal in raw material costs, neither of which is evident.
The more immediate concern is liquidity. Until the company reins in its working capital cycle, the rising interest burden will continue to pressure the thin profit margin. Investors are weighing whether this is a cyclical cost spike or a structural shift in the company's economics.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.