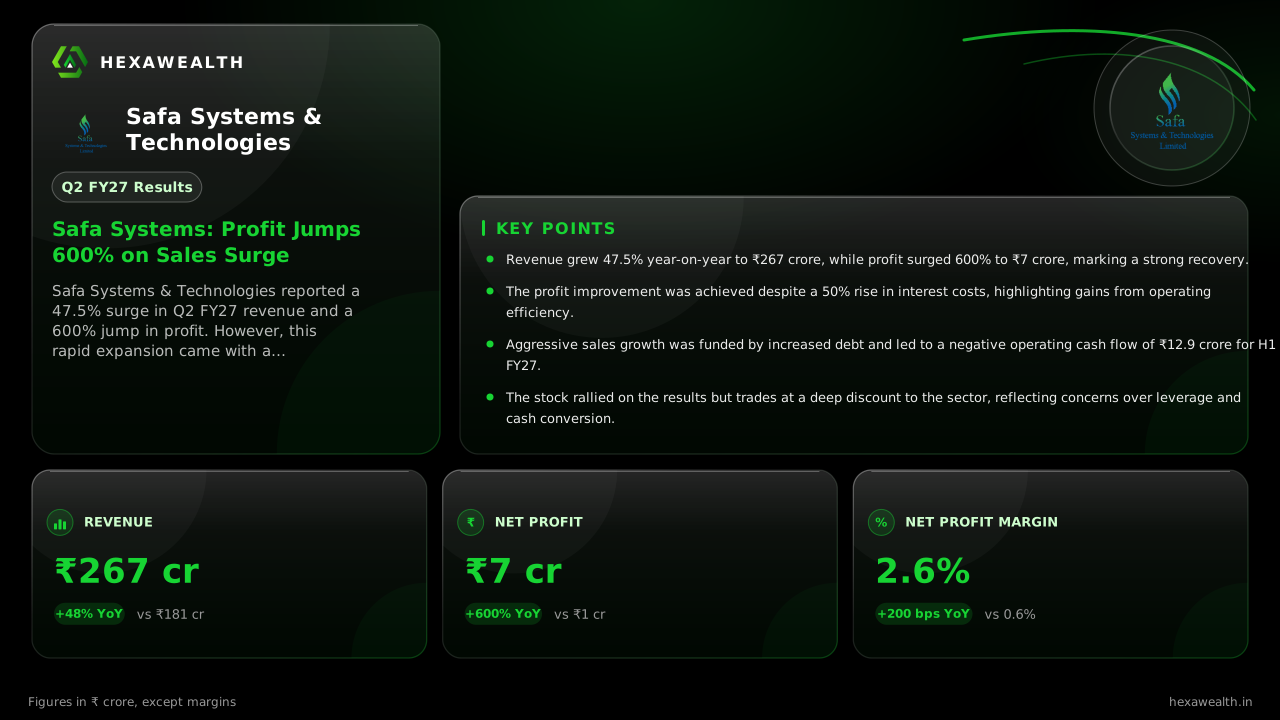
Safa Systems (SSTL) Q2 FY27 Profit Jumps 600% as Revenue Surges 47.5%
The Kerala-based distributor posted a six-fold profit rise on strong sales, but the growth was fueled by a sharp rise in debt and receivables.
Safa Systems & Technologies reported a 47.5% surge in Q2 FY27 revenue and a 600% jump in profit. However, this rapid expansion came with a significant increase in borrowings and a negative operating cash flow.
For a distributor like Safa Systems, growth is a double-edged sword: higher sales demand more working capital, and the cost of that capital can quickly eat into thin margins. The company's September quarter shows that edge in sharp relief, with a spectacular profit jump built on a foundation of rising debt.
Revenue climbed to ₹267 crore, a 47.5% leap from a weak year-ago quarter. Profit soared six-fold to ₹7 crore, lifting the net margin to 2.6% from just 0.6% a year earlier. The trend over the past five quarters shows a clear recovery from a low base.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
- Revenue (₹ Cr.), Sep 2024: 286.0
- Revenue (₹ Cr.), Mar 2025: 233.0
- Revenue (₹ Cr.), Sep 2025: 181.0
- Revenue (₹ Cr.), Mar 2026: 252.0
- Revenue (₹ Cr.), Sep 2026: 267.0
- Profit (₹ Cr.), Sep 2024: 2.0
- Profit (₹ Cr.), Mar 2025: 2.0
- Profit (₹ Cr.), Sep 2025: 1.0
- Profit (₹ Cr.), Mar 2026: 4.0
- Profit (₹ Cr.), Sep 2026: 7.0
Revenue (₹ Cr.)
- Revenue (₹ Cr.), Sep 2024: 286.0
- Revenue (₹ Cr.), Mar 2025: 233.0
- Revenue (₹ Cr.), Sep 2025: 181.0
- Revenue (₹ Cr.), Mar 2026: 252.0
- Revenue (₹ Cr.), Sep 2026: 267.0
Profit (₹ Cr.)
- Profit (₹ Cr.), Sep 2024: 2.0
- Profit (₹ Cr.), Mar 2025: 2.0
- Profit (₹ Cr.), Sep 2025: 1.0
- Profit (₹ Cr.), Mar 2026: 4.0
- Profit (₹ Cr.), Sep 2026: 7.0
Net Profit Margin
- Net Profit Margin, Sep 2024: 0.7%
- Net Profit Margin, Mar 2025: 0.9%
- Net Profit Margin, Sep 2025: 0.6%
- Net Profit Margin, Mar 2026: 1.6%
- Net Profit Margin, Sep 2026: 2.6%
| Metric | CurrentSep 2026 | PreviousMar 2026 |
|---|---|---|
| Revenue (₹ Cr.) | 267.0 | 252.0 |
| Profit (₹ Cr.) | 7.0 | 4.0 |
| Net Profit Margin | 2.6% | 1.6% |
The cost of a cash crunch
The profit surge came from operating leverage, as total expenses grew slower than sales. Yet, the business model's strain is visible in the cash flow. According to a report by ScanX, operating cash flow turned negative at ₹12.9 crore for the half-year.
This was driven by a massive ₹31.5 crore increase in trade receivables, as reported by ScanX. The company funded this working capital spike with more debt, pushing total borrowings to ₹74.6 crore in September from ₹59.5 crore in March.
A market split on sentiment
The stock jumped over 15% on the results day, as tracked by MarketsMojo, reflecting investor cheer for the headline profit growth. However, the company trades at a significant discount, with a P/E of 10.5 against an industry average of 44.1.
Live Chart
· SSTL
(BSE)
ISIN: INE0JNA01014
This gap hints at the market's caution over the balance sheet. With zero institutional holding, the stock's moves are driven by retail and promoter sentiment, which remains positive but sensitive to liquidity.
Key Points
- Revenue grew 47.5% year-on-year to ₹267 crore, while profit surged 600% to ₹7 crore, marking a strong recovery.
- The profit improvement was achieved despite a 50% rise in interest costs, highlighting gains from operating efficiency.
- Aggressive sales growth was funded by increased debt and led to a negative operating cash flow of ₹12.9 crore for H1 FY27.
- The stock rallied on the results but trades at a deep discount to the sector, reflecting concerns over leverage and cash conversion.
Hexa Perspective
This quarter demonstrates the potent operating leverage in Safa Systems' wholesale model when sales accelerate. The 200 basis-point margin expansion is meaningful, but its sustainability is directly tied to the company's ability to manage its working capital cycle.
The receivables bulge suggests either extended credit to drive sales or collection delays. If this cycle does not tighten, the need for incremental debt will persist, keeping finance costs high and pressuring the very margins that just expanded. The next few quarters will test whether this growth is efficiently funded or merely borrowed.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.