Amkay Products (AMKAY) Q4 FY26 Profit Crashes 78% as Costs and Mix Bite
The healthcare supplier's Q4 FY26 profit fell sharply despite higher annual sales, as a shift to low-margin traded goods and rising costs eroded profitability.
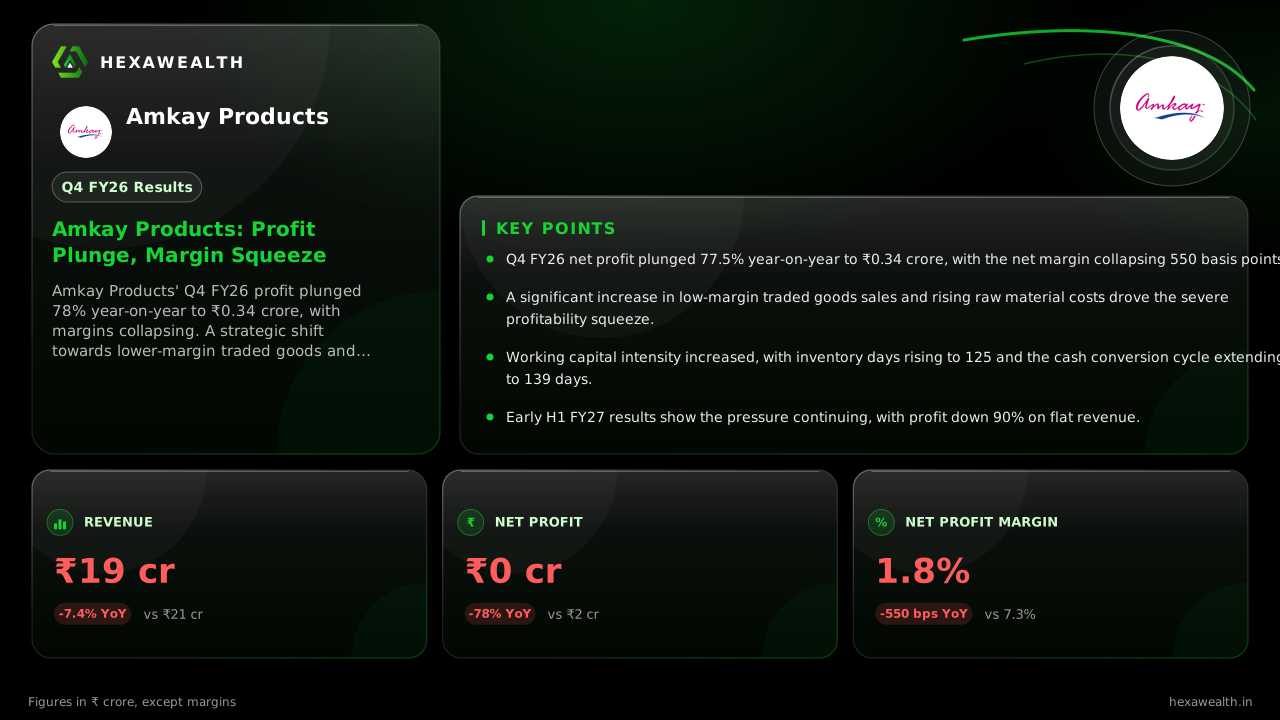
Amkay Products' Q4 FY26 profit plunged 78% year-on-year to ₹0.34 crore, with margins collapsing. A strategic shift towards lower-margin traded goods and higher raw material costs drove the sharp decline, overshadowing full-year revenue growth.
For Amkay Products, a supplier of everyday medical disposables, the final quarter of FY26 revealed a painful trade-off. The company grew its annual sales but saw profitability evaporate, as a strategic pivot and cost pressures converged.
The numbers show a steep sequential decline. Revenue fell 17% from the previous quarter to ₹19.02 crore. Profit collapsed 83% to just ₹0.34 crore, dragging the net profit margin down to 1.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 16.69
- Revenue (₹ Cr), Q2 FY25: 17.84
- Revenue (₹ Cr), Q4 FY25: 20.55
- Revenue (₹ Cr), Q2 FY26: 23.01
- Revenue (₹ Cr), Q4 FY26: 19.02
- Profit (₹ Cr), Q4 FY24: 1.33
- Profit (₹ Cr), Q2 FY25: 1.83
- Profit (₹ Cr), Q4 FY25: 1.51
- Profit (₹ Cr), Q2 FY26: 1.97
- Profit (₹ Cr), Q4 FY26: 0.34
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 16.69
- Revenue (₹ Cr), Q2 FY25: 17.84
- Revenue (₹ Cr), Q4 FY25: 20.55
- Revenue (₹ Cr), Q2 FY26: 23.01
- Revenue (₹ Cr), Q4 FY26: 19.02
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 1.33
- Profit (₹ Cr), Q2 FY25: 1.83
- Profit (₹ Cr), Q4 FY25: 1.51
- Profit (₹ Cr), Q2 FY26: 1.97
- Profit (₹ Cr), Q4 FY26: 0.34
Net Profit Margin
- Net Profit Margin, Q4 FY24: 8.0%
- Net Profit Margin, Q2 FY25: 10.3%
- Net Profit Margin, Q4 FY25: 7.3%
- Net Profit Margin, Q2 FY26: 8.6%
- Net Profit Margin, Q4 FY26: 1.8%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 19.02YoY -7.4% | 20.55 |
| Profit (₹ Cr) | 0.34YoY -77% | 1.51 |
| Net Profit Margin | 1.8%YoY -75% | 7.3% |
The Shift to Thin-Margin Sales
The core issue is a changing business mix. According to analysis from Newboard, traded goods—products bought and resold—earn much thinner margins than items made in-house. Their share of sales rose sharply in FY26, which the company cites as a main reason profit fell while sales grew. This structural shift diluted overall margins.
Compounding this, raw material costs surged. A MarketsMojo alert noted that raw material inflation was a key driver behind a massive 88% profit crash in the subsequent half-year. Competitive pricing pressure in a crowded market for simple disposables left little room to pass these costs on.
A Weaker Cushion and Strained Capital
Other income, which provided a cushion in past years, halved in FY26 to about ₹0.7 crore according to the annual report. This removed a support for the bottom line. Meanwhile, working capital efficiency deteriorated.
Live Chart
· AMKAY
(BSE)
ISIN: INE0QSB01016
Inventory days stretched to 125 in FY26, up from 113 the year before. The cash conversion cycle extended to 139 days, indicating more capital is tied up in the business. While annual operating cash flow was positive at ₹1.18 crore, it represented only 31% of the operating profit.
The Path Ahead Looks Challenging
The strain continued into the new fiscal year. For H1 FY27, Amkay reported flat revenue of ₹23 crore but a 90% plunge in net profit to ₹0.23 crore, as per Alfafinder. The operating margin contracted to just 1.7%, suggesting the margin pressure is persistent.
Management is focusing on adding distributors in underserved markets, as noted in the FY26 annual report. A capacity expansion funded by IPO proceeds is also on track for Q4 FY27. However, in a market where price often decides sales, restoring profitability remains the critical test.
Key Points
- Q4 FY26 net profit plunged 77.5% year-on-year to ₹0.34 crore, with the net margin collapsing 550 basis points.
- A significant increase in low-margin traded goods sales and rising raw material costs drove the severe profitability squeeze.
- Working capital intensity increased, with inventory days rising to 125 and the cash conversion cycle extending to 139 days.
- Early H1 FY27 results show the pressure continuing, with profit down 90% on flat revenue.
Hexa Perspective
Amkay's quarter underscores the vulnerability of a distributor-model pivot without pricing power. The margin compression from traded goods is structural, not cyclical, and raw material inflation adds a persistent headwind. The sharply extended cash conversion cycle signals rising capital needs, which the IPO-funded working capital was meant to address. With profitability at multi-quarter lows and H1 FY27 showing no respite, the turnaround hinges on reversing the margin dilution—a tough ask in a commodity-like market for medical disposables.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.