Silicon Rental Solutions (SRSOLTD) Q4 FY26 Profit Stalls Even as Revenue Climbs 11%
Silicon Rental Solutions posted higher annual revenue but flat quarterly profit, as a strategic shift toward rental services begins to reshape margins.
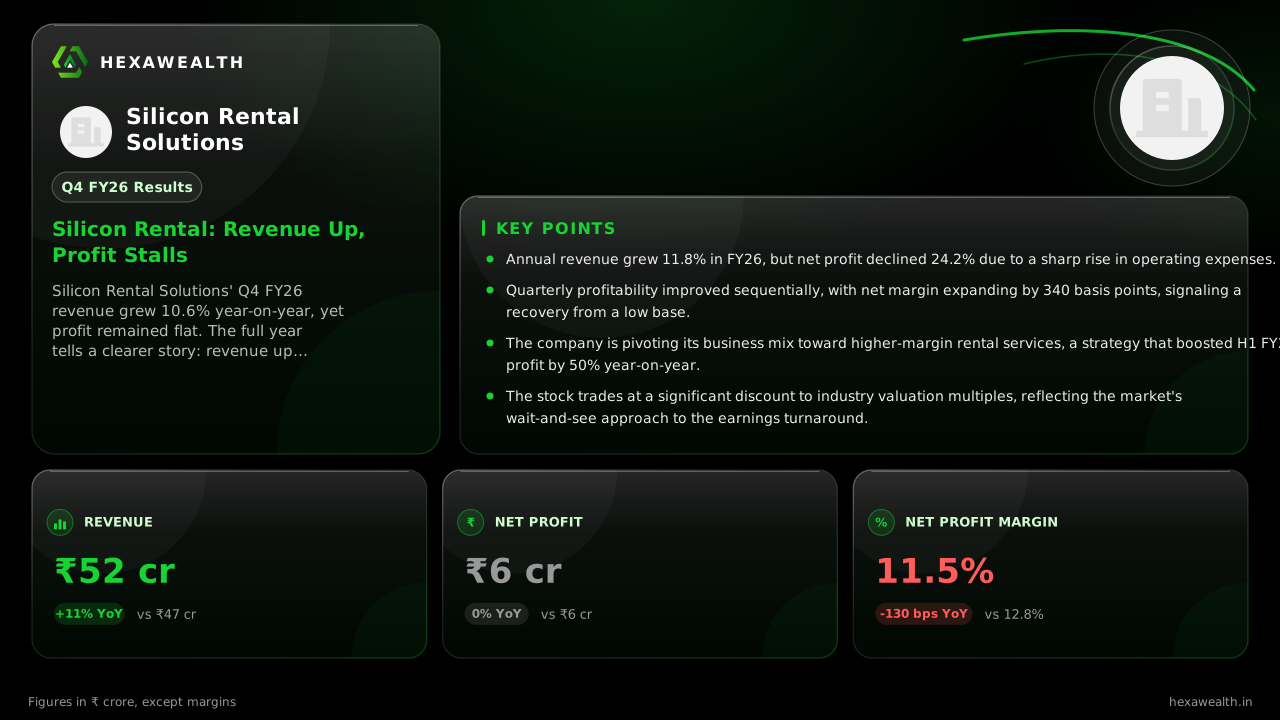
Silicon Rental Solutions' Q4 FY26 revenue grew 10.6% year-on-year, yet profit remained flat. The full year tells a clearer story: revenue up 11.8% but profit down 24.2%, squeezed by rising costs.
For an IT rental business, growth is measured not just in top-line expansion but in the quality of earnings from its asset base. Silicon Rental Solutions' latest quarter shows revenue climbing while profitability holds steady, a sign that a deliberate business mix change is underway.
The March quarter revenue of ₹52 crore was up 10.6% from a year ago, but profit stayed at ₹6 crore. Sequentially, revenue fell 16.1% from a strong September quarter, yet profit rose 20%. The full-year picture sharpens the contrast: FY26 revenue grew 11.8% to ₹114 crore, but net profit fell 24.2% to ₹10 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 39.0
- Revenue (₹ Cr), Q2 FY25: 55.0
- Revenue (₹ Cr), Q4 FY25: 47.0
- Revenue (₹ Cr), Q2 FY26: 62.0
- Revenue (₹ Cr), Q4 FY26: 52.0
- Profit (₹ Cr), Q4 FY24: 6.0
- Profit (₹ Cr), Q2 FY25: 7.0
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 5.0
- Profit (₹ Cr), Q4 FY26: 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 39.0
- Revenue (₹ Cr), Q2 FY25: 55.0
- Revenue (₹ Cr), Q4 FY25: 47.0
- Revenue (₹ Cr), Q2 FY26: 62.0
- Revenue (₹ Cr), Q4 FY26: 52.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 6.0
- Profit (₹ Cr), Q2 FY25: 7.0
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 5.0
- Profit (₹ Cr), Q4 FY26: 6.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY24: 15.4
- Net Profit Margin (%), Q2 FY25: 12.7
- Net Profit Margin (%), Q4 FY25: 12.8
- Net Profit Margin (%), Q2 FY26: 8.1
- Net Profit Margin (%), Q4 FY26: 11.5
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 52.0YoY +11% | 47.0 |
| Profit (₹ Cr) | 6.0YoY 0% | 6.0 |
| Net Profit Margin (%) | 11.5YoY -10% | 12.8 |
The Margin Squeeze and the Strategic Pivot
The annual profit decline points to a significant cost increase. Total expenses surged 79.7% in FY26, far outpacing revenue growth. This pressure is now easing as the company pivots its model. Reports from MCapital indicate a strategic shift away from lower-margin hardware trading toward higher-margin pure rental services.
This explains the improving margin trend within the year. The net profit margin recovered to 11.5% in Q4, up 340 basis points from the previous quarter. The shift is bearing fruit, with the company's subsequent H1 FY27 results showing a 50% jump in profit on lower revenue, as noted by the same source.
A Valuation Disconnect
The market appears to be weighing the near-term profit pressure against the long-term margin story. The stock trades at a P/E of 7.7, an 81% discount to the industry average of 40.8. This deep value gap reflects investor caution as the company navigates its transition.
Live Chart
· SRSOLTD
(BSE)
ISIN: INE0MNV01014
Management's focus for FY27, as highlighted by Univest, remains on consistent revenue growth and margin expansion. The early results from the mix shift suggest this priority is starting to translate into financial performance.
Key Points
- Annual revenue grew 11.8% in FY26, but net profit declined 24.2% due to a sharp rise in operating expenses.
- Quarterly profitability improved sequentially, with net margin expanding by 340 basis points, signaling a recovery from a low base.
- The company is pivoting its business mix toward higher-margin rental services, a strategy that boosted H1 FY27 profit by 50% year-on-year.
- The stock trades at a significant discount to industry valuation multiples, reflecting the market's wait-and-see approach to the earnings turnaround.
Hexa Perspective
The quarter underscores a transition phase. The five-year revenue CAGR of 46.7% against a flat profit trend reveals the cost of scaling. Now, the focus is squarely on earning quality.
The early success of the rental-mix shift, visible in the post-Q4 H1 numbers, suggests the margin recovery has legs. The key will be sustaining this quality of growth without a relapse into high-cost, low-margin sales. Investors are positioned for a rerating, but only if the margin trajectory holds firm through the next few quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.