Angel Fibers (ANGEL) Q4 FY26 Profit Evaporates as Costs and Debt Bite
The cotton spinner closed FY26 with a top-line gain but saw its Q4 net profit fall to zero, squeezed by high interest costs and thin operating margins.
Angel Fibers reported a 5.3% rise in FY26 revenue to ₹211.53 crore, but annual profit fell 30%. The March quarter saw net profit drop to zero, highlighting a persistent squeeze from finance costs and low margins.
For a cotton yarn spinner like Angel Fibers, the business lives on the spread between raw material costs and selling prices. The past year tested that spread, and the final quarter showed it breaking. The company ended FY26 with higher sales but saw its profitability collapse to zero in the March quarter.
The numbers tell a story of divergence. Annual revenue grew 5.3% to ₹211.53 crore, yet net profit fell 30.3% to ₹1.28 crore. The fourth quarter was worse: a 1% yearly sales increase to ₹101 crore delivered no bottom-line reward, with net profit falling from ₹2 crore a year ago to zero.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 95.0
- Revenue (₹ Cr), Q2 FY25: 101.0
- Revenue (₹ Cr), Q4 FY25: 100.0
- Revenue (₹ Cr), Q2 FY26: 110.0
- Revenue (₹ Cr), Q4 FY26: 101.0
- Profit (₹ Cr), Q4 FY24: 0.0
- Profit (₹ Cr), Q2 FY25: 0.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 0.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 95.0
- Revenue (₹ Cr), Q2 FY25: 101.0
- Revenue (₹ Cr), Q4 FY25: 100.0
- Revenue (₹ Cr), Q2 FY26: 110.0
- Revenue (₹ Cr), Q4 FY26: 101.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 0.0
- Profit (₹ Cr), Q2 FY25: 0.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 0.0
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 101.0YoY +1% | 100.0 |
| Profit (₹ Cr) | 0.0YoY -100% | 2.0 |
| Net Margin | 0.0%YoY -100% | 2.0% |
The squeeze from interest and costs
The immediate culprit was a doubling of quarterly interest expense. Finance costs rose to ₹2 crore from ₹1 crore in the previous quarter, according to the company's filings. This ate into an already thin operating profit of ₹4 crore. WinstonDaily notes the company's interest coverage ratio is a dangerous 0.7x, meaning profits barely cover the interest bill.
This pressure isn't new. Management cited declining profitability for the full year in their AGM statement. The business operates on wafer-thin margins, with operating margins around 1%, leaving no buffer when costs rise.
A brighter turn in the new year
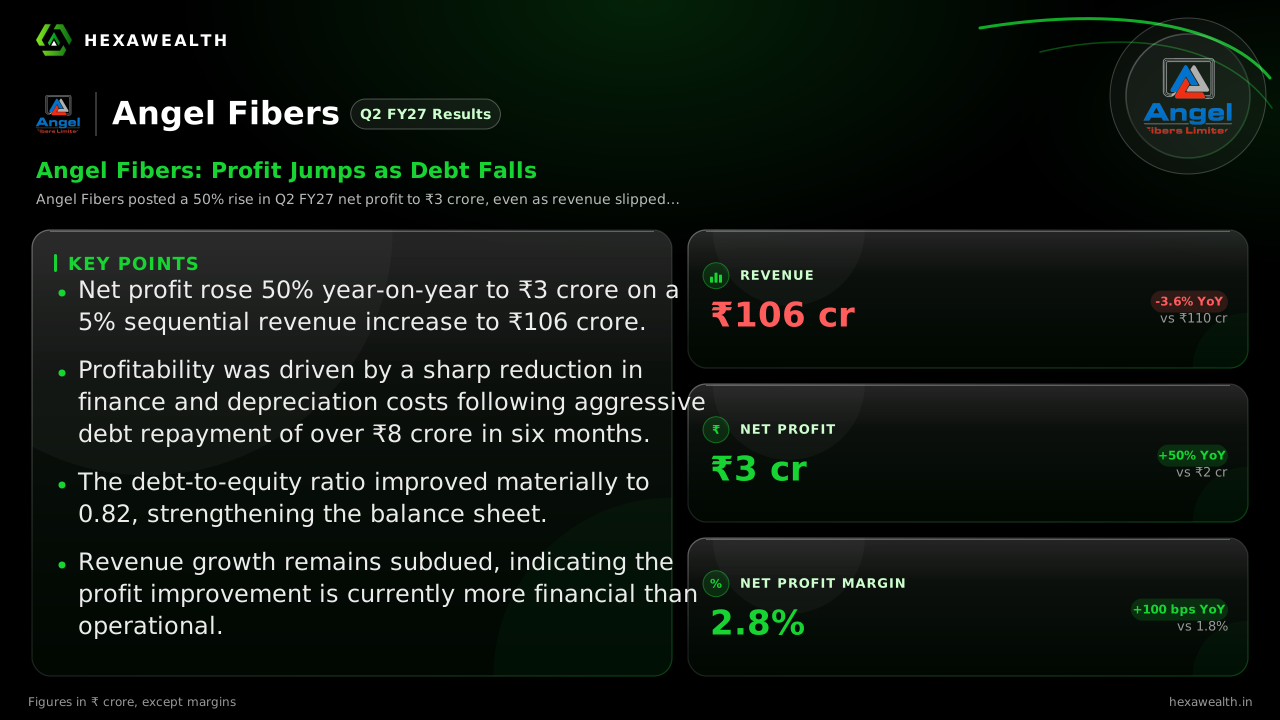
The story took a sharp turn immediately after FY26 closed. For the first half of FY27, Angel Fibers reported a net profit of ₹3 crore, up 76.5% year-on-year, as per a BSE filing. A key driver was a sharp reduction in finance costs, aided by aggressive debt repayment.
Live Chart
· ANGEL
(BSE)
ISIN: INE339Z01011
Reports from Multibagg.ai and Scanx.trade confirm the company cut total borrowings by ₹8.09 crore in six months, improving its debt-equity ratio to 0.82 from 1.18. Strong operating cash flow of over ₹9 crore funded this deleveraging.
Hexa Perspective
The quarter confirms Angel Fibers operates in a commodity trap where sales growth offers little protection. The margin structure is too fragile to absorb routine cost swings, especially finance charges. The subsequent half-year profit rebound is encouraging but stems from balance sheet repair, not a fundamental improvement in operating spreads.
Investors are weighing whether this deleveraging marks a sustainable shift or a brief respite. For the turnaround to hold, the company needs its operating margin to rise durably above its cost of debt—a tall order in a competitive spinning industry.
Key Points
- Annual revenue grew 5.3% in FY26, but net profit fell 30.3%, highlighting severe margin pressure.
- Q4 FY26 net profit was zero, pressured by a 100% quarter-on-quarter jump in interest expense.
- The company has since cut debt aggressively in H1 FY27, leading to a 76.5% jump in half-yearly profit.
- Operating margins remain perilously thin at around 1%, leaving profitability vulnerable to any cost increase.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.