Mittal Sections (MITTALSTL) Q2 FY27 Swings to Loss as Costs Outpace Slowing Sales
The structural steel maker posted a ₹2 crore net loss in Q2 FY27, with revenue down 3% year-on-year as rising interest and employee costs squeezed margins.
Mittal Sections swung to a quarterly net loss of ₹2 crore as revenue declined and expenses rose. Higher finance and employee costs, alongside a debt-funded expansion, pressured profitability in a seasonally softer market.
For a manufacturer of structural steel, the quarter ending in September is often a test of resilience against monsoon-led construction slowdowns. Mittal Sections failed that test, sliding into a loss as costs climbed faster than its declining sales.
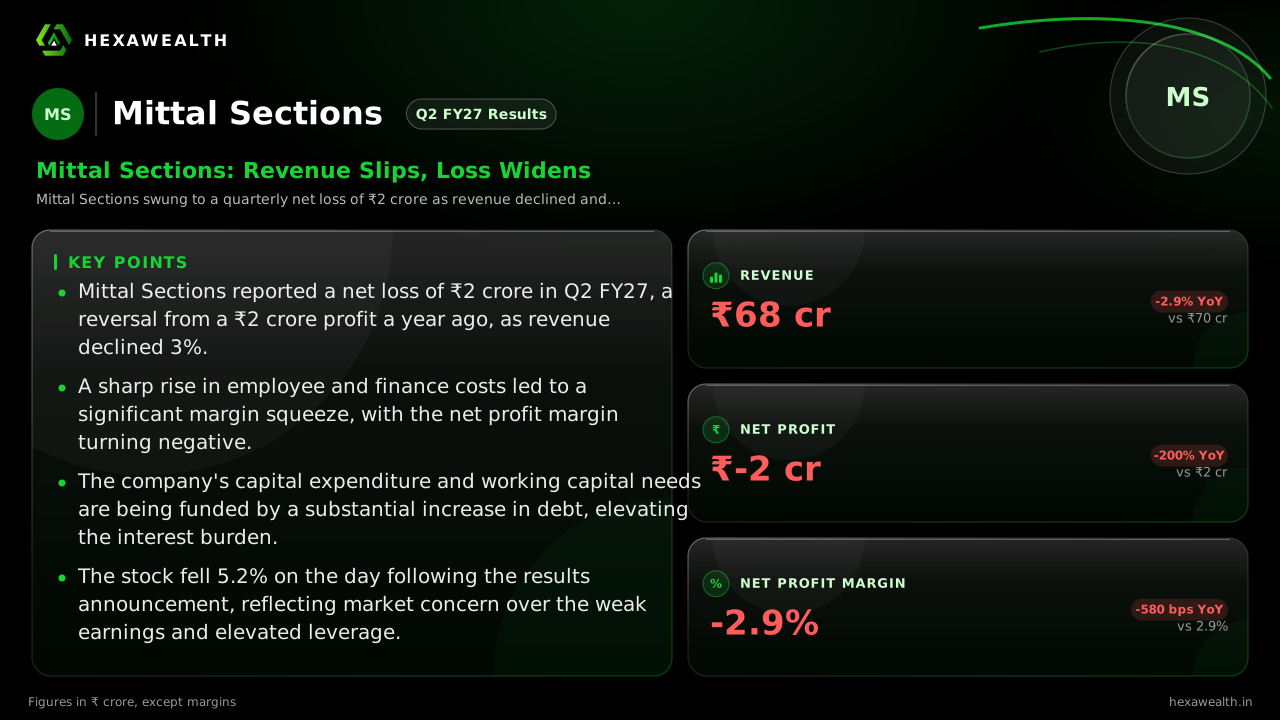
The numbers show a business under pressure. Revenue fell 3% year-on-year to ₹68 crore, while net profit swung from a ₹2 crore profit to a ₹2 crore loss. The net profit margin turned negative at -2.9%, a sharp 580 basis point drop from the same quarter last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 68.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 70.0
- Revenue (₹ Cr), Q4 FY26: 78.0
- Revenue (₹ Cr), Q2 FY27: 68.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 1.0
- Profit (₹ Cr), Q2 FY27: -2.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 68.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 70.0
- Revenue (₹ Cr), Q4 FY26: 78.0
- Revenue (₹ Cr), Q2 FY27: 68.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 1.0
- Profit (₹ Cr), Q2 FY27: -2.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 2.9
- Net Profit Margin (%), Q4 FY25: 1.5
- Net Profit Margin (%), Q2 FY26: 2.9
- Net Profit Margin (%), Q4 FY26: 1.3
- Net Profit Margin (%), Q2 FY27: -2.9
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 68.0YoY -2.9% | 70.0 |
| Profit (₹ Cr) | -2.0YoY -200% | 2.0 |
| Net Profit Margin (%) | -2.9YoY -200% | 2.9 |
The squeeze from two sides
A report by ScanX.Trade points to a classic margin squeeze. Total expenses grew nearly 6% year-on-year while revenue contracted. Employee benefit expenses more than doubled, and finance costs rose sharply to ₹2.42 crore for the half-year. This indicates that recent capital expenditures are being funded through increased leverage, which is now hitting the profit and loss statement.
The broader steel sector context adds to the challenge. Analysis from Reuters and Nexizo.ai suggests that while post-monsoon demand was expected to revive, higher coking coal costs and cautious buyer sentiment created a volatile pricing environment. For a smaller player like Mittal Sections, such input cost pressures are harder to absorb.
Funding growth with debt
The company's expansion is being financed largely by debt. According to a monitoring report cited by InvestyWise, Mittal Sections utilized over ₹20 crore from its IPO proceeds for capital expenditure in the quarter. Furthermore, analysis from Multibagg.ai shows the company funded a ₹24.45 crore investing outflow in the first half primarily through ₹36.21 crore in long-term borrowings.
Live Chart
· MITTALSTL
(BSE)
ISIN: INE833Q01012
This has pushed total financial indebtedness to ₹59.6 crore, as noted by mCapital.in. While there are no reported defaults, the interest burden from this debt is a clear and present drag on profitability, unlikely to ease until new capacity generates sufficient returns.
Key Points
- Mittal Sections reported a net loss of ₹2 crore in Q2 FY27, a reversal from a ₹2 crore profit a year ago, as revenue declined 3%.
- A sharp rise in employee and finance costs led to a significant margin squeeze, with the net profit margin turning negative.
- The company's capital expenditure and working capital needs are being funded by a substantial increase in debt, elevating the interest burden.
- The stock fell 5.2% on the day following the results announcement, reflecting market concern over the weak earnings and elevated leverage.
Hexa Perspective
The quarter reveals a business caught between cyclical demand softness and a self-inflicted cost problem. The debt-funded expansion adds a fixed financial cost that the current operating scale cannot support, turning a modest revenue dip into a loss.
Investors are now weighing whether the new capacity, once operational, can drive enough volume and margin improvement to service the higher debt. Until then, the company's earnings will remain vulnerable to any further slowdown in construction demand or spikes in steel input costs. The path to profitability hinges on execution and a supportive market, both of which are uncertain in the near term.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.