Misquita Engineering (MISQUITA) Q2 FY27 Profit Halved Despite Flat Revenue
The precision components maker saw its net profit plunge 47% year-on-year as higher costs erased a modest revenue gain, leaving margins squeezed.
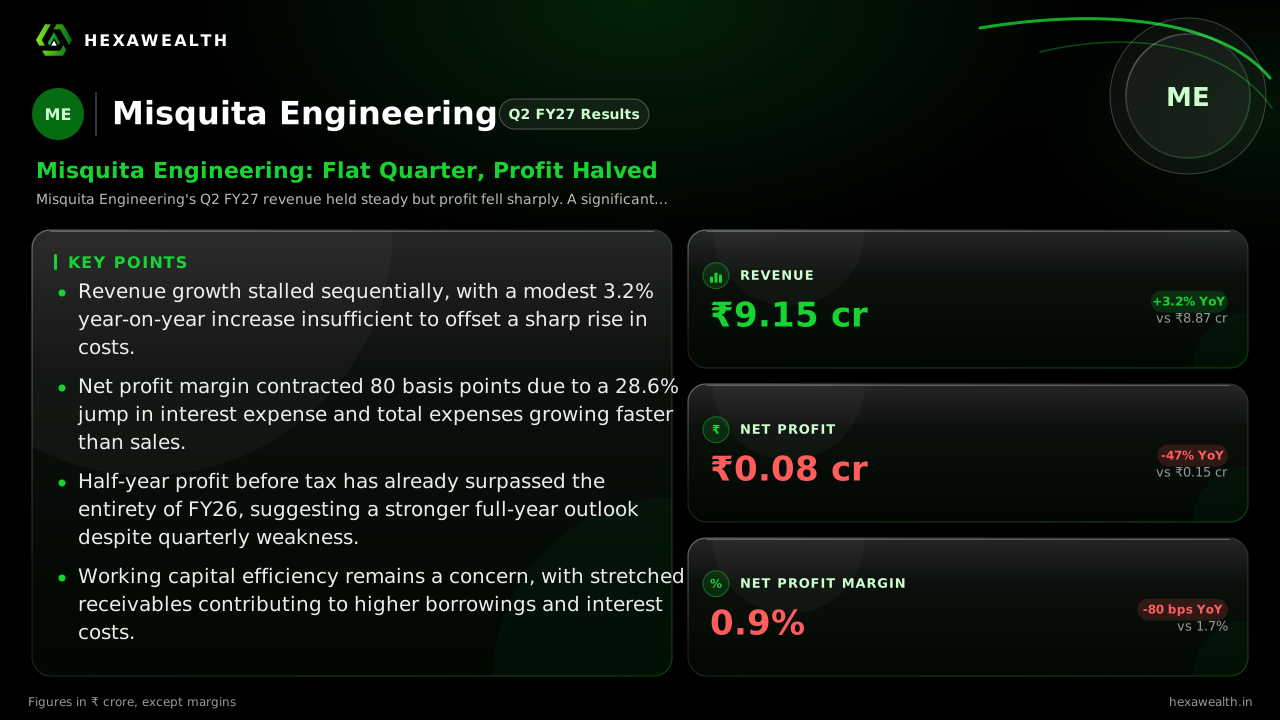
Misquita Engineering's Q2 FY27 revenue held steady but profit fell sharply. A significant rise in interest and operating expenses compressed margins, though a strong first-half performance suggests a potential recovery ahead.
For a precision machining business, steady revenue is only half the story if costs run ahead. Misquita Engineering's September quarter delivered exactly that tension, with sales holding firm but profits collapsing under the weight of higher expenses.
The numbers show a standstill. Revenue was flat sequentially at ₹9.15 crore, and up a modest 3.2% from a year ago. Net profit, however, halved year-on-year to ₹0.08 crore. The net profit margin contracted by 80 basis points to 0.9%.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
- Revenue (₹ Cr.), Q2 FY25: 5.52
- Revenue (₹ Cr.), Q4 FY25: 6.47
- Revenue (₹ Cr.), Q2 FY26: 8.87
- Revenue (₹ Cr.), Q4 FY26: 9.15
- Revenue (₹ Cr.), Q2 FY27: 9.15
- Profit (₹ Cr.), Q2 FY25: 0.19
- Profit (₹ Cr.), Q4 FY25: 0.00
- Profit (₹ Cr.), Q2 FY26: 0.15
- Profit (₹ Cr.), Q4 FY26: 0.08
- Profit (₹ Cr.), Q2 FY27: 0.08
Revenue (₹ Cr.)
- Revenue (₹ Cr.), Q2 FY25: 5.52
- Revenue (₹ Cr.), Q4 FY25: 6.47
- Revenue (₹ Cr.), Q2 FY26: 8.87
- Revenue (₹ Cr.), Q4 FY26: 9.15
- Revenue (₹ Cr.), Q2 FY27: 9.15
Profit (₹ Cr.)
- Profit (₹ Cr.), Q2 FY25: 0.19
- Profit (₹ Cr.), Q4 FY25: 0.00
- Profit (₹ Cr.), Q2 FY26: 0.15
- Profit (₹ Cr.), Q4 FY26: 0.08
- Profit (₹ Cr.), Q2 FY27: 0.08
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 3.4
- Net Profit Margin (%), Q4 FY25: 0.0
- Net Profit Margin (%), Q2 FY26: 1.7
- Net Profit Margin (%), Q4 FY26: 0.9
- Net Profit Margin (%), Q2 FY27: 0.9
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr.) | 9.15YoY +3.2% | 8.87 |
| Profit (₹ Cr.) | 0.08YoY -47% | 0.15 |
| Net Profit Margin (%) | 0.9YoY -47% | 1.7 |
The cost pinch that erased gains
A closer look reveals where the money went. Total expenses rose 4.3% year-on-year, outpacing revenue growth. More critically, interest expense surged 28.6% to ₹0.09 crore. According to a report by mcapital, this follows a near-doubling of borrowings to fund working capital needs.
This points to a working capital strain. The same analysis notes debtor days stretched to 209 in FY26, meaning customers are taking much longer to pay. This locks up cash, forcing the company to borrow more and bear the resulting finance cost.
A brighter first-half story
Despite the weak quarterly profit, the half-year picture offers a pivot. Analysis by mcapital shows the company's unaudited H1 FY27 profit before tax of about ₹0.32 crore has already exceeded the full-year PBT of ₹0.31 crore for FY26.
Live Chart
· MISQUITA
(BSE)
ISIN: INE957W01025
This implies the severe cost pressures from the prior quarter may be easing with better operational scale. The report projects FY27 revenue could rise 11-17% and net profit may nearly double from the small base of ₹0.23 crore last year.
Key Points
- Revenue growth stalled sequentially, with a modest 3.2% year-on-year increase insufficient to offset a sharp rise in costs.
- Net profit margin contracted 80 basis points due to a 28.6% jump in interest expense and total expenses growing faster than sales.
- Half-year profit before tax has already surpassed the entirety of FY26, suggesting a stronger full-year outlook despite quarterly weakness.
- Working capital efficiency remains a concern, with stretched receivables contributing to higher borrowings and interest costs.
Hexa Perspective
The quarter underscores Misquita's vulnerability to cost inflation and working capital cycles. While the top line is stable, profitability is fragile. The promising H1 performance suggests management is navigating these pressures, but the path to sustained margin improvement is narrow.
It hinges on converting sales faster and managing input costs, all within a competitive precision machining landscape. Investors are weighing the potential for a profit rebound in FY27 against the demonstrated sensitivity of earnings to financing costs.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.