Associated Coaters (ASSOCIATED) Q4 FY26 Profit Drops 12% Despite 38% Sales Surge
The powder coating specialist posted strong top-line growth in Q4 FY26, but a sharp rise in expenses led to a double-digit profit decline and margin compression.
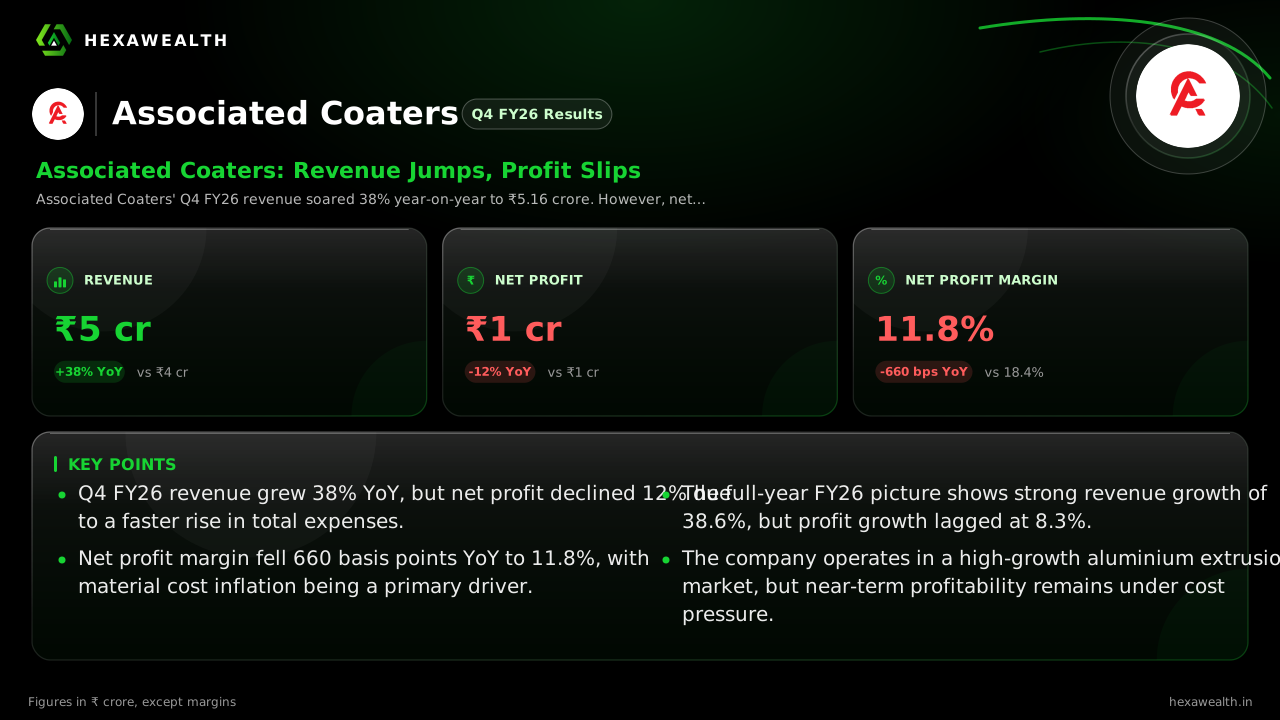
Associated Coaters' Q4 FY26 revenue soared 38% year-on-year to ₹5.16 crore. However, net profit fell 12% to ₹0.61 crore as total expenses grew faster than sales, squeezing the net profit margin by 660 basis points.
For a company riding India's construction and infrastructure boom, the fourth quarter should have been a clear win. Associated Coaters, a provider of powder coating services for aluminium extrusions, saw demand surge, driving revenue sharply higher. Yet the bottom line tells a story of costs rising even faster, turning strong sales growth into weaker profits.
The numbers show the split clearly. Revenue for the quarter ended March 2026 jumped 38% year-on-year to ₹5.16 crore, and soared 66.5% from the previous quarter. Net profit, however, fell 11.6% year-on-year to ₹0.61 crore, though it improved 27% sequentially. The net profit margin contracted sharply to 11.8%, down from 18.4% a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 5.16YoY +38% | 3.74 |
| Profit (₹ Cr) | 0.61YoY -12% | 0.69 |
| Net Profit Margin (%) | 11.8YoY -36% | 18.4 |
Why margins came under pressure
The profit squeeze was driven by expenses that grew 54.4% year-on-year, far outpacing the 38% revenue growth. Research from mcapital.in points to higher raw material, employee, and other expenses as the culprits, keeping profitability under pressure. A breakdown from lax.sh shows material costs as a percentage of sales rose to 60% in Q4 FY26, up from 46% a year earlier.
This cost pressure is not a one-quarter event. For the full financial year FY26, revenue grew 38.6% to ₹8.26 crore, but profit growth was a modest 8.3% to ₹1.15 crore. The annual operating margin, as reported by newboard.in, fell to 19.6% from 28.5% in FY25, confirming a sustained margin compression trend.
The outlook amid industry growth
The underlying demand environment remains robust. The Indian aluminium extrusion market is projected to grow at a 14.1% CAGR through 2035, driven by construction, electric vehicles, and solar infrastructure, according to Datamintelligence. Powder coating is a key finishing segment expected to see accelerated growth.
Associated Coaters has invested to capture this demand, with a recent capacity expansion that enhanced production by 1.5x, as noted by Groww. However, the near-term challenge is managing input costs. The company's own H1 FY27 results show the trend continuing, with revenue up 9% but profit down 5.2% on higher expenses.
Key Points
- Q4 FY26 revenue grew 38% YoY, but net profit declined 12% due to a faster rise in total expenses.
- Net profit margin fell 660 basis points YoY to 11.8%, with material cost inflation being a primary driver.
- The full-year FY26 picture shows strong revenue growth of 38.6%, but profit growth lagged at 8.3%.
- The company operates in a high-growth aluminium extrusion market, but near-term profitability remains under cost pressure.
Hexa Perspective
Associated Coaters is caught in a classic growth squeeze. It is successfully riding a structural demand wave in building materials and infrastructure, evidenced by its stellar revenue trajectory. Yet, it has not been able to fully pass on rising input costs, leading to significant margin erosion.
The next few quarters will test its pricing power and operational efficiency. If cost pressures persist without corresponding price increases, the strong top-line growth may continue to deliver only modest bottom-line gains. Investors are weighing this margin compression against the company's positioning in a rapidly expanding market.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.