Cosco (COSCO) Q2 FY27 (India) Swings to Profit on Revenue Surge, But High Debt Caps Gains
The sports goods maker posted a ₹0.78 crore profit in Q2 FY27, a sharp turnaround from last year's loss, yet its heavy debt burden and thin margins signal a fragile recovery.
Cosco (India) reported a net profit of ₹0.78 crore for Q2 FY27, reversing a year-ago loss, as revenue jumped 38%. However, elevated debt costs and a sequential sales dip highlight the challenges facing this micro-cap stock.
For Cosco (India), a maker and trader of sports goods, the September quarter delivered a clear operational win. Revenue surged from a depressed base, pushing the company into the black for a third straight quarter. Yet the market's muted reaction points to deeper, unresolved strains that keep profitability thin.
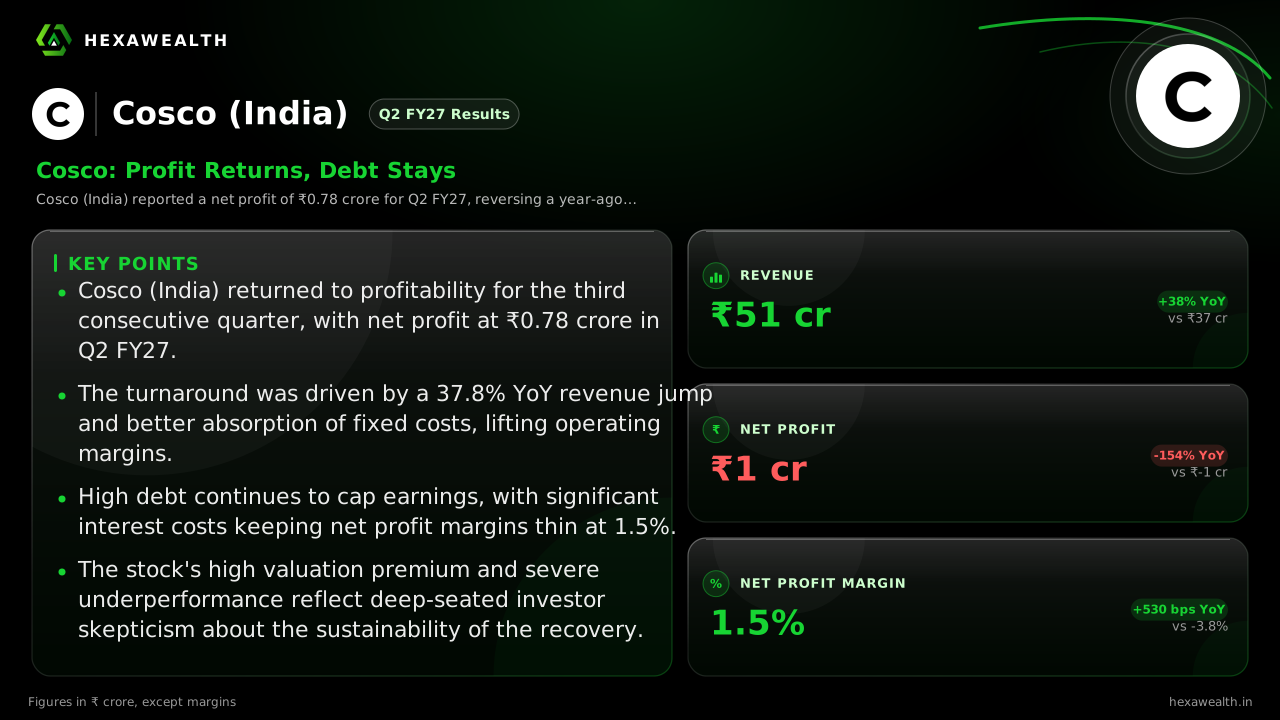
The numbers show a business in transition. Revenue of ₹51.36 crore grew 37.8% year-on-year, though it slipped 6.5% from the previous quarter. Net profit stood at ₹0.78 crore, a stark reversal from a ₹1.43 crore loss a year ago. The net profit margin, while positive at 1.5%, remains wafer-thin.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 51.36YoY +38% | 54.95 | 37.27 |
| Profit (₹ Cr) | 0.78YoY +155% | 0.70 | -1.43 |
| Net Profit Margin (%) | 1.5YoY +139% | 1.3 | -3.8 |
The Leverage That Lifted Margins
The profit improvement came from operating leverage, not cost cuts. MarketsMojo notes operating margin hit 5.28%, its highest in seven quarters, as higher sales better absorbed fixed costs. Employee expenses held steady, but the real story is on the top line. The strong year-on-year growth likely reflects a recovery in demand for sports and fitness equipment from a weak prior-year period.
The Anchor of High Debt
Operating gains are being heavily taxed by a persistent financial burden. Interest expense remained elevated at ₹1.10 crore, reflecting a debt-to-equity ratio of 1.21. MarketsMoji reports the company's debt-to-EBITDA ratio stands at a high 6.14 times, creating significant financial stress. This interest burden is the primary reason a 38% revenue surge translates into a net profit margin of just 1.5%.
The trading business is currently the profit driver. Analysis by MarketPing indicates that in FY26, the traded goods segment contributed positive operating profit, while the in-house manufacturing segment ran at a loss. This reliance on trading, coupled with import cost disadvantages highlighted in a NITI Aayog report, underscores the company's structural margin challenges.
A Market Waiting for More
The stock, trading at ₹186.10, was flat on results day and is down 23% over the past year. It commands a P/E of 67.2, an 18.5% premium to its industry, which MarketsMojo calls unjustified given weak return ratios. The firm maintains a 'Sell' rating on the stock, arguing that tactical improvement is insufficient to offset strategic weaknesses like high leverage and an average ROE of just 3.11%.
Key Points
- Cosco (India) returned to profitability for the third consecutive quarter, with net profit at ₹0.78 crore in Q2 FY27.
- The turnaround was driven by a 37.8% YoY revenue jump and better absorption of fixed costs, lifting operating margins.
- High debt continues to cap earnings, with significant interest costs keeping net profit margins thin at 1.5%.
- The stock's high valuation premium and severe underperformance reflect deep-seated investor skepticism about the sustainability of the recovery.
Hexa Perspective
This quarter confirms Cosco is operationally stable, having climbed out of the loss-making hole of FY26. The recovery, however, is built on a shaky foundation. For profits to grow meaningfully, the company must either consistently grow revenue to further leverage its cost base or make tangible progress on reducing its debt load. The current thin margins offer no buffer against demand softness or rising costs, making the path to durable shareholder returns exceptionally narrow. The market is rightly focused on these structural constraints rather than the quarterly profit print.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.