Namastika (NETPIX) Q2 FY27's Revenue Surges 1495% But Profit Slips Back Into Loss
Namastika's Q2 FY27 revenue rocketed over 1400% year-on-year, but costs soared even faster, pushing the company back into a net loss.
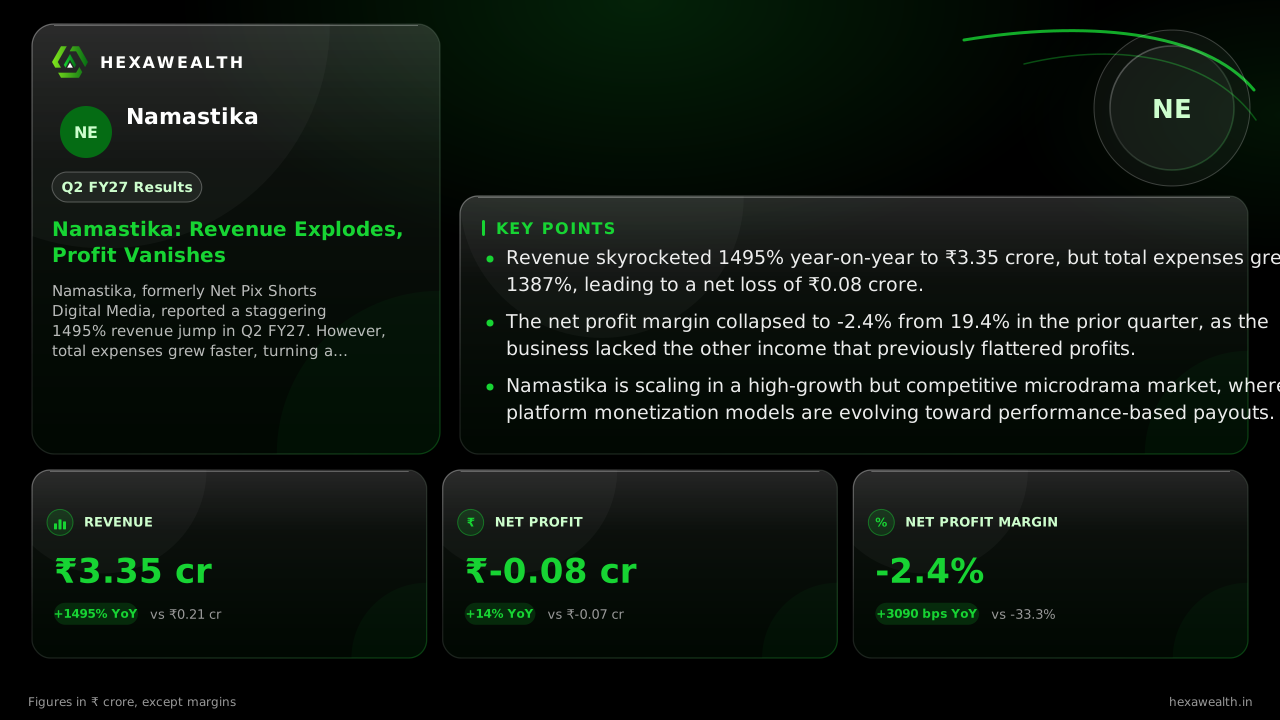
Namastika, formerly Net Pix Shorts Digital Media, reported a staggering 1495% revenue jump in Q2 FY27. However, total expenses grew faster, turning a prior quarter's profit into a loss and raising questions about the sustainability of its growth model.
For Namastika, the quarter was a tale of explosive growth that failed to reach the bottom line. The company, which recently changed its name from Net Pix Shorts Digital Media, saw revenue multiply fifteen-fold from a tiny base. Yet the costs of generating that business grew even faster, wiping out profitability and signaling the challenges of scaling a digital content venture.
The numbers show a stark disconnect. Revenue leapt to ₹3.35 crore in the September 2026 quarter, up 1495% from a year ago and 831% from the prior quarter. But total expenses surged 1387% year-on-year to ₹3.42 crore, outstripping sales. This pushed the company to a net loss of ₹0.08 crore, a sharp reversal from the ₹0.07 crore profit reported in March 2026.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 0.31
- Revenue (₹ Cr), Q4 FY25: 0.16
- Revenue (₹ Cr), Q2 FY26: 0.21
- Revenue (₹ Cr), Q4 FY26: 0.36
- Revenue (₹ Cr), Q2 FY27: 3.35
- Profit (₹ Cr), Q2 FY25: 0.03
- Profit (₹ Cr), Q4 FY25: -0.07
- Profit (₹ Cr), Q2 FY26: -0.07
- Profit (₹ Cr), Q4 FY26: 0.07
- Profit (₹ Cr), Q2 FY27: -0.08
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 0.31
- Revenue (₹ Cr), Q4 FY25: 0.16
- Revenue (₹ Cr), Q2 FY26: 0.21
- Revenue (₹ Cr), Q4 FY26: 0.36
- Revenue (₹ Cr), Q2 FY27: 3.35
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.03
- Profit (₹ Cr), Q4 FY25: -0.07
- Profit (₹ Cr), Q2 FY26: -0.07
- Profit (₹ Cr), Q4 FY26: 0.07
- Profit (₹ Cr), Q2 FY27: -0.08
Net Profit Margin
- Net Profit Margin, Q2 FY25: 9.7%
- Net Profit Margin, Q4 FY25: -43.8%
- Net Profit Margin, Q2 FY26: -33.3%
- Net Profit Margin, Q4 FY26: 19.4%
- Net Profit Margin, Q2 FY27: -2.4%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 3.35YoY +1495% | 0.21 |
| Profit (₹ Cr) | -0.08YoY -14% | -0.07 |
| Net Profit Margin | -2.4%YoY +93% | -33.3% |
The profit that wasn't
The dramatic margin collapse from 19.4% to -2.4% quarter-on-quarter has a clear culprit. According to filings reviewed by ForgeUp, the company's total expenses for the half-year ending September 2026 were ₹3.42 crore, just above its revenue of ₹3.35 crore. This suggests the revenue surge came with proportionally high operating costs, likely tied to content production, marketing, or platform fees.
A look back shows the prior quarter's profit was flattered by other income. In Q4 FY26, other income of ₹0.07 crore accounted for the entire reported profit of ₹0.07 crore. Strip that out, and the core business was at breakeven even then. The latest quarter had no such cushion, with other income at zero.
A market in transition
The company operates in India's booming but crowded microdrama market. A report highlighted by LinkedIn notes this segment crossed $300 million in India within its first year and could reach $3–$4.5 billion by 2030. However, platforms are shifting toward performance-based payouts, buying audience confidence rather than just content volume.
Live Chart
· NETPIX
(BSE)
ISIN: INE0D5F01013
This environment demands both scale and efficiency, a balance Namastika has yet to strike. With no specific management commentary on the cost spike in the results, the path to sustainable profitability remains unclear. The company did secure shareholder approval to change its name to Namastika Limited, effective November 19, 2026.
Key Points
- Revenue skyrocketed 1495% year-on-year to ₹3.35 crore, but total expenses grew 1387%, leading to a net loss of ₹0.08 crore.
- The net profit margin collapsed to -2.4% from 19.4% in the prior quarter, as the business lacked the other income that previously flattered profits.
- Namastika is scaling in a high-growth but competitive microdrama market, where platform monetization models are evolving toward performance-based payouts.
Hexa Perspective
This quarter reveals a company in the painful early stages of scaling. The revenue jump confirms market demand for its short-form content, but the cost structure is not yet disciplined enough to convert that demand into profit. The valuation, with a P/E of 3360 against an industry average of 29, prices in transformative success far ahead of the current reality. Investors are left weighing the potential of the microdrama boom against the evident execution risk. For the story to improve, Namastika must demonstrate it can grow revenue without a parallel surge in expenses, proving it has a viable, not just a visible, business model.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.