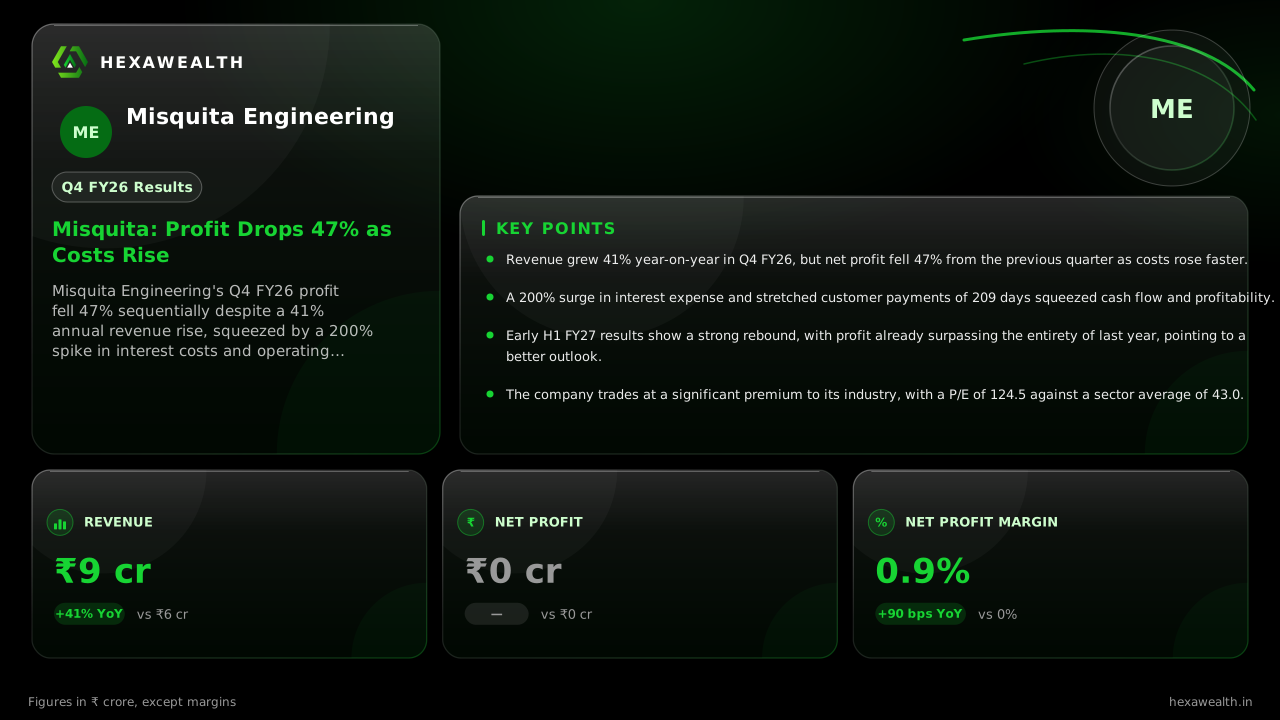
The precision components maker saw a sharp quarterly profit drop as higher interest and operating expenses erased sales growth, though a strong H1 FY27 offers a brighter outlook.
Misquita Engineering's Q4 FY26 profit fell 47% sequentially despite a 41% annual revenue rise, squeezed by a 200% spike in interest costs and operating expenses. However, a strong first half of FY27 points to a potential profit recovery ahead.
For a precision engineering firm, growth is only half the story if costs rise faster. Misquita Engineering’s March quarter delivered that exact tension: a 41% annual sales surge met a 47% sequential profit drop, revealing the squeeze underneath the headline growth.
The numbers show a business expanding but struggling to convert that scale into earnings. Revenue for Q4 FY26 reached ₹9.15 crore, up 3% from the previous quarter. Yet net profit fell to ₹8 lakh, and the net profit margin contracted 80 basis points to 0.9%.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
Revenue (₹ Cr.), Q4 FY24: 4.75
Revenue (₹ Cr.), Q2 FY25: 5.52
Revenue (₹ Cr.), Q4 FY25: 6.47
Revenue (₹ Cr.), Q2 FY26: 8.87
Revenue (₹ Cr.), Q4 FY26: 9.15
Profit (₹ Cr.), Q4 FY24: 0.33
Profit (₹ Cr.), Q2 FY25: 0.19
Profit (₹ Cr.), Q4 FY25: 0.00
Profit (₹ Cr.), Q2 FY26: 0.15
Profit (₹ Cr.), Q4 FY26: 0.08
Revenue (₹ Cr.)
Revenue (₹ Cr.), Q4 FY24: 4.75
Revenue (₹ Cr.), Q2 FY25: 5.52
Revenue (₹ Cr.), Q4 FY25: 6.47
Revenue (₹ Cr.), Q2 FY26: 8.87
Revenue (₹ Cr.), Q4 FY26: 9.15
Profit (₹ Cr.)
Profit (₹ Cr.), Q4 FY24: 0.33
Profit (₹ Cr.), Q2 FY25: 0.19
Profit (₹ Cr.), Q4 FY25: 0.00
Profit (₹ Cr.), Q2 FY26: 0.15
Profit (₹ Cr.), Q4 FY26: 0.08
Net Profit Margin (%)
Net Profit Margin (%), Q4 FY24: 6.9
Net Profit Margin (%), Q2 FY25: 3.4
Net Profit Margin (%), Q4 FY25: 0.0
Net Profit Margin (%), Q2 FY26: 1.7
Net Profit Margin (%), Q4 FY26: 0.9
Metric
CurrentQ4 FY26
Same quarter LYQ4 FY25
Revenue (₹ Cr.)
9.15YoY +41%
6.47
Profit (₹ Cr.)
0.08
0.00
Net Profit Margin (%)
0.9
0.0
Why the profit fell faster than sales
The margin squeeze had two clear drivers. Interest expense tripled year-on-year, rising 200% to ₹9 lakh, according to the company's financials. This followed a near-doubling of borrowings to ₹2.5 crore by the end of FY26, as reported by Newboard.
Operating costs also rose 4.3% sequentially, outpacing the 3.2% revenue growth. This suggests the company faced higher input or execution costs even as it ramped up sales.
The working capital drag
Financing that growth is tying up more cash. Data from Newboard shows debtor days stretched to 209 days in FY26, up from 118 days a year earlier. That means customers are taking much longer to pay, locking up capital the business could otherwise use or borrow less of.
Live Chart
· MISQUITA
(BSE)
ISIN: INE957W01025
The interest cover ratio, a measure of operating profit's ability to service debt, stood at 2.9 times. This is a thin buffer against further rate hikes or a slowdown in collections.
A pivot point in the new year
Despite the weak finish to FY26, the story has already turned in the new fiscal year. According to an analysis by mcapital, the company's unaudited H1 FY27 profit before tax of about ₹0.32 crore has already exceeded the full-year PBT of ₹0.31 crore for FY26.
This implies the cost pressures of Q4 may be easing with better operational scale. The same report projects FY27 revenue could rise 11-17% and net profit may nearly double from the small base of ₹0.23 crore in FY26.
Key Points
Revenue grew 41% year-on-year in Q4 FY26, but net profit fell 47% from the previous quarter as costs rose faster.
A 200% surge in interest expense and stretched customer payments of 209 days squeezed cash flow and profitability.
Early H1 FY27 results show a strong rebound, with profit already surpassing the entirety of last year, pointing to a better outlook.
The company trades at a significant premium to its industry, with a P/E of 124.5 against a sector average of 43.0.
“
Hexa Perspective
The quarter underscores a classic small-cap growth challenge: scaling revenue before the cost structure is fully under control. The spike in interest and receivables shows that growth is being funded, not yet funding itself.
The sharp recovery indicated in H1 FY27 is promising but needs to hold. For the full-year turnaround to materialize, the company must demonstrate it can sustain sales momentum while improving working capital efficiency. Investors are paying a high multiple for a profitability level that has been volatile, making consistent execution in the coming quarters critical.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Misquita Engineering's Q4 FY26 results?
Misquita Engineering reported Q4 FY26 revenue of ₹9.15 crore, a 41.4% increase from the same quarter last year. Net profit for the quarter was ₹0.08 crore, which was a 46.7% decline compared to the previous quarter (Q2 FY26).
Why did Misquita Engineering's Q4 FY26 net profit fall 46.7% quarter-on-quarter despite a 3.2% revenue increase?
Misquita Engineering's Q4 profit fell due to a sharp rise in costs. Interest expense jumped 200% year-on-year to ₹0.09 crore, and total expenses grew 4.3% sequentially, faster than the 3.2% revenue growth. This combination severely squeezed the net profit margin.
What caused the 80 bps sequential contraction in Misquita Engineering's net profit margin in Q4 FY26?
The 80 basis point margin contraction in Q4 FY26 was primarily driven by a significant increase in interest costs, which tripled year-on-year. Higher operating expenses, which rose faster than revenue during the quarter, also contributed to the profitability squeeze.
What is the status of Misquita Engineering's debt and working capital?
Misquita Engineering's borrowings increased to ₹2.5 crore at the end of FY26, up from ₹1.3 crore a year prior. Working capital efficiency deteriorated, with debtor days stretching to 209 days in FY26, meaning customers are taking much longer to pay their bills.
What guidance did Misquita Engineering management provide for FY27?
While no formal guidance was issued, analysis by mcapital points to a strong start. H1 FY27 profit before tax of ~₹0.32 crore has already exceeded the full-year FY26 PBT. This suggests management expects FY27 revenue to grow 11-17% and net profit to potentially double from the ₹0.23 crore base of FY26.
Did Misquita Engineering's Q4 FY26 results beat or miss analyst estimates?
The results likely missed on profitability. While revenue growth of 41.4% was strong, the 47% sequential drop in profit and the severe margin contraction indicate earnings fell short of expectations. The company's valuation, trading at a 190% premium to the industry P/E, suggests the market was anticipating stronger bottom-line performance.
How has Misquita Engineering's stock price reacted to the Q4 FY26 results announcement?
Specific post-results reaction data isn't detailed, but broader context shows the stock was down about 38% over the past year as of mid-November 2026. The stock traded at a P/E of 124.5, a significant premium to its industry peers, indicating high expectations that the Q4 profit slump may have challenged.
What is Misquita Engineering's current order book and backlog position as of March 2026?
The verified financial results and accompanying research do not specify Misquita Engineering's order book or backlog position as of March 2026. The analysis focuses on reported revenue and profit figures for the completed quarter.
Are there any customer concentration risks affecting Misquita Engineering?
Yes, according to analysis from Know Your Company, a key risk for Misquita Engineering is customer concentration. The company is heavily reliant on the consumer appliance sector, making it vulnerable to demand fluctuations from a limited number of major brands that purchase its precision components.
What is the competitive position of Misquita Engineering in CNC machining?
Misquita Engineering operates as a niche mid-tier player in precision CNC machining, specializing in components for front-loading washing machines. Analysts note its competitive moat comes from technical integration with client designs, but it faces pricing pressure from large OEMs and rising raw material costs, which can pressure its already thin margins.
Misquita Engineering Q4 FY26 results August 2026
Misquita Engineering's Q4 FY26 (March 2026 quarter) results were announced on May 15, 2026. The company reported revenue of ₹9.15 crore, up 41.4% year-on-year, but net profit fell to ₹0.08 crore, a 46.7% drop from the previous quarter.
Misquita Engineering Q2 net profit
Misquita Engineering's net profit for Q2 FY26 (September 2025 quarter) was ₹0.15 crore. This was higher than the ₹0.08 crore profit reported in the subsequent Q4 FY26, indicating a sequential decline in profitability in the second half of the fiscal year.