Mittal Sections (MITTALSTL) Profit Halved in Q4 FY26 as Costs Outpace Revenue Growth
The structural steel maker saw revenue climb 15% year-on-year, but net profit fell 50% sequentially as expenses surged, squeezing margins.
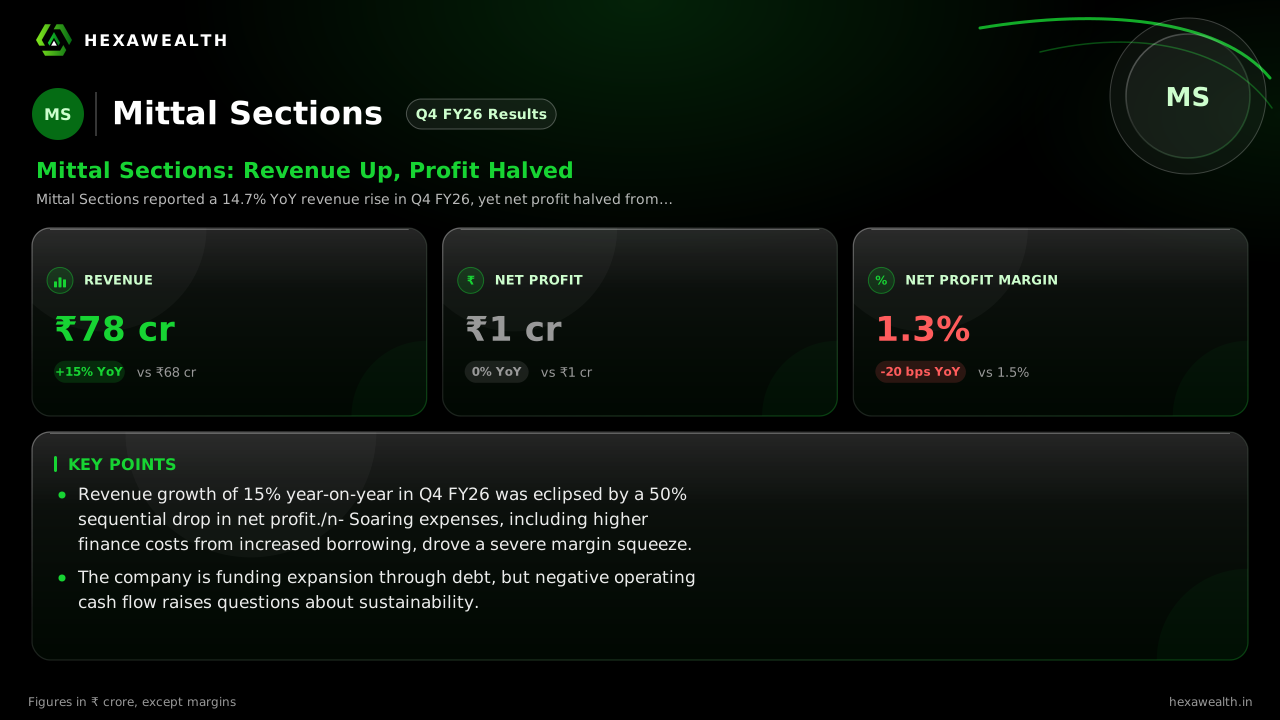
Mittal Sections reported a 14.7% YoY revenue rise in Q4 FY26, yet net profit halved from the previous quarter. The sharp margin compression highlights persistent cost pressures that overshadowed top-line growth.
For a structural steel maker like Mittal Sections, a quarter of rising construction demand should flow straight to the bottom line. The March quarter brought that demand, with revenue up 15% from a year ago. Yet net profit halved sequentially, as costs grew faster than sales.
The numbers tell a story of pressure. Revenue for the quarter ended March 2026 was ₹78 crore, up from ₹68 crore in Q4 FY25. Profit, however, was just ₹1 crore, flat year-on-year but down 50% from the ₹2 crore earned in Q2 FY26. The net profit margin thinned to 1.3%, a drop of 160 basis points from the prior quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 68.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 70.0
- Revenue (₹ Cr), Q4 FY26: 78.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 1.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 68.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 70.0
- Revenue (₹ Cr), Q4 FY26: 78.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 1.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 2.9
- Net Profit Margin (%), Q4 FY25: 1.5
- Net Profit Margin (%), Q2 FY26: 2.9
- Net Profit Margin (%), Q4 FY26: 1.3
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 78.0YoY +15% | 68.0 |
| Profit (₹ Cr) | 1.0YoY 0% | 1.0 |
| Net Profit Margin (%) | 1.3YoY -13% | 1.5 |
Why the top line did not reach the bottom
The gap between sales and profit was driven by a sharp rise in expenses. Total expenses jumped 18% year-on-year and 16% quarter-on-quarter, according to the company's filings. Research from StockFin.ai notes the company's margin decline was driven by higher expenses, a trend seen across the full year where the profit margin fell to 2.3%.
This cost pressure is not a one-quarter event. For the half-year ended September 2026, Mittal Sections reported a net loss of ₹1.98 crore, as per a Market News & Analysis report. The shift was due to a 5.9% rise in total expenses even as revenue fell 3.5%, pointing to a sustained margin squeeze.
Funding growth while profits shrink
To support its operations, the company has leaned heavily on debt. Long-term borrowings surged to ₹49.71 crore as of September 2026, up from ₹13.49 crore at the end of March, reports from multibagg.ai show. This funded a significant capex program, including ₹20.21 crore utilized for land, building, and machinery in the September quarter, as detailed in an IPO fund utilization report.
Live Chart
· MITTALSTL
(BSE)
ISIN: INE833Q01012
The increased leverage comes with a cost. Finance expenses stood at ₹2.42 crore for the first half of FY27. With cash flow from operations deeply negative at ₹-7.88 crore for the same period, the company's ability to fund growth internally remains constrained.
A market waiting for direction
Management has provided no forward guidance on demand or margins, according to a StockFin.ai analysis of recent communications. This silence, amid a sector where peers like Surya Roshni are forecasting improved per-tonne earnings, adds uncertainty. The stock trades at a P/E of 7.9, a 60% discount to the industry average, reflecting the market's cautious stance.
Key Points
- Revenue growth of 15% year-on-year in Q4 FY26 was eclipsed by a 50% sequential drop in net profit./n- Soaring expenses, including higher finance costs from increased borrowing, drove a severe margin squeeze.
- The company is funding expansion through debt, but negative operating cash flow raises questions about sustainability.
Hexa Perspective
Mittal Sections is caught between two forces. Government infrastructure spending is lifting demand for its structural products, as seen in the quarterly revenue climb. Yet it cannot convert that into earnings, with costs—some likely from its own expansion—rising relentlessly.
The next few quarters hinge on whether those new capacities can be ramped up efficiently to generate operating leverage. Until then, with debt rising and management silent on the path to profitability, the stock's deep discount to the sector seems a fair reflection of the risk.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.