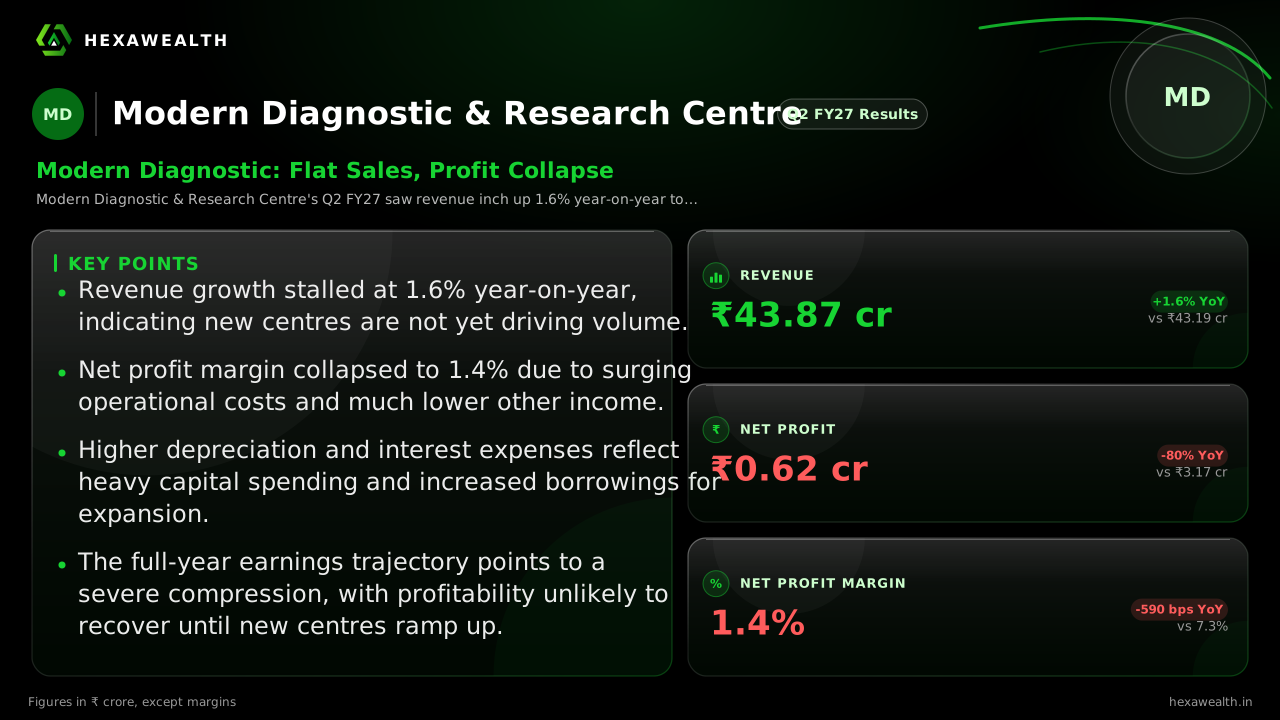
Modern Diagnostic (MDRC) Q2 FY27 Profit Collapses 80% as Expansion Costs Bite
The diagnostic chain's revenue held steady, but a surge in expenses from new labs and higher interest wiped out nearly all profitability.
Modern Diagnostic & Research Centre's Q2 FY27 saw revenue inch up 1.6% year-on-year to ₹43.87 crore. However, net profit plunged 80.4% to just ₹0.62 crore as expansion-related costs soared and other income dried up.
For a regional diagnostic chain spending to grow, the test is whether new centres fill fast enough to cover their upfront costs. Modern Diagnostic’s September quarter shows that balance tipping the wrong way. Revenue was nearly flat, but profit collapsed under the weight of its own expansion.
The numbers tell a story of top-line stagnation and a brutal margin squeeze. Revenue of ₹43.87 crore was up a mere 1.6% from a year ago. Net profit, however, cratered 80.4% to ₹0.62 crore. The net profit margin shrank to 1.4%, down 590 basis points year-on-year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 43.19
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 39.92
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 43.87
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.17
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 2.08
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.62
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 43.19
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 39.92
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 43.87
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.17
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 2.08
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.62
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 7.3
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 5.2
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 1.4
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 43.87 | 39.92 |
| Profit (₹ Cr) | 0.62 | 2.08 |
| Net Profit Margin (%) | 1.4 | 5.2 |
Why the bottom line vanished
A 11.2% year-on-year jump in total expenses was the primary culprit. Research from mcapital.in points to staff, rent and ramp-up costs at new laboratories in Gurugram, East Delhi, Meerut and Mohali. Depreciation also rose 17.4%, a direct hit from ₹5.53 crore of equipment spent in the quarter.
At the same time, a crucial cushion vanished. Other income plunged 83.6% to just ₹0.10 crore. This removed a support that had previously helped offset operating costs, making the expense surge far more painful for the bottom line.
The debt and expansion drag
Higher interest costs, up 18.4% year-on-year, added to the pressure. This reflects increased borrowings, which stood at ₹37.1 crore at the end of FY26 according to newboard.in. The company is spending ahead of revenue, funding a network it expects to grow from 25 to about 30 centres.
Live Chart
· MDRC
(BSE)
ISIN: INE1HK501016
Management is considering an acquisition of a diagnostic centre with imaging facilities, but no terms were disclosed. The immediate outlook, however, is for continued strain. mcapital.in estimates suggest the full-year net profit could be 70-90% below the ₹5.25 crore reported in FY26.
Key Points
- Revenue growth stalled at 1.6% year-on-year, indicating new centres are not yet driving volume.
- Net profit margin collapsed to 1.4% due to surging operational costs and much lower other income.
- Higher depreciation and interest expenses reflect heavy capital spending and increased borrowings for expansion.
- The full-year earnings trajectory points to a severe compression, with profitability unlikely to recover until new centres ramp up.
Hexa Perspective
This quarter lays bare the execution risk in Modern Diagnostic’s expansion. The model is working in reverse: costs are arriving today, while the revenue payoff is deferred. The 590-basis-point margin contraction is severe, and with a large part of its IPO capex still to be spent, the depreciation drag has room to run.
The path back requires new centres to fill rapidly, turning fixed costs into operating leverage. Until patient volumes catch up to the expanded footprint, the company will be spending to stand still. Investors are left weighing whether this is a temporary trough in an investment cycle or a sign that growth is becoming prohibitively expensive.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.