All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 22 November 20263 min read

Ambo Agritec (AMBOAGRI) Q2 FY27's Trading Boom Masks a Cash Crunch

Revenue more than doubled year-on-year, but the profit jump was muted and operating cash flow stayed negative.

By Abhinav Singhvi, Founder & CEO Hexawealth · Created 14 November 2026

Ambo Agritec's Q2 FY27 saw a 66% revenue surge, driven by its trading segment. However, profit growth lagged and cash flow turned negative, raising questions about the sustainability of this trading-led expansion.

For Ambo Agritec, a quarter defined by explosive top-line growth reveals a business caught between two gears. The company's revenue more than doubled from a year ago, but the engine driving it—aggressive commodity trading—consumes cash faster than it generates profit.

The numbers tell a split story. Revenue hit ₹103 crore, up 66% from last September. Net profit was ₹2 crore, doubling year-on-year but rising from a low base. Sequentially, profit fell sharply from the March quarter's loss, yet the net profit margin remains thin at 1.9%.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Revenue & profitQ2 FY25 (Sep 2024) 52.0, Q4 FY25 (Mar 2025) 68.0, Q2 FY26 (Sep 2025) 62.0, Q4 FY26 (Mar 2026) 69.0, Q2 FY27 (Sep 2026) 103.0. Q2 FY25 (Sep 2024) 1.0, Q4 FY25 (Mar 2025) 0.0, Q2 FY26 (Sep 2025) 1.0, Q4 FY26 (Mar 2026) -1.0, Q2 FY27 (Sep 2026) 2.0-200-1000100200Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr), Q2 FY25 (Sep 2024): 52.0
  • Revenue (₹ Cr), Q4 FY25 (Mar 2025): 68.0
  • Revenue (₹ Cr), Q2 FY26 (Sep 2025): 62.0
  • Revenue (₹ Cr), Q4 FY26 (Mar 2026): 69.0
  • Revenue (₹ Cr), Q2 FY27 (Sep 2026): 103.0
  • Profit (₹ Cr), Q2 FY25 (Sep 2024): 1.0
  • Profit (₹ Cr), Q4 FY25 (Mar 2025): 0.0
  • Profit (₹ Cr), Q2 FY26 (Sep 2025): 1.0
  • Profit (₹ Cr), Q4 FY26 (Mar 2026): -1.0
  • Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.0

Revenue (₹ Cr)

Revenue (₹ Cr)Q2 FY25 (Sep 2024) 52.0, Q4 FY25 (Mar 2025) 68.0, Q2 FY26 (Sep 2025) 62.0, Q4 FY26 (Mar 2026) 69.0, Q2 FY27 (Sep 2026) 103.0050100150200Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr), Q2 FY25 (Sep 2024): 52.0
  • Revenue (₹ Cr), Q4 FY25 (Mar 2025): 68.0
  • Revenue (₹ Cr), Q2 FY26 (Sep 2025): 62.0
  • Revenue (₹ Cr), Q4 FY26 (Mar 2026): 69.0
  • Revenue (₹ Cr), Q2 FY27 (Sep 2026): 103.0

Profit (₹ Cr)

Profit (₹ Cr)Q2 FY25 (Sep 2024) 1.0, Q4 FY25 (Mar 2025) 0.0, Q2 FY26 (Sep 2025) 1.0, Q4 FY26 (Mar 2026) -1.0, Q2 FY27 (Sep 2026) 2.0-4-2024Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Profit (₹ Cr), Q2 FY25 (Sep 2024): 1.0
  • Profit (₹ Cr), Q4 FY25 (Mar 2025): 0.0
  • Profit (₹ Cr), Q2 FY26 (Sep 2025): 1.0
  • Profit (₹ Cr), Q4 FY26 (Mar 2026): -1.0
  • Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.0

Net Profit Margin

Net Profit MarginQ2 FY25 (Sep 2024) 1.9%, Q4 FY25 (Mar 2025) 0.0%, Q2 FY26 (Sep 2025) 1.6%, Q4 FY26 (Mar 2026) -1.4%, Q2 FY27 (Sep 2026) 1.9%-4%-2%0%2%4%Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Net Profit Margin, Q2 FY25 (Sep 2024): 1.9%
  • Net Profit Margin, Q4 FY25 (Mar 2025): 0.0%
  • Net Profit Margin, Q2 FY26 (Sep 2025): 1.6%
  • Net Profit Margin, Q4 FY26 (Mar 2026): -1.4%
  • Net Profit Margin, Q2 FY27 (Sep 2026): 1.9%
MetricCurrentQ2 FY27 (Sep 2026)PreviousQ4 FY26 (Mar 2026)
Revenue (₹ Cr)
103.0
69.0
Profit (₹ Cr)
2.0
-1.0
Net Profit Margin
1.9%
-1.4%

Why Profit Lagged the Revenue Surge

This growth came almost entirely from trading, not biscuits. According to a scanx.trade report, trading revenue more than doubled to over ₹86 crore, while manufacturing sales fell. Trading inherently carries lower margins, which explains why a 66% revenue jump yielded only a 30 basis-point improvement in net profit margin year-on-year.

Expenses climbed in lockstep with sales, up 67% year-on-year. This suggests the company is not yet achieving operating leverage from its trading scale. Profit before tax grew only 50%, held back by the low-margin profile of its booming segment.

The Cash That Never Arrived

A critical flaw emerged beneath the profit. Despite the operating profit, net cash flow from operations was negative ₹3.5 crore for the half-year, as reported by MCapital. Cash reserves dwindled to near zero as money was tied up in loans and advances to fund trading growth.

Live Chart

· AMBOAGRI

(BSE)

ISIN: INE0N6V01016

The company's cash conversion cycle was 137 days at the last fiscal year-end. This working capital intensity means profits are not backed by cash, a significant risk if trading volumes stall or credit terms tighten.

How Long Can This Run?

The immediate outlook is for continued top-line strength. The H1 revenue run-rate implies full-year sales could reach ₹180-195 crore, a 40-50% jump over FY26, as noted in analyst projections. However, this projection is contingent on the trading segment's momentum, which is funding its own growth through increased debt.

Borrowings rose by over ₹4 crore in six months to nearly ₹30 crore. With no analyst coverage providing formal ratings, the market's modest 2.9% share price bump post-results suggests investors are weighing growth against the deteriorating cash profile.

Key Points

  • Revenue growth of 66% was powered by a more-than-doubling of low-margin trading segment sales.
  • Net profit margin improved only slightly to 1.9%, as expenses rose in line with revenue.
  • Operating cash flow remained negative due to a sharp increase in working capital loans and advances.
  • The sustainability of growth depends on the company's ability to manage its cash conversion cycle and rising debt.

Hexa Perspective

Ambo Agritec's quarter showcases a potent but capital-intensive growth model. The trading engine can drive revenue multiples higher, as the H1 run-rate suggests. Yet, the model's weakness is its cash appetite—profits are an accounting entry while real liquidity is deployed as working capital.

The next few quarters will test whether this trading scale can eventually generate operating leverage and positive cash flow, or if it merely expands the balance sheet without improving returns. For now, the story is one of impressive top-line momentum built on financially fragile ground.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
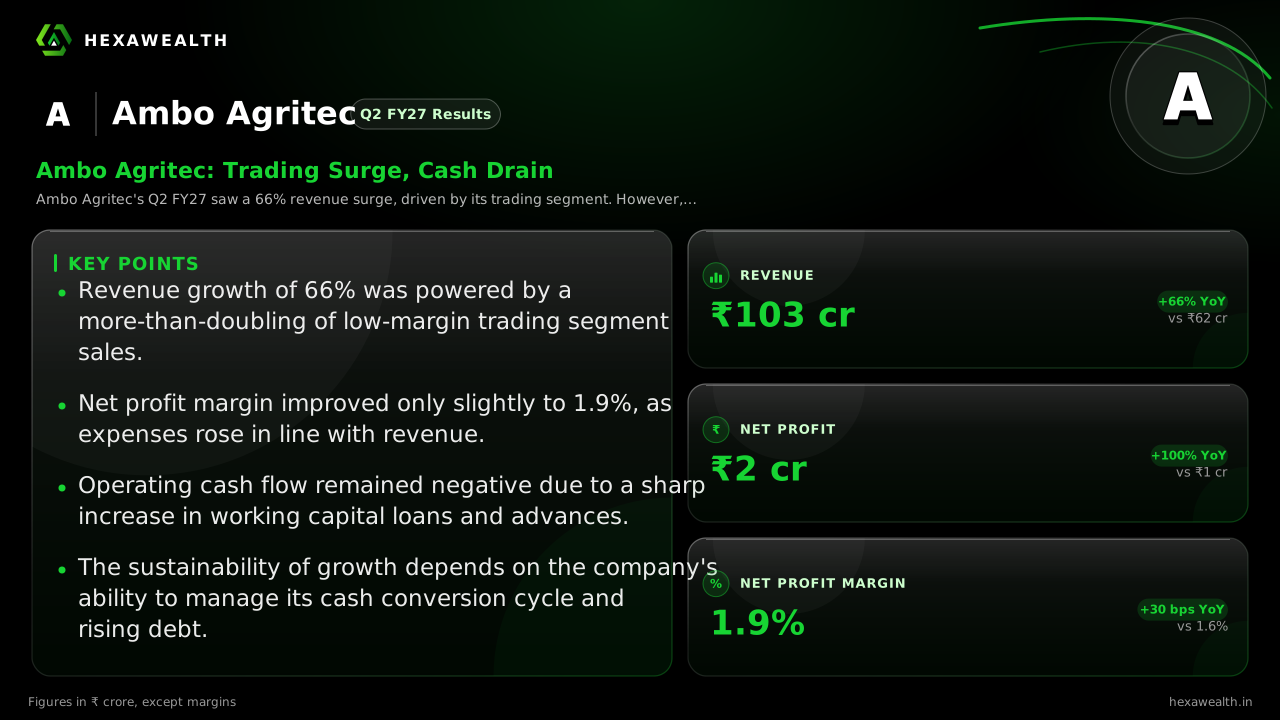
Ambo Agritec (AMBOAGRI) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Ambo Agritec's Q2 FY27 results?
Ambo Agritec reported Q2 FY27 revenue of ₹103 crore, a 66% increase year-on-year. Net profit for the quarter was ₹2 crore, doubling from the ₹1 crore profit in Q2 FY26. The net profit margin was 1.9%.
What was Ambo Agritec's net profit in Q2 FY27?
Ambo Agritec's net profit for Q2 FY27 (September 2026 quarter) was ₹2 crore. This represents a 100% increase from the ₹1 crore profit reported in the same quarter last year (Q2 FY26).
What was Ambo Agritec's revenue in Q2 FY27?
Ambo Agritec's revenue in Q2 FY27 was ₹103 crore. This is a significant 66.1% increase compared to the revenue of ₹62 crore reported in the September quarter of the previous fiscal year (Q2 FY26).
What drove Ambo Agritec's 66% revenue surge in Q2 FY27?
The revenue surge was driven almost entirely by the trading segment. According to a scanx.trade report, trading revenue more than doubled year-on-year to over ₹86 crore, while revenue from the company's biscuit manufacturing business declined during the quarter.
Why did Ambo Agritec's profit growth lag behind its revenue surge?
Profit growth lagged because the revenue boom came from the low-margin trading business. Expenses rose nearly as fast as sales (67% YoY), preventing significant operating leverage. This kept the net profit margin thin at 1.9%, only 30 basis points higher than a year ago.
What is Ambo Agritec's cash flow and working capital situation?
Ambo Agritec's cash flow situation weakened. Despite reporting a profit, operating cash flow was negative ₹3.5 crore for the half-year ending September 2026, as per MCapital. Cash reserves fell sharply as money was tied up in loans and advances to fund trading growth.
What guidance did Ambo Agritec management provide for FY27?
While no formal guidance was cited in results snippets, analyst projections based on the H1 run-rate suggest full-year FY27 revenue could reach ₹180-195 crore, a 40-50% increase over FY26. Profit is also projected to rise significantly from the previous year's low base.
Is Ambo Agritec undertaking any capacity expansion in biscuit manufacturing?
The research snippets did not highlight specific biscuit manufacturing capacity expansion in Q2. The company's recent strategic moves, per a scanx.trade report, include seeking shareholder approval to raise authorized capital and diversify into new business areas like electronics and beverages.
Did Ambo Agritec's Q2 FY27 results beat analyst estimates?
The available research does not mention specific consensus analyst estimates for Ambo Agritec's Q2 FY27 results. The company is a micro-cap stock with limited formal sell-side coverage, making a clear beat or miss difficult to ascertain from the provided information.
How did Ambo Agritec's stock price react to the Q2 results?
According to MCapital, Ambo Agritec's stock price rose 2.9% on November 16, 2026, following the results announcement. The analysis noted the market reaction was positive, weighing the strong revenue and profit growth against higher debt and negative cash flow.
Are mutual funds or FIIs increasing their stake in Ambo Agritec?
Institutional interest remains negligible. Shareholding data shows Foreign Institutional Investors (FIIs) held 0.00% and Domestic Institutional Investors (DIIs) held just 0.02% as of September 2026. Promoters hold 49.9% of the company.
Why did Ambo Agritec report a net loss in Q4 FY26?
Ambo Agritec reported a net loss of ₹1 crore in Q4 FY26 (March 2026 quarter). The provided research snippets do not specify the exact cause, but it followed a period of inconsistent profitability, as shown in the quarterly results table.
Ambo Agritec Q2 profit drop
Ambo Agritec did not report a profit drop in Q2 FY27 on a year-on-year basis; profit actually doubled to ₹2 crore. However, profit did decline significantly quarter-on-quarter, falling from the ₹-1 crore loss in Q4 FY26, which is a less meaningful comparison due to the prior quarter's loss.
Ambo Agritec Q2 net profit
Ambo Agritec's Q2 FY27 net profit was ₹2 crore. This result, for the quarter ended September 2026, marks a recovery from the net loss reported in the immediate preceding quarter (Q4 FY26) and is double the profit from Q2 FY26.