Jay Kailash (JAYKAILASH) Q2 FY27 Profit Saved by One-Off Income as Sales Halve
The snack maker's revenue fell 42% year-on-year, with profit cushioned by a surge in other income and a qualified audit raising concerns.
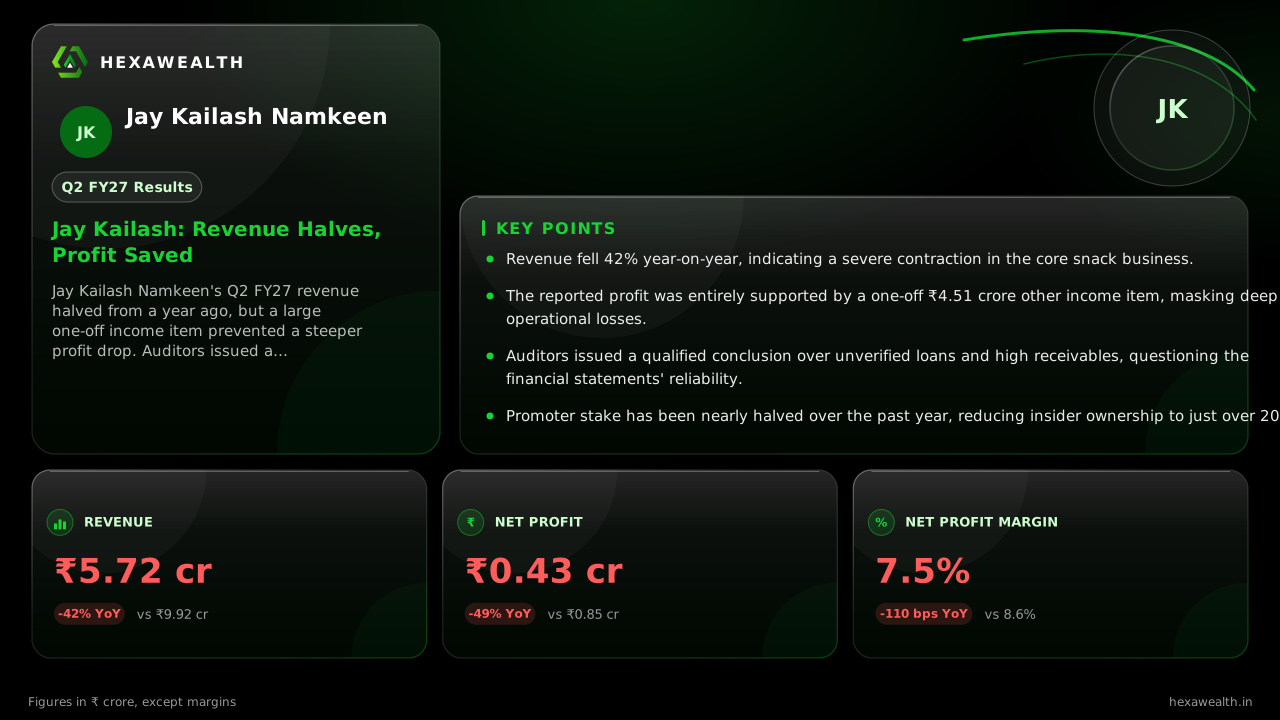
Jay Kailash Namkeen's Q2 FY27 revenue halved from a year ago, but a large one-off income item prevented a steeper profit drop. Auditors issued a qualified conclusion over unverified loans and receivables.
For a packaged snacks company, a sharp drop in sales volume is a direct challenge to its core business model. Jay Kailash Namkeen faced exactly that in the September quarter, with revenue nearly halving from a year earlier. The reported profit was propped up entirely by a one-time surge in other income, while auditors flagged significant concerns about the company's financial statements.
The numbers tell a story of deep top-line stress. Revenue fell 42% year-on-year to ₹5.72 crore, and was down 24% from the March quarter. Net profit of ₹0.43 crore was 49% lower than last year, though it improved 19% sequentially. The quarterly trend shows a business in retreat.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 8.81
- Revenue (₹ Cr), Q4 FY25: 6.22
- Revenue (₹ Cr), Q2 FY26: 9.92
- Revenue (₹ Cr), Q4 FY26: 7.55
- Revenue (₹ Cr), Q2 FY27: 5.72
- Profit (₹ Cr), Q2 FY25: 0.61
- Profit (₹ Cr), Q4 FY25: 0.61
- Profit (₹ Cr), Q2 FY26: 0.85
- Profit (₹ Cr), Q4 FY26: 0.36
- Profit (₹ Cr), Q2 FY27: 0.43
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 8.81
- Revenue (₹ Cr), Q4 FY25: 6.22
- Revenue (₹ Cr), Q2 FY26: 9.92
- Revenue (₹ Cr), Q4 FY26: 7.55
- Revenue (₹ Cr), Q2 FY27: 5.72
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.61
- Profit (₹ Cr), Q4 FY25: 0.61
- Profit (₹ Cr), Q2 FY26: 0.85
- Profit (₹ Cr), Q4 FY26: 0.36
- Profit (₹ Cr), Q2 FY27: 0.43
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 6.9
- Net Profit Margin (%), Q4 FY25: 9.8
- Net Profit Margin (%), Q2 FY26: 8.6
- Net Profit Margin (%), Q4 FY26: 4.8
- Net Profit Margin (%), Q2 FY27: 7.5
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 5.72YoY -42% | 9.92 |
| Profit (₹ Cr) | 0.43YoY -49% | 0.85 |
| Net Profit Margin (%) | 7.5YoY -13% | 8.6 |
Why the profit didn't collapse
The headline profit figure is misleading. According to reports from MarketsMojo and Flash Finance, the entire pre-tax profit of ₹0.60 crore came from a ₹4.51 crore surge in other income. The core snack business, after expenses, was deeply in the red. This other income, which the company has not detailed, was the sole reason the bottom line stayed positive.
A balance sheet under scrutiny
Beyond the weak operations, a qualified audit conclusion raises deeper questions. The statutory auditor, as reported by ForgeUp, stated the results do not give a true and fair view. This is due to unverified significant loans, advances, and outstanding trade receivables of ₹18.9 crore. With sales falling, these high receivables imply a severe working capital strain.
Promoter ownership has also fallen sharply, from 48% in September 2024 to just over 20% now, as noted by The Economic Times. This significant reduction in insider holding adds another layer of uncertainty for investors.
Live Chart
· JAYKAILASH
(BSE)
ISIN: INE0MSS01019
Key Points
- Revenue fell 42% year-on-year, indicating a severe contraction in the core snack business.
- The reported profit was entirely supported by a one-off ₹4.51 crore other income item, masking deep operational losses.
- Auditors issued a qualified conclusion over unverified loans and high receivables, questioning the financial statements' reliability.
- Promoter stake has been nearly halved over the past year, reducing insider ownership to just over 20%.
Hexa Perspective
This quarter reveals a company where reported earnings have detached from operational reality. The core snack business is shrinking rapidly, and the profit is an accounting artifact, not an operating achievement. The qualified audit and ballooning receivables on falling sales point to potential asset-quality issues that could pressure cash flows.
The path forward requires a credible recovery in sales volume and a resolution of the auditor's concerns. Until then, the headline profit offers little comfort, as it is neither repeatable nor indicative of the health of the underlying business. Investors are left weighing a broken operating model against a balance sheet whose key assets are under a cloud.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.