Ambo Agritec (AMBOAGRI) Q4 FY26's Revenue Gains Are Eaten by Rising Costs
The biscuit maker and trader posted higher annual sales, but a quarterly loss highlights persistent margin pressures from rising expenses.
Ambo Agritec's FY26 revenue grew 8.7%, but profit fell 18.8%. The March quarter saw a loss despite higher sales, as costs rose faster than income. The company's shift towards retail and trading is reshaping its business mix.
For Ambo Agritec, the story is one of top-line progress shadowed by a persistent struggle for profitability. The company, which blends biscuit manufacturing with agricultural commodity trading, saw its revenue climb for the full year. Yet the final quarter laid bare the cost pressures eroding the bottom line.
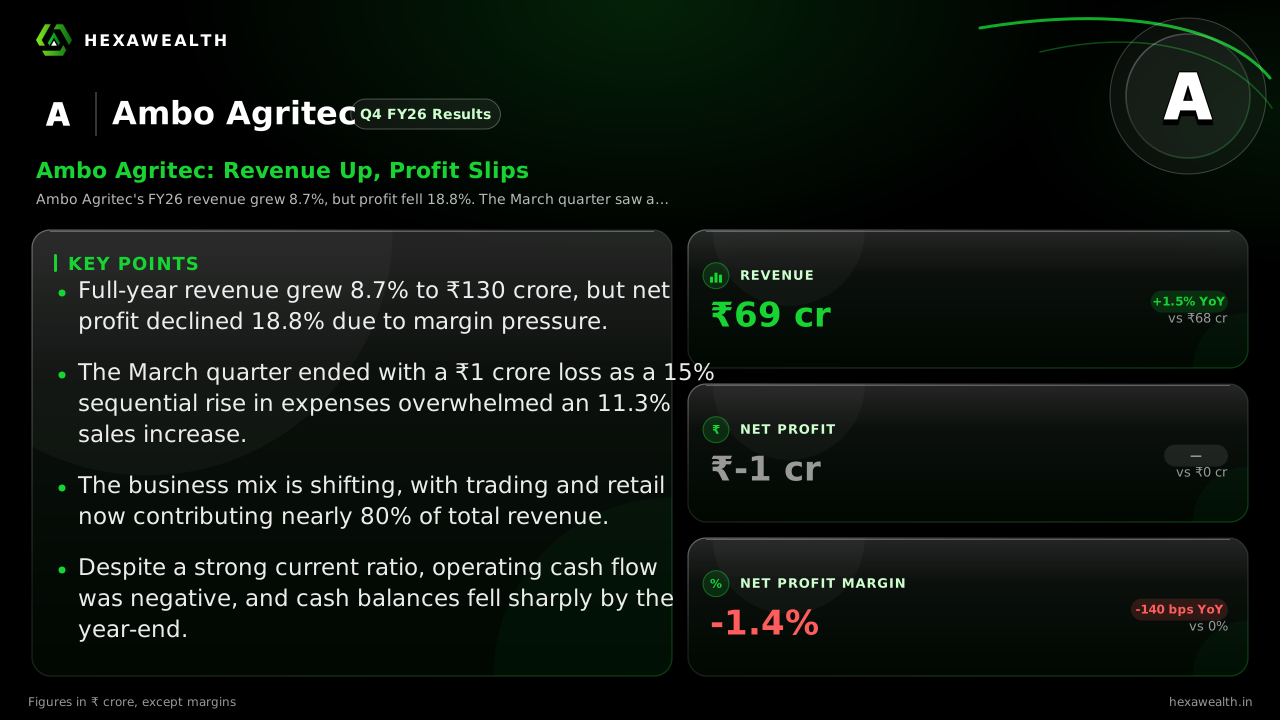
Annual revenue reached ₹130 crore, an 8.7% increase over the prior year. Profit, however, fell 18.8% to ₹1 crore. The tension was sharpest in the March quarter, where a ₹1 crore net loss arrived despite an 11.3% sequential sales rise to ₹69 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 52.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 62.0
- Revenue (₹ Cr), Q4 FY26: 69.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 0.0
- Profit (₹ Cr), Q2 FY26: 1.0
- Profit (₹ Cr), Q4 FY26: -1.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 52.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 62.0
- Revenue (₹ Cr), Q4 FY26: 69.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 0.0
- Profit (₹ Cr), Q2 FY26: 1.0
- Profit (₹ Cr), Q4 FY26: -1.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 1.9
- Net Profit Margin (%), Q4 FY25: 0.0
- Net Profit Margin (%), Q2 FY26: 1.6
- Net Profit Margin (%), Q4 FY26: -1.4
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 69.0YoY +1.5% | 68.0 |
| Profit (₹ Cr) | -1.0 | 0.0 |
| Net Profit Margin (%) | -1.4 | 0.0 |
Why the gains didn't reach the bottom line
Total expenses jumped 15% from the previous quarter, outpacing revenue growth and wiping out margins. A report from InvestorFeed notes the company's strategic shift is visible in its FY26 segment split: trading contributed nearly 50% of revenue, while the newer retail chain accounted for 27%.
This pivot may explain the margin volatility. Trading often operates on thin spreads, and building a retail footprint carries upfront costs. The company's annual report, cited by StockFin, confirms a focus on expanding retail outlets and strengthening manufacturing, with no dividend paid to conserve cash.
A liquidity squeeze beneath the surface
While the balance sheet shows a healthy current ratio, cash flow tells a different story. Research from ScanX Trade indicates a sharp depletion in cash balances by March 2026, with operating cash flow turning negative. This was driven by a significant increase in loans and advances, suggesting working capital is absorbing liquidity despite reported profits.
Live Chart
· AMBOAGRI
(BSE)
ISIN: INE0N6V01016
The road ahead
Management is preparing for growth, having recently approved a proposal to increase authorized share capital. The immediate future appears brighter, with H1 FY27 results already showing a strong rebound. According to Alfafinder, the company reported a 67.4% surge in revenue and a 28.6% rise in net profit for the half-year ended September 2026.
The key question is whether this recovery marks a sustainable turn or another peak in a volatile cycle. The company's ability to manage costs in its expanding retail business and navigate thin-margin trading will determine if annual profits can finally keep pace with sales.
Key Points
- Full-year revenue grew 8.7% to ₹130 crore, but net profit declined 18.8% due to margin pressure.
- The March quarter ended with a ₹1 crore loss as a 15% sequential rise in expenses overwhelmed an 11.3% sales increase.
- The business mix is shifting, with trading and retail now contributing nearly 80% of total revenue.
- Despite a strong current ratio, operating cash flow was negative, and cash balances fell sharply by the year-end.
Hexa Perspective
The quarter underscores Ambo Agritec's transition phase. Revenue growth is evident, but it is coming from lower-margin trading and capital-intensive retail expansion, not its core manufacturing. The 300-basis-point sequential margin collapse shows how quickly costs can overtake sales in this model.
The sharp rebound in H1 FY27 profits is encouraging but must be weighed against the company's history of volatility and negative operating cash flow. Investors are essentially betting that the retail foray will eventually generate operating leverage, a thesis that remains unproven. For now, the stock's premium valuation seems to discount a smoother path to profitability than the quarterly results deliver.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.