Swastika Castal (SWASTIKAAL) Q2 FY27 Profit Drops 13% Despite Strong Revenue Growth
The metal components maker posted a 26% yearly revenue jump, but a sharp sequential rise in expenses led to a quarterly profit decline and margin squeeze.
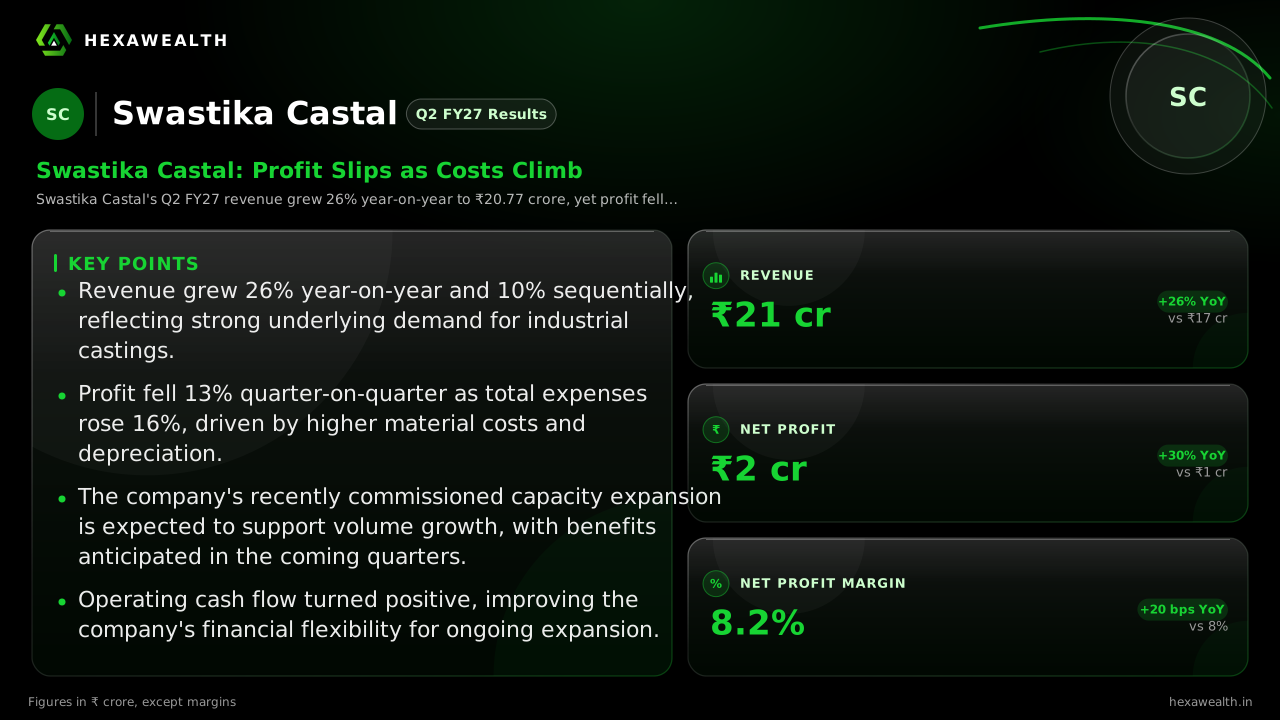
Swastika Castal's Q2 FY27 revenue grew 26% year-on-year to ₹20.77 crore, yet profit fell 13% from the previous quarter. The drop was driven by a 16% sequential rise in total expenses, outpacing sales growth and squeezing margins.
For a metal casting company, growth is a function of industrial demand and the ability to manage volatile input costs. Swastika Castal’s September quarter delivered the first part, with revenue climbing 26% year-on-year, but a sharp jump in expenses kept the reward from reaching the bottom line.
Revenue for Q2 FY27 came in at ₹20.77 crore, a 10% sequential increase. Profit, however, declined 13% from the March quarter to ₹1.71 crore. The net profit margin compressed to 8.2%, down 220 basis points from the previous quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 12.98
- Revenue (₹ Cr), Q4 FY25: 17.16
- Revenue (₹ Cr), Q2 FY26: 16.54
- Revenue (₹ Cr), Q4 FY26: 18.81
- Revenue (₹ Cr), Q2 FY27: 20.77
- Profit (₹ Cr), Q2 FY25: 0.39
- Profit (₹ Cr), Q4 FY25: 3.96
- Profit (₹ Cr), Q2 FY26: 1.32
- Profit (₹ Cr), Q4 FY26: 1.96
- Profit (₹ Cr), Q2 FY27: 1.71
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 12.98
- Revenue (₹ Cr), Q4 FY25: 17.16
- Revenue (₹ Cr), Q2 FY26: 16.54
- Revenue (₹ Cr), Q4 FY26: 18.81
- Revenue (₹ Cr), Q2 FY27: 20.77
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.39
- Profit (₹ Cr), Q4 FY25: 3.96
- Profit (₹ Cr), Q2 FY26: 1.32
- Profit (₹ Cr), Q4 FY26: 1.96
- Profit (₹ Cr), Q2 FY27: 1.71
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 3.0
- Net Profit Margin (%), Q4 FY25: 23.1
- Net Profit Margin (%), Q2 FY26: 8.0
- Net Profit Margin (%), Q4 FY26: 10.4
- Net Profit Margin (%), Q2 FY27: 8.2
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 20.77YoY +26% | 16.54 |
| Profit (₹ Cr) | 1.71YoY +30% | 1.32 |
| Net Profit Margin (%) | 8.2YoY +2.5% | 8.0 |
Why the margin squeeze hit now
The primary driver was a 16% quarter-on-quarter rise in total expenses, which outpaced the 10% revenue growth. According to a report from Multibagg.ai, the cost of materials consumed rose sharply to ₹11.45 crore from ₹9.25 crore in the prior quarter. Depreciation also jumped 39%, likely linked to the commissioning of new capacity.
This suggests the company is spending to grow, but the immediate financial benefit is lagging. The operating environment remains supportive, with reports like IndexBox forecasting 6-9% annual growth for India's iron and steel casting market through 2035, driven by automotive and infrastructure demand.
The path to better profitability
Management has signaled that the recent capacity expansion, commissioned in March 2026, is now operational. A report from ScanX.Trade notes the company expects benefits to become visible in the near term. The key will be improving capacity utilization from the reported 57% and managing input cost volatility.
Live Chart
· SWASTIKAAL
(BSE)
ISIN: INE0PTF01017
A positive shift is visible in cash flow. The company generated net operating cash inflow of ₹1.04 crore for the half-year, a significant improvement from an outflow of ₹8.72 crore a year earlier, as noted by Multibagg.ai. This provides a stable base for funding its growth plans.
Key Points
- Revenue grew 26% year-on-year and 10% sequentially, reflecting strong underlying demand for industrial castings.
- Profit fell 13% quarter-on-quarter as total expenses rose 16%, driven by higher material costs and depreciation.
- The company's recently commissioned capacity expansion is expected to support volume growth, with benefits anticipated in the coming quarters.
- Operating cash flow turned positive, improving the company's financial flexibility for ongoing expansion.
Hexa Perspective
The quarter presents a classic growth-versus-margin tension. Swastika Castal is successfully capturing higher demand, but profitability is being tested by the costs of scaling up. The margin compression from 10.4% to 8.2% sequentially is a meaningful signal that the expansion phase is pressuring near-term earnings.
The investment case now hinges on execution. If the newly operational capacity can be utilized efficiently, it should provide operating leverage to offset the current cost pressure. Investors are effectively betting that today's margin squeeze is a temporary cost of building a larger, more profitable business for the sustained industrial upcycle ahead.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.