Nilachal Carbo Metalicks (NCML) Q2 FY27 Sees Profit Margin Rise as Revenue Halves
The ferrochrome maker's revenue fell sharply after exiting its trading business, but a tighter cost structure lifted its net profit margin.
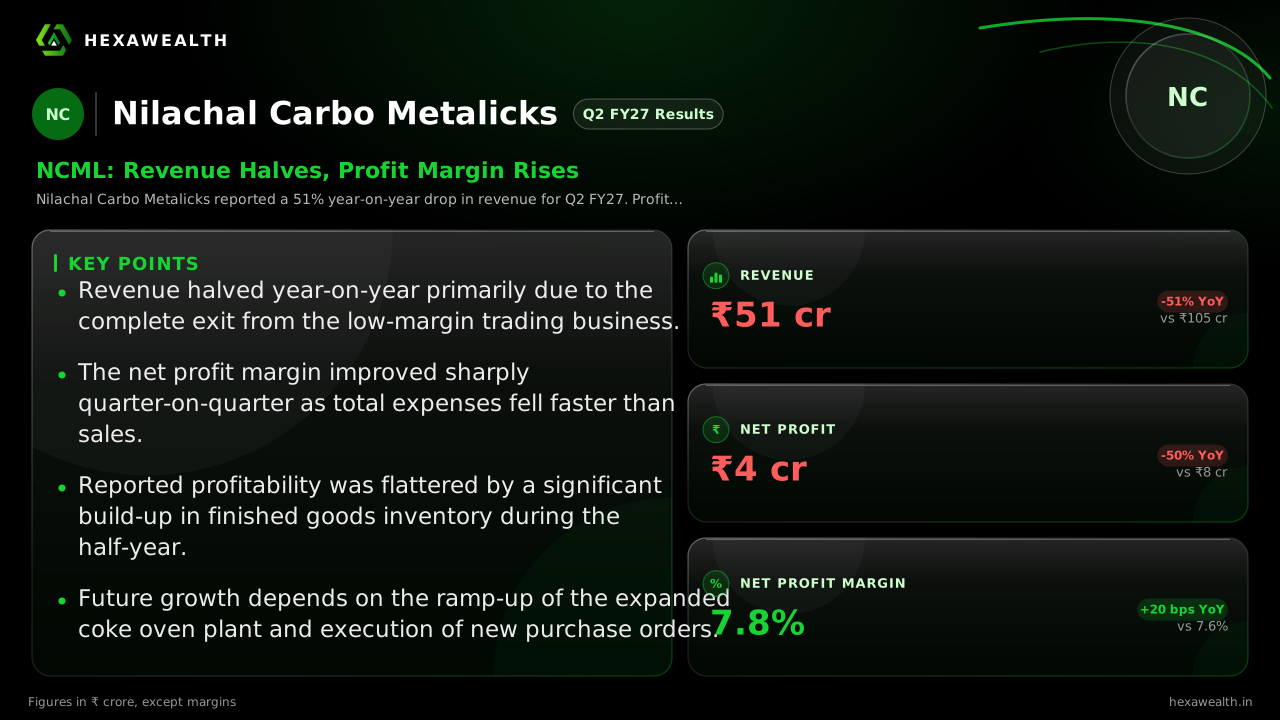
Nilachal Carbo Metalicks reported a 51% year-on-year drop in revenue for Q2 FY27. Profit fell 50%, but the net profit margin improved as the company exited a low-margin trading segment.
For a ferrochrome and sponge iron maker, the top line is a direct read on market demand and its own sales mix. Nilachal Carbo Metalicks' September quarter shows what happens when a major revenue stream vanishes, leaving the core manufacturing business to carry the load.
Revenue fell to ₹51 crore, down 51% from a year ago. Profit halved to ₹4 crore. The quarter-on-quarter comparison tells a different story: profit rose 33% even as revenue fell 47%, a sign of a sharply changed cost base.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 99.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 105.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 96.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 51.0
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 6.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 8.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 4.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 99.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 105.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 96.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 51.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 6.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 8.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 3.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 4.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25 (Sep 2024): 6.1
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 7.6
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 3.1
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 7.8
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 51.0 | 96.0 |
| Profit (₹ Cr) | 4.0 | 3.0 |
| Net Profit Margin (%) | 7.8 | 3.1 |
The trading book disappears
According to a report from StockWatch, the revenue decline traces almost entirely to the disappearance of the trading business. Purchases of stock-in-trade, which accounted for ₹58.61 crore in the first half of last year, fell to zero this year. This explains the steep top-line drop against a smaller 44% fall in the core cost of materials consumed.
Exiting this low-margin segment had an immediate effect on profitability. Total expenses fell faster than revenue, dropping 52% year-on-year. Finance costs and depreciation also declined, consistent with a smaller, less working-capital-intensive operation.
A margin flattered by inventory
While the exit from trading helped, the reported net profit margin of 7.8% also benefited from a one-off swing. The same StockWatch analysis notes a significant build-up in finished goods inventory this half versus a drawdown last year. This accounting credit lowered the recognised cost of goods sold, flattering the bottom line.
Live Chart
· NCML
(BSE)
ISIN: INE346R01013
Stripping out this inventory swing, the report suggests the half-year's pretax profit would have been a loss. This means the reported profitability depends on unsold stock sitting in inventory rather than converted sales.
The outlook hinges on new orders
The company's future now rests on its core manufacturing. According to InvestorFeed, it has secured a purchase order for 10,000 MT in October 2026 and is targeting capacity utilisation up to 85%. Its recently expanded coke oven plant, funded almost entirely by IPO proceeds, is slated for a commercial start in Q1 FY27.
Market conditions offer a mixed backdrop. A SMM Analysis notes Indian sponge iron prices have risen to a two-year high, driven by raw material costs. However, ferrochrome prices in China have been under pressure, with steel mills cutting tender prices.
Key Points
- Revenue halved year-on-year primarily due to the complete exit from the low-margin trading business.
- The net profit margin improved sharply quarter-on-quarter as total expenses fell faster than sales.
- Reported profitability was flattered by a significant build-up in finished goods inventory during the half-year.
- Future growth depends on the ramp-up of the expanded coke oven plant and execution of new purchase orders.
Hexa Perspective
This quarter marks a reset. Nilachal Carbo Metalicks is now a pure manufacturing play, having shed a large but low-quality revenue stream. The improved margin is a structural positive, but it comes atop a much smaller base.
The valuation, at a PE of 23.2 against an industry average of 8.2, prices in a swift recovery that is not yet evident in the numbers. Investors are betting the new capacity will quickly fill the revenue gap left by trading. That bet must pay off in the coming quarters for the current premium to hold.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.