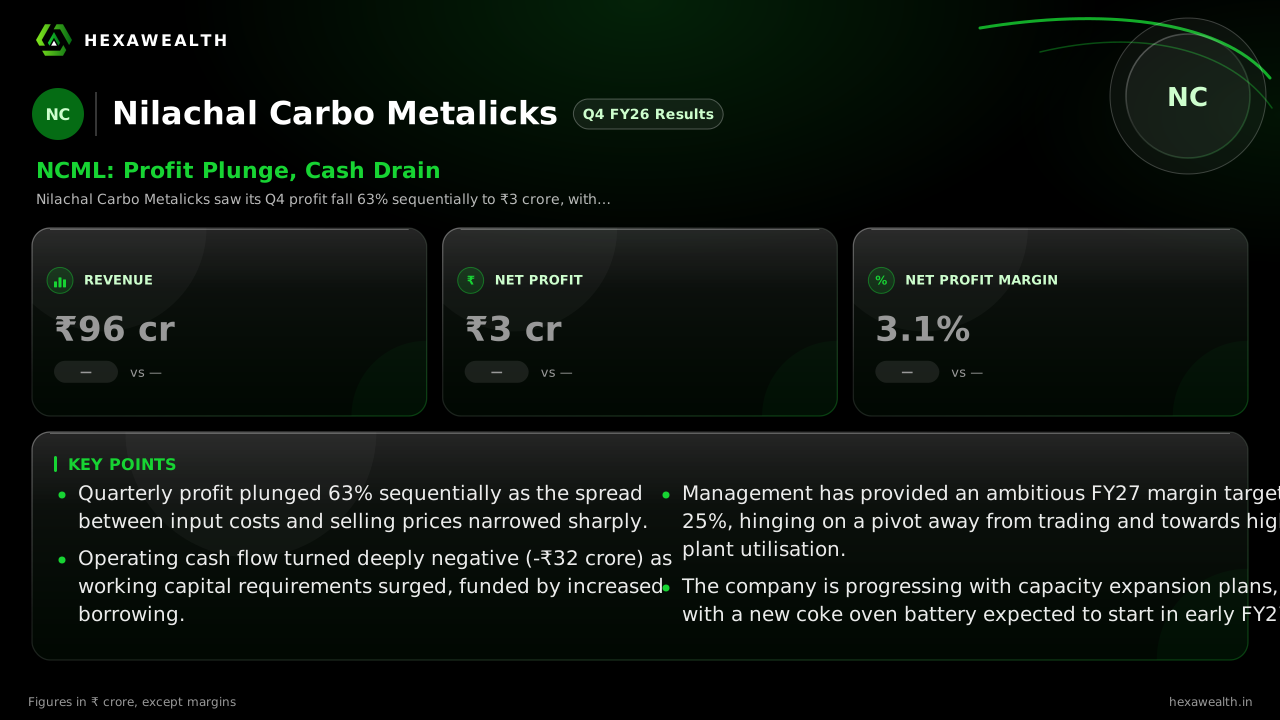
Nilachal Carbo Metalicks (NCML) Q4 FY26 Profit Plunges 63% as Cash Flow Turns Negative
The ferro chrome maker's quarterly profit fell sharply despite a modest revenue dip, while its cash flow turned deeply negative as working capital swelled.
Nilachal Carbo Metalicks saw its Q4 profit fall 63% sequentially to ₹3 crore, with margins contracting sharply. The company's operating cash flow turned deeply negative for the full year, highlighting a growing working capital strain.
For a commodity producer like Nilachal Carbo Metalicks, the spread between input costs and selling prices is everything. The March quarter saw that spread compress severely, turning a modest sales dip into a sharp profit drop and exposing a deeper cash flow problem.
Revenue for Q4 FY26 was ₹96 crore, down 9% from the September quarter. Profit after tax fell 63% to just ₹3 crore, dragging the net profit margin down by 450 basis points to 3.1%. For the full year, revenue was nearly flat at ₹200.4 crore, but profit fell 25% to ₹10.54 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 99.0
- Revenue (₹ Cr), Q2 FY26: 105.0
- Revenue (₹ Cr), Q4 FY26: 96.0
- Profit (₹ Cr), Q2 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q4 FY26: 3.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 99.0
- Revenue (₹ Cr), Q2 FY26: 105.0
- Revenue (₹ Cr), Q4 FY26: 96.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q4 FY26: 3.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 6.1
- Net Profit Margin (%), Q2 FY26: 7.6
- Net Profit Margin (%), Q4 FY26: 3.1
| Metric | CurrentQ4 FY26 |
|---|---|
| Revenue (₹ Cr) | 96.0 |
| Profit (₹ Cr) | 3.0 |
| Net Profit Margin (%) | 3.1 |
The squeeze that sank margins
A report from newboard.in explains the core issue: the company's margin is the spread between imported coking coal and the coke it sells. Price falls in coal must be passed on immediately, while price rises reach customers only with a lag. With no long-term contracts, this lag creates volatility. In FY26, a significant ₹58.9 crore of revenue came from trading goods, not its own production, which kept sales steady while its plant ran at half capacity.
This shift in mix, from manufacturing to trading, likely contributed to the operating margin pressure seen in the second half. According to data from mcapital.in, the operating profit margin for the March quarter was just 8%, down from 13% in the September quarter.
A cash flow problem that’s getting worse
The real story, however, is on the balance sheet. Operating cash flow for FY26 was a deeply negative ₹32 crore, a stark reversal from the prior year. This was driven by a massive ₹50 crore increase in working capital. Newboard.in notes that advances to suppliers ballooned to ₹36 crore and receivables rose sharply, indicating cash is getting stuck in the supply chain.
Live Chart
· NCML
(BSE)
ISIN: INE346R01013
To fund this growing working capital need, the company borrowed more. Borrowings rose by ₹15 crore in FY26 to ₹38.6 crore. Shareholders recently approved raising the aggregate borrowing limit to ₹75 crore, as reported by scanx.trade.
A pivot back to the core business?
Management's outlook, cited by knowyourcompany.ai, points to a potential shift. They guided for FY27 revenue of ₹210-220 crore and a net profit margin of 25%. This ambitious margin target suggests a move away from low-margin trading. The anti-dumping duty on imported low ash coke, noted by Investor Feed, could also support domestic producers like NCML.
Furthermore, the company is focusing on its core manufacturing expansion. Investor Feed reported it has secured orders and is targeting 85% capacity utilisation. A coke oven expansion is slated for a commercial start in Q1 FY27.
Key Points
- Quarterly profit plunged 63% sequentially as the spread between input costs and selling prices narrowed sharply.
- Operating cash flow turned deeply negative (-₹32 crore) as working capital requirements surged, funded by increased borrowing.
- Management has provided an ambitious FY27 margin target of 25%, hinging on a pivot away from trading and towards higher plant utilisation.
- The company is progressing with capacity expansion plans, with a new coke oven battery expected to start in early FY27.
Hexa Perspective
The quarter reveals a business caught between two models. The trading activity that propped up revenue is a cash drain, while its own manufacturing runs below potential. The promised margin recovery in FY27 depends entirely on executing the shift back to higher-margin production and ramping up the new capacity on schedule. Investors are weighing the steep valuation—a P/E of 23.5 against an industry average of 8.3—against this high-stakes transition. The next few quarters will show if the company can convert its guidance into the operating leverage and cash generation the stock price implies.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.